
Quiz
Chapter 4 - Compensation
Create a free account to finish this quiz
Save your progress and see your final score.
Already have an account? Sign in
Questions in this quiz (15)
1IRC §415 compensation must include elective deferrals to a 401(k) plan.
- ATrue
- BFalse
2The average percentage of total compensation that is considered for NHCEs must be at least 70 percent of the average percentage of total compensation considered for HCEs in order for the definition of compensation to satisfy IRC §414(s).
- ATrue
- BFalse
3The plan’s definition of compensation used for allocating contributions must satisfy the nondiscriminatory definition of compensation under IRC §414(s).
- ATrue
- BFalse
4IRC §414(s) compensation must include elective deferrals to a 401(k) plan to avoid testing that definition for nondiscrimination.
- ATrue
- BFalse
5IRC §415 compensation must be used to determine HCEs.
- ATrue
- BFalse
6IRC §414(s) compensation must be used to determine key employees.
- ATrue
- BFalse
7IRC §415 compensation must not include tips, depending on how IRC §415 compensation is defined.
- ATrue
- BFalse
8Designated Roth contributions are included in IRC §415 compensation.
- ATrue
- BFalse
9Excluding nontaxable fringe benefits from IRC §415 compensation is a safe harbor modification to IRC §414(s) compensation, meaning the resulting definition will not need to be tested for nondiscrimination purposes.
- ATrue
- BFalse
10IRC §415 compensation is based on the plan year.
- ATrue
- BFalse
11All of the following statements regarding IRC §414(s) compensation are TRUE, EXCEPT:
- AA. A plan using a safe harbor definition of IRC §414(s) compensation for nondiscrimination testing need not perform the compensation ratio test.
- BB. A plan using a nonsafe harbor definition of IRC §414(s) compensation for nondiscrimination testing must apply such definition consistently for all participants.
- CC. A plan may meet the safe harbor definition of IRC §414(s) compensation by including 401(k) elective deferrals and excluding 125 plan elective deferrals.
- DD. A plan may use a 12-month period other than the plan year for purposes of determining IRC §414(s) compensation.
- EE. A plan may use a rate-of-pay definition of compensation for IRC §414(s) purposes.
12All of the following exclusions are deemed reasonable for defining IRC §414(s) compensation, EXCEPT:
- AA. 20 percent of regular compensation
- BB. Bonuses
- CC. Overtime
- DD. Expense allowances
- EE. Fringe benefits
13Based on the following information, determine the participant’s IRC §415 compensation:
The employer sponsors a 401(k) plan that allows designated Roth contributions.
The plan excludes overtime for allocation purposes.
The participant’s taxable income, not including elective deferrals, is $58,000.
The participant defers $4,000 as pre-tax elective deferrals and $4,000 as designated Roth contributions.
The participant defers $500 into the employer’s IRC §125 plan.
The participant’s overtime compensation totals $3,000.- AA. $58,000
- BB. $59,500
- CC. $62,500
- DD. $66,500
- EE. $69,500
14All of the following statements regarding the calculation of the employer deduction are true, EXCEPT:
- AA. In the case of a short taxable year, the deduction limit for a defined contribution plan is applied to aggregate participant compensation paid for the short period.
- BB. A short taxable year results in a prorated compensation dollar limit under IRC §401(a)(17).
- CC. A short plan year does not directly affect the defined contribution deduction limit because that deduction limit is based on participant compensation for the employer’s taxable year.
- DD. Compensation for deduction purposes is measured on the basis of the employer’s taxable year, whereas compensation for IRC §415 purposes is measured on the basis of the limitation year.
- EE. The definition of compensation used for allocation purposes must be the same as the definition of compensation used for deduction purposes.
15Based on the following information, which of the following statements regarding the compensation ratio is/are TRUE?
I. The plan passes the compensation ratio test.
II. The compensation ratio for the HCEs is 81.5%.
III. The compensation ratio for the NHCEs is 93.3%.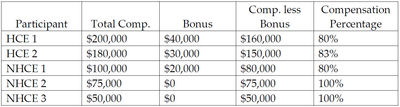
- AA. I only
- BB. II only
- CC. I and II only
- DD. II and III only
- EE. I, II and III
Information
- Description
- DC3 DC3 Quiz on Chapter 4 - Compensation, created by Justin Guy (just on 21/10/2015.
- Author
- Justin Guy (just
- Language
- English
- Views
- 45
- Tags
- Rating
- No ratings yet Rate this quiz