
Flussdiagramm
Trust
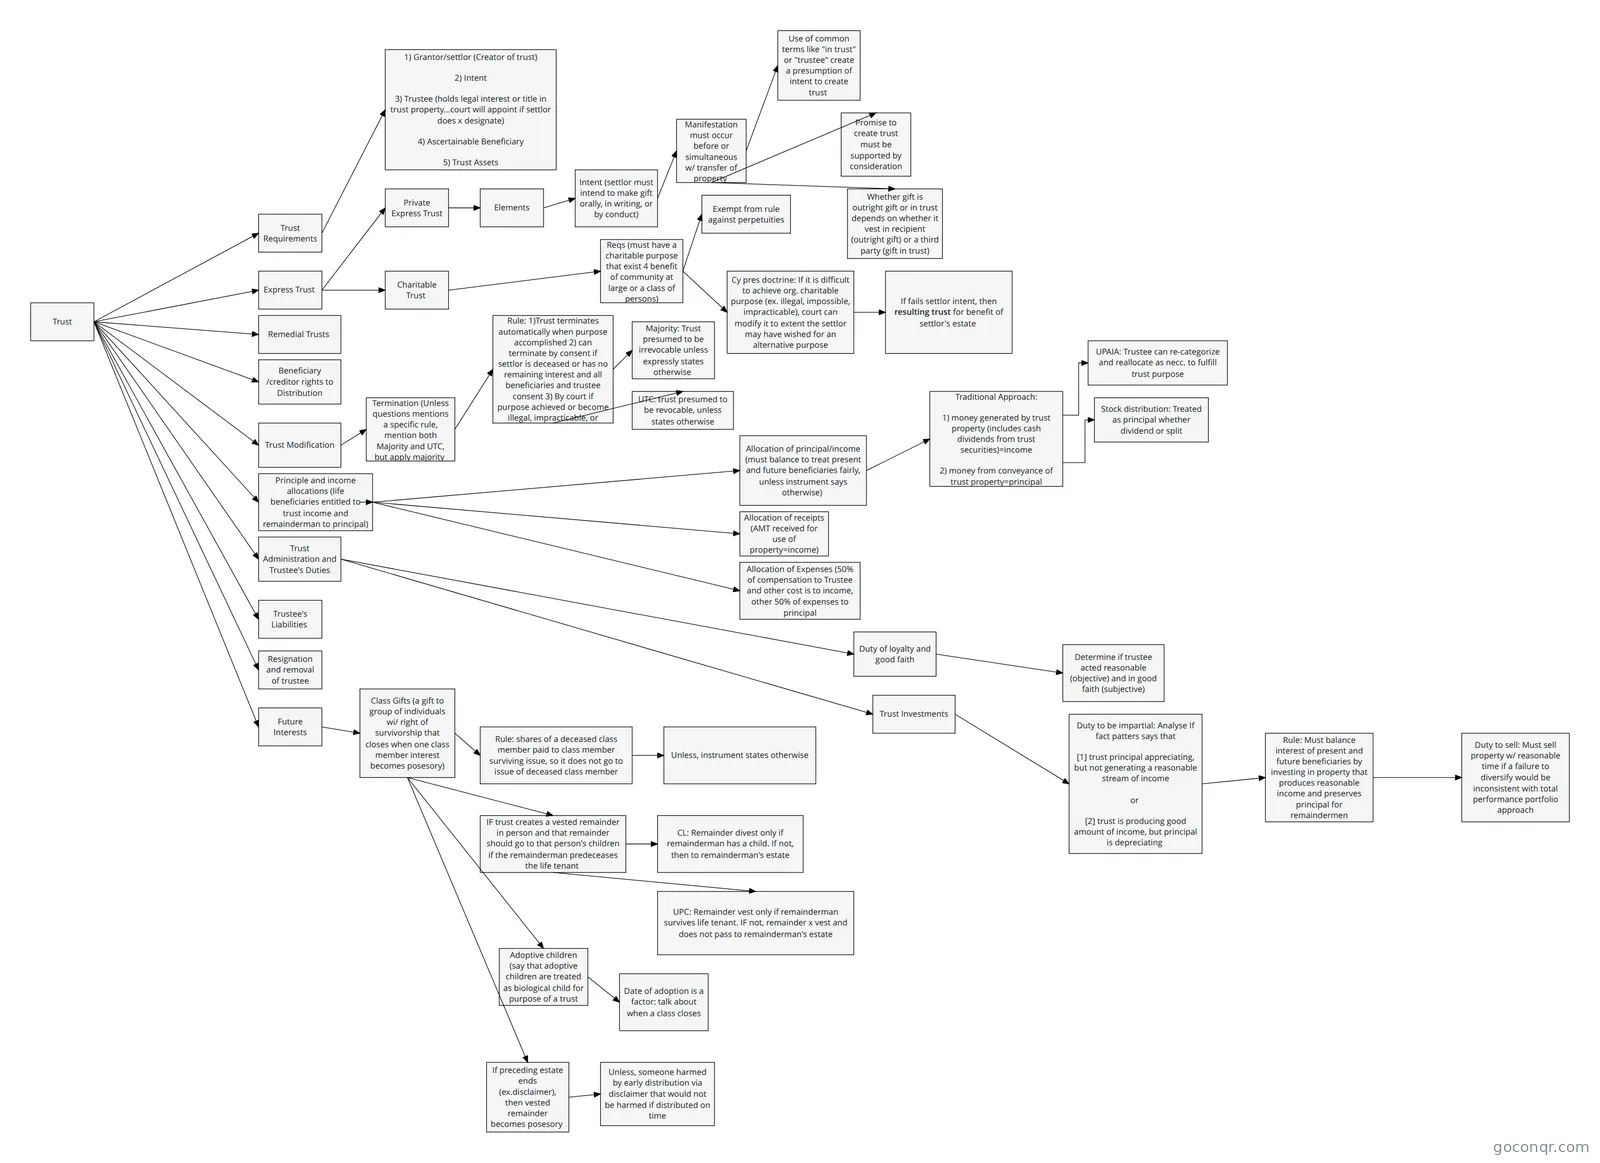
Flowchart: Trust law flowchart
Inhalt des Flussdiagramms
Trust
Trust Requirements
1) Grantor/settlor (Creator of trust)
2) Intent
3) Trustee (holds legal interest or title in trust property...court will appoint if settlor does x designate)
4) Ascertainable Beneficiary
5) Trust Assets
Express Trust
Remedial Trusts
Beneficiary /creditor rights to Distribution
Trust Modification
Principle and income allocations (life beneficiaries entitled to trust income and remainderman to principal)
Trust Administration and Trustee's Duties
Trustee's Liabilities
Future Interests
Resignation and removal of trustee
Termination (Unless questions mentions a specific rule, mention both Majority and UTC, but apply majority
Rule: 1)Trust terminates automatically when purpose accomplished 2) can terminate by consent if settlor is deceased or has no remaining interest and all beneficiaries and trustee consent 3) By court if purpose achieved or become illegal, impracticable, or impossible
Majority: Trust presumed to be irrevocable unless expressly states otherwise
UTC: trust presumed to be revocable, unless states otherwise
Private Express Trust
Elements
Intent (settlor must intend to make gift orally, in writing, or by conduct)
Manifestation must occur before or simultaneous w/ transfer of property
Use of common terms like "in trust" or "trustee" create a presumption of intent to create trust
Whether gift is outright gift or in trust depends on whether it vest in recipient (outright gift) or a third party (gift in trust)
Promise to create trust must be supported by consideration
Charitable Trust
Reqs (must have a charitable purpose that exist 4 benefit of community at large or a class of persons)
Exempt from rule against perpetuities
Cy pres doctrine: If it is difficult to achieve org. charitable purpose (ex. illegal, impossible, impracticable), court can modify it to extent the settlor may have wished for an alternative purpose
If fails settlor intent, then resulting trust for benefit of settlor's estate
Duty of loyalty and good faith
Determine if trustee acted reasonable (objective) and in good faith (subjective)
Trust Investments
Duty to be impartial: Analyse If fact patters says that
[1] trust principal appreciating, but not generating a reasonable stream of income
or
[2] trust is producing good amount of income, but principal is depreciating
Rule: Must balance interest of present and future beneficiaries by investing in property that produces reasonable income and preserves principal for remaindermen
Duty to sell: Must sell property w/ reasonable time if a failure to diversify would be inconsistent with total performance portfolio approach
Class Gifts (a gift to group of individuals wi/ right of survivorship that closes when one class member interest becomes posesory)
Rule: shares of a deceased class member paid to class member surviving issue, so it does not go to issue of deceased class member
Unless, instrument states otherwise
IF trust creates a vested remainder in person and that remainder should go to that person's children if the remainderman predeceases the life tenant
CL: Remainder divest only if remainderman has a child. If not, then to remainderman's estate
UPC: Remainder vest only if remainderman survives life tenant. IF not, remainder x vest and does not pass to remainderman's estate
Adoptive children (say that adoptive children are treated as biological child for purpose of a trust
Date of adoption is a factor: talk about when a class closes
Allocation of principal/income (must balance to treat present and future beneficiaries fairly, unless instrument says otherwise)
Allocation of Expenses (50% of compensation to Trustee and other cost is to income, other 50% of expenses to principal
Allocation of receipts (AMT received for use of property=income)
UPAIA: Trustee can re-categorize and reallocate as necc. to fulfill trust purpose
Stock distribution: Treated as principal whether dividend or split
Traditional Approach:
1) money generated by trust property (includes cash dividends from trust securities)=income
2) money from conveyance of trust property=principal
If preceding estate ends (ex.disclaimer), then vested remainder becomes posesory
Unless, someone harmed by early distribution via disclaimer that would not be harmed if distributed on time
Informationen
- Beschreibung
- Flussdiagramm am Trust, erstellt von Alan Santana am 17/02/2020.
- Erstellt von
- Alan Santana
- Aufrufe
- 5
- Bewertung