
Karteikarten
Chapter 4: Balance sheet
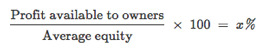
Karten in diesem Stapel (30)
- 1Financial reporting obligations in Australia- Companies registered in Australia must report to the Australian Securities and Investments Commission (ASIC)
- Charities registered in Australia must report to the Australian Charities and Not-for-profits Commission (ACNC)
- For other entities (e.g. partnerships, sole traders), there is no legal requirement to prepare financial statements - 2Reporting entity concept- Reporting entity - an entity with users who rely on the information in GPFS's to meet their information needs
- Factors include size, indebtedness, separation of management and ownership, and economic / political significance - 3Differential reporting regime: IFRS for SME's- IFRS for SME's simplifies the recognition and measurement rules
- Reduces burden on SME's that do not have public accountability but are publishing GPFS's
- Public accountability - refers to entities with securities, debt or equity, traded in a public market - 4Differential reporting in Australia- Australia does not follow IFRS for SME's but allows IFRS with reduced disclosure requirements
- Entities required to follow full IFRS: all for-profit private sector entities that have public accountability, all governments, universities
- Entities able to follow IFRS with reduced disclosure requirements: all for-profit private sector entities that do not have public accountability, all not-for-profit private sector entities - 5Balance sheet / statement of financial position- Financial statement reporting the assets, liabilities and equity of an entity at a particular point in time
- Prepared semi-annually or annually at end of reporting period (but can be more regularly)
- Presents both previous and current periods (comparative) - 6Balance sheet components1. Assets - what the entity owns (or controls) as at a particular date
2. Liabilities - external claims on the entity’s assets
3. Equity - internal claim on the entity’s assets - 7Purpose of balance sheetEnables users to make a preliminary assessment of an entity's financial position and solvency by identifying:
- Types of assets in which it invests (investing decisions)
- Use of liabilities relative to equity to finance the assets (financing decisions) - 8Link to other financial statements- Info about debt can help guide an investment decision
- Info about assets can provide insight into business operations and ability to generate cash flow - 9T-format- Used by smaller entities
- Assets on left-hand side; liabilities and equity on right-hand side
- Based on A = L + OE - 10Narrative format- Used by larger entities
- Assets, liabilities and equity are presented down the page
- Assets first (current before non-current), followed by liabilities (current before non-current), and then equity
- Based on A - L = OE - 11Group entity- If a company controls other entities, the balance sheet is presented for the group as a single economic entity
- Balance sheet reports combined assets, liabilities and equity for the parent entity and subsidiaries (inter-company transactions are eliminated) - 12Current vs non-current assetsBased on timing of future economic benefits:
- Current assets - cash and other assets expected to be converted to cash or used in the entity within one operating cycle (usually a year) e.g. inventory
- Non-current assets - assets not expected to be consumed or sold within one operating cycle e.g. machinery - 13Current vs non-current liabilitiesBased on timing of expected future sacrifices:
- Current liabilities - obligations expected to be paid within one operating cycle
- Non-current liabilities - obligations expected to be paid outside one operating cycle - 14Aggregation of assets, liabilities and equity- Asset classes e.g. cash; receivables; investments; property, plant and equipment; intangible assets; tax assets
- Liability classes e.g. payables, borrowings, tax liabilities and provisions
- Equity classes e.g. share /contributed capital, reserves, retained earnings / profits, and non-controlling interests - 15Carrying amount / book valueDollar value assigned to an asset or liability on the balance sheet
- 16Historical cost- For an asset: the cash or cash equivalents paid to acquire the asset
- For a liability: the amount of proceeds received in exchange for the obligation - 17Current cost- For an asset: the cash or cash equivalents that would have to be paid to replace the asset
- For a liability: the undiscounted amount of cash or cash equivalents that would be required to settle the obligation currently - 18Realisable (settlement) value- For an asset: the expected cash or cash equivalents from selling the asset in an orderly disposal
- For a liability: the settlement value required to be paid in the normal course of business - 19Present value- For an asset: the present discounted net cash flows associated with the asset
- For a liability: the present discounted value of the future net cash flows that are expected to be required to settle the liabilities in the normal course of business - 20Cost-flow assumption- Under a periodic system there is no running balance of the inventory on hand or cost price of the inventory sold
- An assumption must be made using
one of two IFRS-approved methods:
1. First-in, first-out (FIFO)
2. Weighted-average - 21Intangible assetsNon-current, non-monetary assets that do not have physical substance
1. Identifiable intangible assets - can be separated or divided from an entity, or must arise from legal rights e.g. trademarks, brand names, franchises, rights, agreements, licences
2. Unidentifiable intangible assets (goodwill) - cannot be separated from the entity e.g. established client base, reputation - 22Some measurement rules- Receivables must be measured at their net amount i.e. gross value - allowance for doubtful debts
- Inventory must be measured at the lower of cost or net realisable value (promotes conservatism in presentation)
- Non-current assets with finite lives must be depreciated / amortised except for land - 23Recognition of goodwill- Only recognised as an asset in balance sheet if it has been acquired (purchased)
- At acquisition, it is recorded as the excess of historic cost over the fair value of the net assets acquired
- After acquisition, goodwill must be tested for impairment at least once annually (if impaired, value of goodwill is written down and impairment expense is recognised in the income statement) - 24Net realisable amountExpected selling price - expected costs of getting the inventory to a saleable state + costs of marketing, selling and distribution
- 25ImpairmentWhen an asset’s carrying value exceeds its recoverable amount
- Non-current assets carried at cost or written down cost must not have a carrying amount greater than their recoverable amount - 26Balance sheet is not a reflection of an entity’s value because...- Items creating value may not be recorded (as they fail definition / recognition criteria)
- Assets and liabilities can be measured differently (e.g. historical vs fair cost)
- No consideration is given to differences in cost prices due to changes in the purchasing power of money / inflation
- Preparation of balance sheet involves choices, assumptions and estimations on behalf of the manager / preparer
- Balance sheet is a historical representation (future earnings and growth potential can influence value) - 27Ratio analysis- Compares items in financial statements to determine their size relative to one another
- Ratios that relate profit earned to components of the balance sheet e.g. return on equity and return on assets
- Ratios that analyse the balance sheet on its own e.g. capital structure - 28Return on equity (ROE)
- 29Return on assets (ROA)
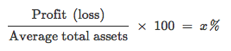
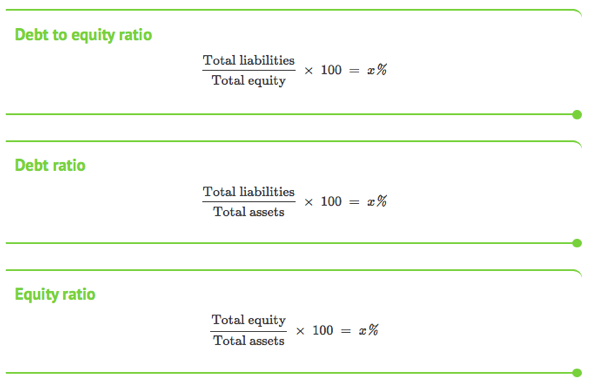
- 30Capital structure ratiosGearing ratios that measure how an entity finances its investments in assets i.e. proportion of debt to equity
Informationen
- Beschreibung
- Business/Economics (ACC1200: Accounting for Managers) Karteikarten am Chapter 4: Balance sheet, erstellt von Melina Mackey am 21/04/2018.
- Erstellt von
- Melina Mackey
- Aufrufe
- 6
- Bewertung