
Mindmap
Auditors Reports- referencing other matters
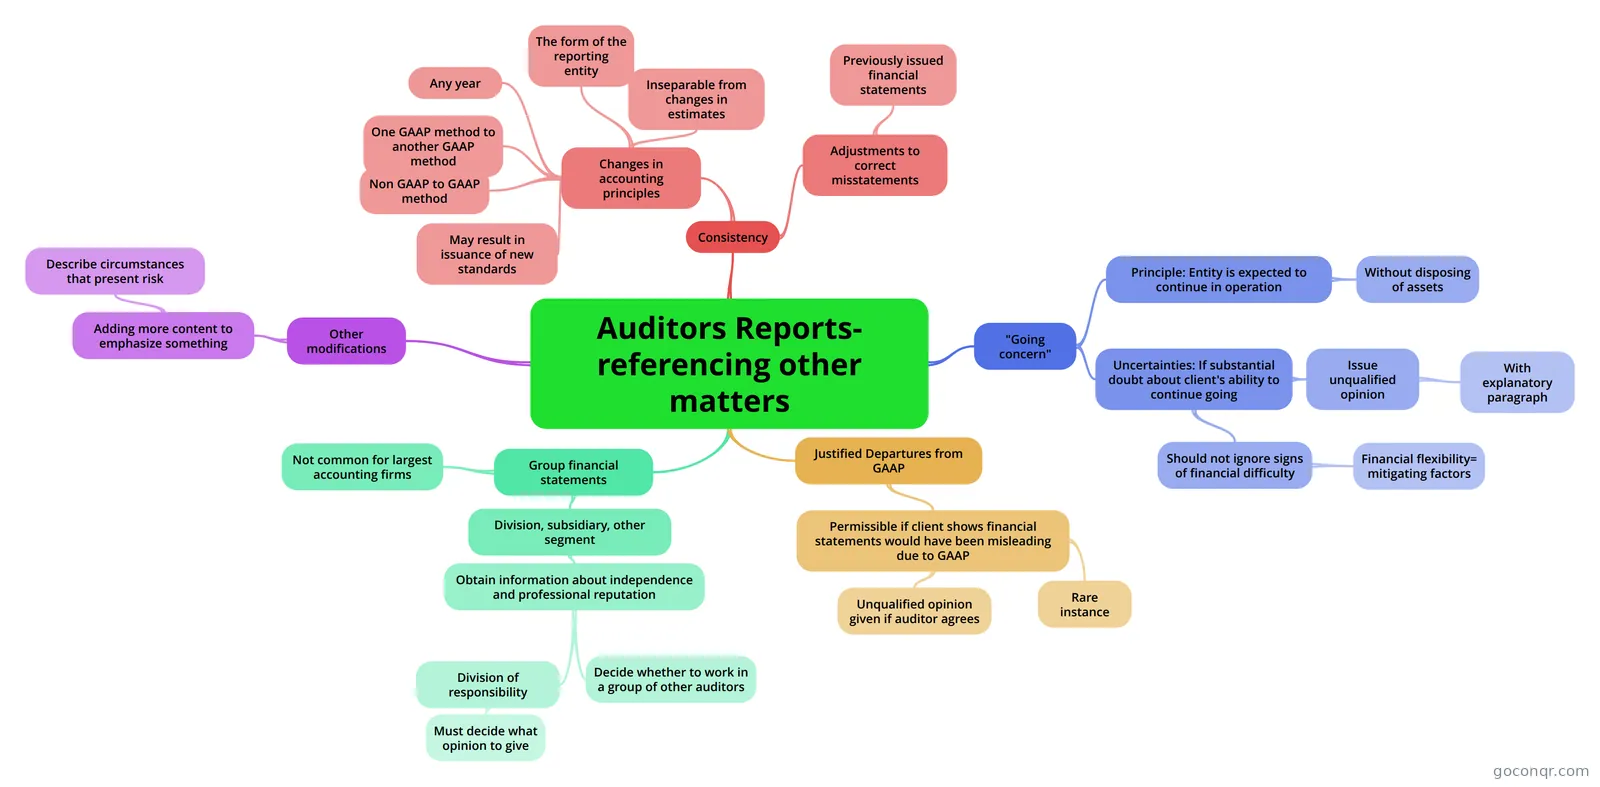
Mind map: auditors reports referencing other matters
Inhalt der Mindmap
Auditors Reports- referencing other matters
Consistency
- Changes in accounting principles
- Any year
- One GAAP method to another GAAP method
- The form of the reporting entity
- Non GAAP to GAAP method
- Inseparable from changes in estimates
- May result in issuance of new standards
- Adjustments to correct misstatements
- Previously issued financial statements
- Changes in accounting principles
"Going concern"
- Principle: Entity is expected to continue in operation
- Without disposing of assets
- Uncertainties: If substantial doubt about client's ability to continue going
- Issue unqualified opinion
- With explanatory paragraph
- Should not ignore signs of financial difficulty
- Financial flexibility= mitigating factors
- Issue unqualified opinion
- Principle: Entity is expected to continue in operation
Justified Departures from GAAP
- Permissible if client shows financial statements would have been misleading due to GAAP
- Rare instance
- Unqualified opinion given if auditor agrees
- Permissible if client shows financial statements would have been misleading due to GAAP
Group financial statements
- Division, subsidiary, other segment
- Obtain information about independence and professional reputation
- Decide whether to work in a group of other auditors
- Division of responsibility
- Must decide what opinion to give
- Obtain information about independence and professional reputation
- Not common for largest accounting firms
- Division, subsidiary, other segment
Other modifications
- Adding more content to emphasize something
- Describe circumstances that present risk
- Adding more content to emphasize something
Informationen
- Beschreibung
- Mindmap am Auditors Reports- referencing other matters, erstellt von emmiller10 am 23/04/2013.
- Erstellt von
- emmiller10
- Aufrufe
- 42
- Bewertung