
Karteikarten
Financial Statements Flashcards
Karten in diesem Stapel (26)
- 1RelevanceFinancial Information is said to be relevant if :
- It has the ability to influence the economic decisions of the users
- It is provided in time to influence those decisions - 2ReliabilityValuations (such as depreciation or inventory) must be;
- Free from bias
- Free from material errors
- With a degree of caution (prudence) - 3ComparabilityInformation is much more useful if it is comparable over time and also with similar information about other businesses.
- 4Ease of UnderstandingUsers should be able to understand with a reasonable knowledge of accounting and have a willingness to study the information diligently.
- 5MaterialityMateriality defines the threshold or cut-off point after which financial information becomes relevant to the decision making needs of the users.
- 6Statement of Profit or Loss (SPL)Summary of Activity in the year
Income
Expenses - 7Statement of Financial Position (SPF)Snapshot of the business on final day of accounting period
Assets
Liabilities
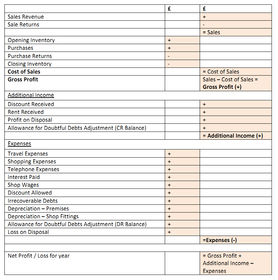
Capital - 8SPL - Example
- 9SFP - Example
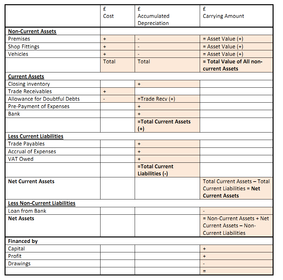
- 10SFP Non-Current AssetsPremises
Shop Fittings
Vehicles - 11SFP Current AssetsClosing Inventory
Trade Receivables (minus Allowance DD)
Pre-Payment of Expenses
Bank - 12SFP Current LiabilitiesTrade Payables
Accrual of Expenses
VAT Owed - 13SFP Non-Current LiabilitiesLoan from Bank
Mortgage - 14SFP Financed ByCapital + Profit - Drawings
(Should match Net Assets) - 15SFP Net AssetsNon-Current Assets + Net Current Assets - Non-Currnet Liabilities =
NET ASSETS - 16SPL Gross ProfitSales Revenue
- Sales Returns
=SALES
+Opening Inventory
+Purchases
-Purchases Returns
-Closing Inventory
=COST OF SALES
SALES - COST OF SALES
= GROSS PROFIT - 17SPL Additional IncomeDiscount Received
Rent Received
Profit on Disposal
Allowance for DD Adjustment (CR) - 18SPL ExpensesGeneral Expenses
Interest Paid
Wages
Discount Allowed
Irrecoverable Debts
Depreciation
Allowance DD Adjustment (DR)
Loss on Disposal - 19SPL OverviewGross Profit + Additional Income – Expenses
= Net Profit / Loss - 20AccrualsSFP
Current Liability - 21Allowance For Doubt DebtsSFP
(Removed from SLCA - Trade Receivables) - 22Accumulated DepreciationSFP
Removed from Assets in the Accumulated Depreciation Column - 23Pre-PaymentsSFP
Current Asset - 24Allowance for Doubtful Debts AdjustmentsSPL
Expenses - 25Opening InventorySPL
- 26SLCA Sales Ledger Control AccountSFP
Trade Receivables - Remove Allowance for Doubtful Debts before posting to the SFP
Informationen
- Beschreibung
- Level 3 AAT AAT Level 3 (Sole Traders and Partnerships ) Karteikarten am Financial Statements Flashcards, erstellt von claire.harrison am 24/02/2015.
- Erstellt von
- claire.harrison
- Aufrufe
- 207
- Tags
- Bewertung