
Karteikarten
Pensions and Income Tax accounting
Karten in diesem Stapel (23)
- 1Defined benefit planbenefits employees receive at retirement are determined by a formula
- 2Defined contribution plancontributions that sponsor company receives, determined by a formula (simple)
- 3Accumulated Benefit Obligation (ABO)PV of future retirement payments, uses current/past salary levels
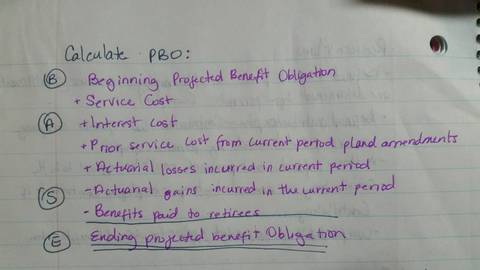
- 4Projected Benefit Obligation (PBO)on BS, assumes future compensation levels
- 5Vestedemployee has earned benefits
- 6Service CostPV of all pension benefits earned by co. employees in current yr
- 7Interest Costincrease in PBO due to changes in actuarial assumption
- 8benefit paymentspayments to plan participants after retirement
- 9Projected Benefit obligation (PBO) formula
- 10Plan Assetsstocks, bonds, other investments set aside to provide for pension benefits
- 11Actual return on plan assetsreturn on plan assets - returns on assets held by pension plan
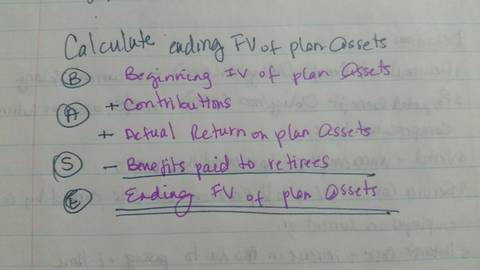
- 12Ending FV of Plan Assets Formula
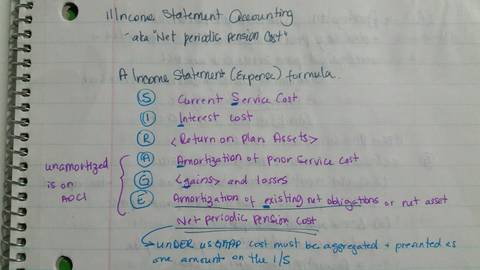
- 13Net Periodic Benefits
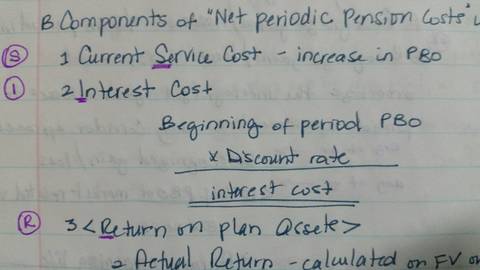
- 14Interest Cost Formula
- 15expected return on plan assets formula
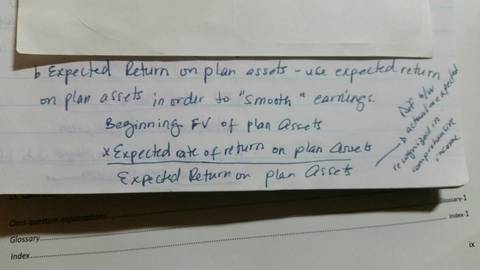
- 16amortization of unrecognized prior service cost formula
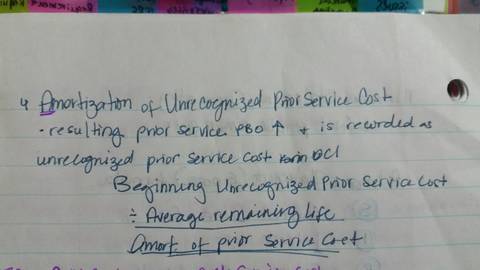
- 17Changes in Actuarial assumptions
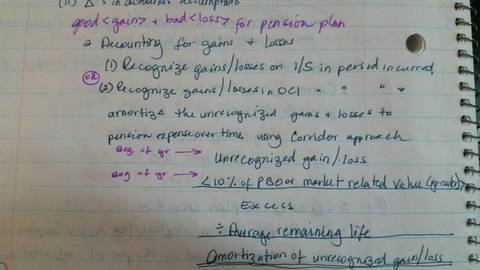
- 18amortization of existing net obligation/asset at implementation(rare)
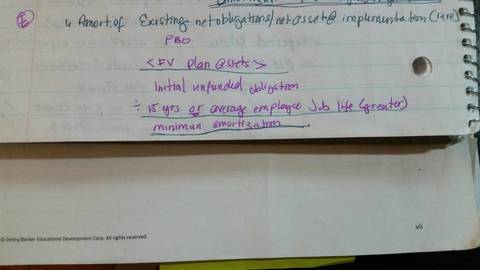
- 19pension plan contributions
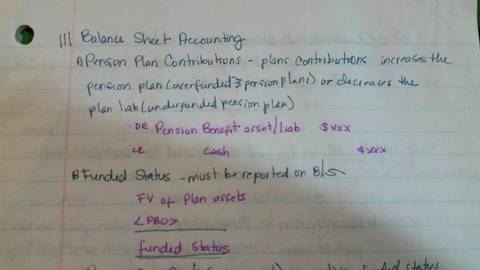
- 20Net pension gainunder GAAP, its the difference between expected return on plan assets and actual return on plan assets
- 21Funded StatusFV plan assets - PBO = Funded Status
pension plan with a positive funded status will always report a noncurrent asset - 22Effective Tax RateEffective tax rate = Income tax expense / Pretax income
- 23Attribution Periodperiod of an employee's service to which the expected postretirement benefit obligation for that employee is assigned
Informationen
- Beschreibung
- Karteikarten am Pensions and Income Tax accounting, erstellt von Eylin Nunez am 27/06/2015.
- Erstellt von
- Eylin Nunez
- Aufrufe
- 35
- Tags
- Bewertung