
Fichas
cima. F1
Fichas del conjunto (54)
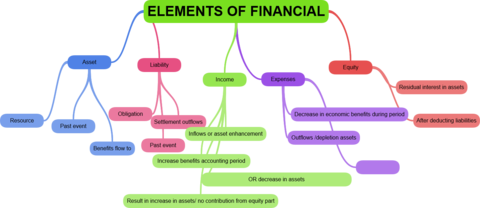
- 1ASSETAn asset is a resource controlled by the enterprise as a result of a past event and from which future economic benefits are expected to flow to the enterprise
- 2LIABILITYA liability is a present obligation arising from past events, the settlement of which is expected to result in an outflow of resources from the enterprise
- 3EQUITYEquity is the residual interest in the assets of the enterprise after deducting all its liabilities
- 4INCOMEIncome is increases in economic benefits during the accounting period in the form of inflows or enhancements of assets or decreases of liabilities that result in increases in equity, other than those relating to contributions from equity participants
- 5EXPENSESExpenses are decreases in economic benefits during the accounting period in the form of outflows or depletions of assets or incurrence's of liabilities that result in decreases in equity, other than those relating to distributions to equity participants.
- 6cima code of ethicsICOPP
- 7INTEGRITYStraightforward
Honest
In all professional &business relationships - 8ObjectivityNot allow
Bias
Conflict of interest
Undue influence to override judgements - 9PROFESSIONAL COMPETENCE AND DUE CAREMaintain professional knowledge & skills
Client to receive competent professional services - 10ConfidentialityConfidentiality of information
Do not disclose unless without authority or legal duty
No use of info for personal gain - 11Professional BehaviourComply with relevant laws and regulations
Avoid action that discredit profession - 12Purpose of IFRS framework1) Review existing IAS's IFRS's and develop NEW IFRS's
2) harmonize existing accounting standards.
3)Assist national accounting setting boards
4) assist preparers in applying IFRS's
5) assist auditors do statements comply with IFRS - 13IFRS ADVISORY COUNCILForum for groups to give opinions
Advises on practical application and implementation of NEW IFRS
*composed of wide geograph and jobs - 14IFRIC INTERNATIONAL FINANCIAL REPORTING INTERPRETATIONS COMMITTEEGUIDANCE APPLICATION&interpretation
Complex accounting issues
Setting and improving IFRS
Produces interpretations that ratified and issued by IASB - 15Complete set of financial statements include1. Statement of financial position (bal sheet)
2. Statement of profit and loss and other comprehensive income
3. St tempest of changes in equity
4. Statement of cash flows
5. Management notes - 16PURPOSE OF FINANCIAL STATEMENTSIAS 1 (revised) states that the objective of financial statements is to provide information about the financial position, performance and cash flows of an enterprise that is useful in making economic decisions
- 17A COMPLETE SET OF FINANCIAL STATEMENTS INCLUDES• a statement of financial position;
• either:
– a statement of comprehensive income, or
– an income statement plus a statement showing other comprehensive income;
• a statement of changes in equity;
• a statement of cash flows;
• accounting policies note and other explanatory notes - 18ELEMENTS OF FINANCIAL STATEMENTS
- 19INTANGIBL ASSETIDENTIFIABLE
NON MONETARY
WITHOUT PHYSICAL SUBSTANCE
CONTROLLED/FEB FLOW - 20IMPAIRMENTRECOVERABLE AMT
LESS THAN BOOK VALUE - 21RECOVERABLE AMOUNTHIGHER OF THE FAIR VALUE LSS COSTS TO SELL
OR
VALUE IN USE - 22CARRYING AMOUNT OF ASSETTHE AMOUNT RECOGNISED IN THE FINANCIAL STATEMENTS
- 23IMPAIRMENT LOSSAMOUNT
- 24SUM OF THE DIGITSN x (N+1) / 2
USE TO APPLY AMOUNT OF INTEREST TO EACH YEAR
LAST PAYMETN IS 1 - 25ACTURARIAL METHOD FOR FINANCE LEASEUSE IF INTEREST RATE ISPROVIDED
Beg Balance = Initial recognition amount
Paid= Amount of the lease payment
Subtotal = Beg Bal less lease payment
Interest = Int % times Subtotal
Closing Balance= Subtotal plus Interest - 264 Qualities IASB. FRAMEWORKRRCU
1. Relevance
2. Reliability
3. Comparability
4. Understandability - 27RELEVANCE (one of IASB Framework Qualities)Influences economic decisions of users
helps to evaluate past present or future events
confirming and predictive role - 28RELIABILITY ( one of the IASB Framework qualitative principles)Free from MATERIAL ERRROR & BIAS
INFORMATION CAN BE DEPENDED UPON - 29COMPARABILITY ( one of the IASB Framework Qualitative Principles)Helps users COMPARE DATA OVER TIME
Compare statements of Different Companies
Fin Stms must show prior period numbers
Accounting Policies must be knoown - 30UNDERSTANDABILITY ( one of the IASB Framework's QualitativePrinciples)Assume readers have reasonable knowledge of
BUSINESS
ECONOMIC ACTIVITIES
ACCOUNTING
Able to study info with reasonable diligence - 31UNDERSTANDABILITY ( one of the IASB Framework's QualitativePrinciples)Assume readers have reasonable knowledge of
BUSINESS
ECONOMIC ACTIVITIES
ACCOUNTING
Able to study info with reasonable diligence - 323 THINGS TAX EXPENSE CONSISTS OFlCURRENT YEARS TAX CHG
DEFERRED TAX MOVEMENT
UNDER/OVER PROVISION - 33CONSTRUCTIONS WORKINGS1) Overall Profit
2) % of Completion
3)Income Statement Extract
4) SOFP ( from and to customer) - 34Constructions Working Amount due to/From CustomerTotal Costs
+ Profit Realised
Less Amount Billed - 353 tax basesincome - Corp or Personal
Asset- Capital Gains
Consumption - Sales Tax - 36Adam Smith Taxes Should be:FACE
Fair
Absolute
Convenient
Efficient - 373 Major PrinciplesEEE
Equitable
Efficient
Economic Benefit - 38Types of Taxes: UNITBased on the number of items or weight
Example: EXISE DUTIES - 39Types of Taxes: Ad VolorenBased on Value
Sales Tax - 40Multi Stage TaxesCascade- Everyone Pays ( no refunds)
VAT - Charged at all stages - refunds so only the end consumer pays - 41VAT OUTPUTTax charged to the customer on the products that the company is putting OUT
- 42VAT INPUTTAX paid on purchases that the company is inputting into their comapny
- 43exempt vatno tax in or out
- 44ZERO RATED VATNot paid for by consumer - company can claim back
- 45trading loss solutions1)Carry loss foward
)Carry loss Backwards
3)Off set loss against other income/cap gains
4)Offset against porfits of other group company - 46LEASE - JOURNAL ENTRIES (4)1) Record Asset & Liability
2) Record Depreciation
3) Allocate and Record Finance Charge
4) Record Lease Payment - 47SHARE ISSUE COSTSDeduct first from Share Premium Account then from retained earnings
- 48The objective of general purpose financial reportingThe objective of general purpose financial reporting is
• to provide financial information
• about the reporting entity
• that is useful to existing and potential investors, lenders and other creditors
• in making decisions about providing resources to the entity.’ - 492 categories of qualitivative infomration The qualitative characteristics of useful financial information identify the types of information that are likely to be most useful to existing and potential investors, lenders and other creditors for making decisions about the reporting entity on the basis of information in its financial report (financial information).3.6 The qualitative characteristics of useful financial information identify the types of information that are likely to be
most useful to existing and potential investors, lenders and other creditors for making decisions about the
reporting entity on the basis of information in its financial report (financial information).
They are categorised into two categories:
• Fundamental qualitative characteristics
• Enhancing qualitative characteristics. - 50PROFITDIFFERENCE BETWEEN COMPANYS BEGINNING CAPITAL AND ENDING CAPITAL
- 51TO RECOGNIZE AN ELEMENTS IT MUST (3 THINGS)*Definition- Meet the definiton of an element
* Reliably MeasuredCost or Revenue must be reliably
measured
*Future Economic benefit will flow. - 52Fundamental QUALITATIVE characteristics (2)Relevant: Capable of making difference in decisions ( Material)
Faithful Representation: Complete, Free From Bias and Error - 53ENHANCING QUALITATIVE Characteristics (4)C U T V
Comparable- time Periods/ Other Companies
Understandable- clear, concise
Timeliness-
Verifiable- verification can be direct or indirect - 54CAPITAL 2 TYPES1) FINANCING CAPITAL - Fund attributable to shareholder - wealth of Shareholders
2) OPERATING CAPITAL- Physical operating capital- support business operation.
Información
- Descripción
- CIMA CIMA F1 PAPER Fichas sobre cima. F1, creado por beth auerbach el 18/09/2013.
- Creado por
- beth auerbach
- Visitas
- 435
- Etiquetas
- Valoración