
Mapa mental
Issues with WACC and capital structure policy
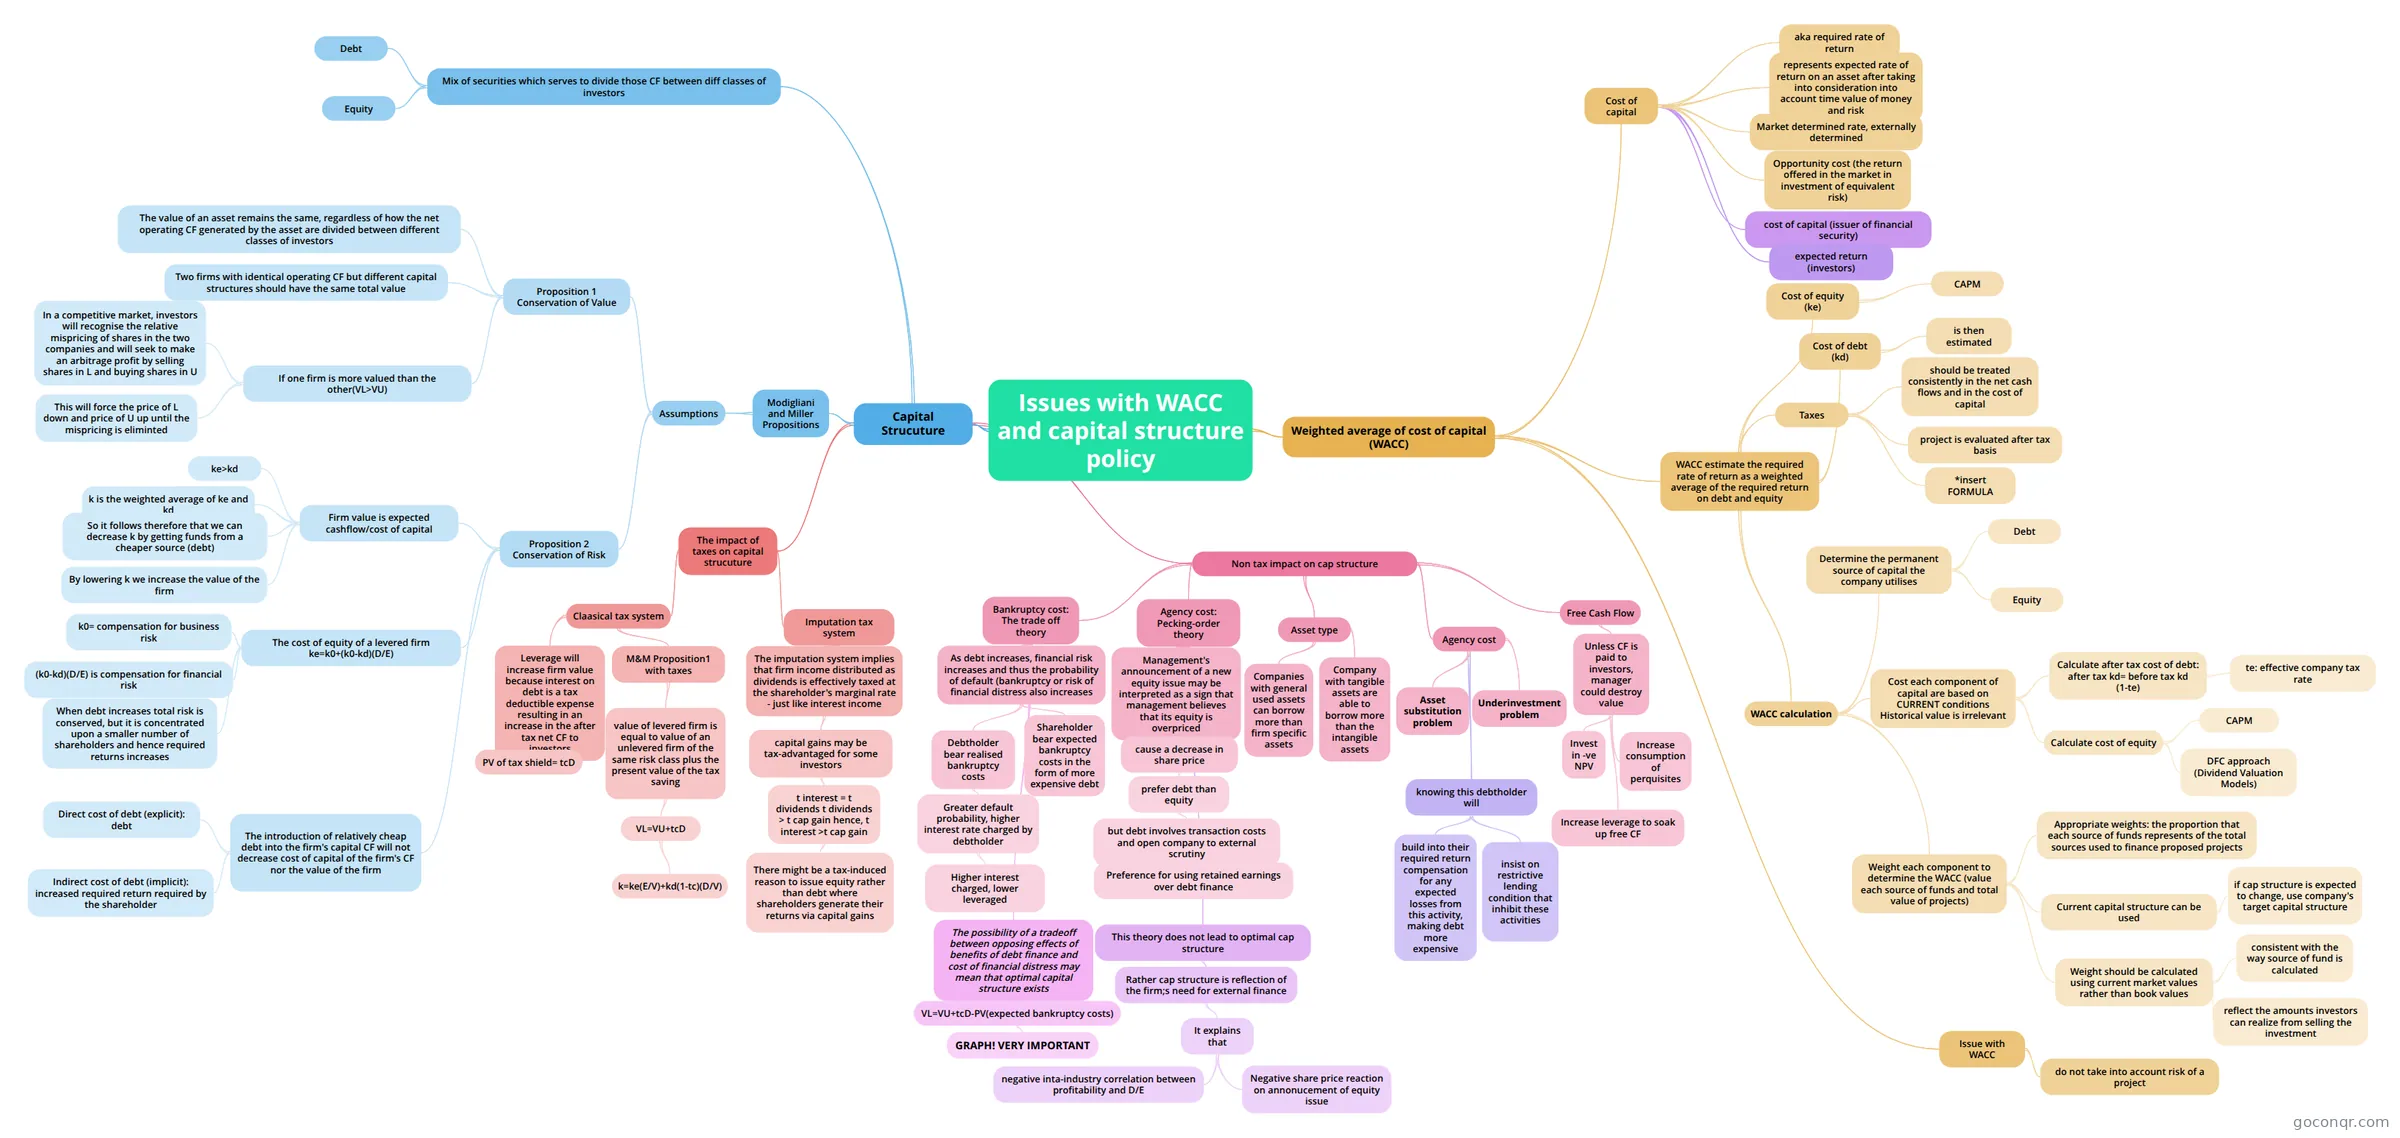
Mind map: Issues with WACC and capital structure policy
Contenido del mapa
Issues with WACC and capital structure policy
Weighted average of cost of capital (WACC)
- Cost of capital
- aka required rate of return
- represents expected rate of return on an asset after taking into consideration into account time value of money and risk
- Market determined rate, externally determined
- Opportunity cost (the return offered in the market in investment of equivalent risk)
- cost of capital (issuer of financial security)
- expected return (investors)
- WACC estimate the required rate of return as a weighted average of the required return on debt and equity
- Cost of equity (ke)
- CAPM
- Cost of debt (kd)
- is then estimated
- Taxes
- should be treated consistently in the net cash flows and in the cost of capital
- project is evaluated after tax basis
- *insert FORMULA
- WACC calculation
- Determine the permanent source of capital the company utilises
- Debt
- - Bank overdraft - Money market loans - Commercial bills - Promissory notes - Bonds - Debentures - Unsecured notes - Mortgage loans - Finance leases - Term loans
- Equity
- - Ordinary shares - Preference shares - Retained earnings
- Debt
- Cost each component of capital are based on CURRENT conditions Historical value is irrelevant
- Calculate after tax cost of debt: after tax kd= before tax kd (1-te)
- te: effective company tax rate
- Calculate cost of equity
- CAPM
- DFC approach (Dividend Valuation Models)
- Calculate after tax cost of debt: after tax kd= before tax kd (1-te)
- Weight each component to determine the WACC (value each source of funds and total value of projects)
- Appropriate weights: the proportion that each source of funds represents of the total sources used to finance proposed projects
- Current capital structure can be used
- if cap structure is expected to change, use company's target capital structure
- Weight should be calculated using current market values rather than book values
- consistent with the way source of fund is calculated
- reflect the amounts investors can realize from selling the investment
- Determine the permanent source of capital the company utilises
- Cost of equity (ke)
- Issue with WACC
- do not take into account risk of a project
- Cost of capital
Capital Strucuture
- Mix of securities which serves to divide those CF between diff classes of investors
- Debt
- Equity
- Modigliani and Miller Propositions
- Assumptions
- 1. Capital markets are perfect 2. Companies and individual can borrow at the same interest rate 3. There are no taxes 4. There are no cost associated woth the liquidation of a company 5. Companies have fixed investment policy so that investment decisions are not affected by financing decisions
- Proposition 1 Conservation of Value
- The value of an asset remains the same, regardless of how the net operating CF generated by the asset are divided between different classes of investors
- Two firms with identical operating CF but different capital structures should have the same total value
- If one firm is more valued than the other(VL>VU)
- In a competitive market, investors will recognise the relative mispricing of shares in the two companies and will seek to make an arbitrage profit by selling shares in L and buying shares in U
- This will force the price of L down and price of U up until the mispricing is eliminted
- Proposition 2 Conservation of Risk
- Firm value is expected cashflow/cost of capital
- ke>kd
- k is the weighted average of ke and kd
- So it follows therefore that we can decrease k by getting funds from a cheaper source (debt)
- By lowering k we increase the value of the firm
- The cost of equity of a levered firm ke=k0+(k0-kd)(D/E)
- k0= compensation for business risk
- (k0-kd)(D/E) is compensation for financial risk
- When debt increases total risk is conserved, but it is concentrated upon a smaller number of shareholders and hence required returns increases
- The introduction of relatively cheap debt into the firm's capital CF will not decrease cost of capital of the firm's CF nor the value of the firm
- Direct cost of debt (explicit): debt
- Indirect cost of debt (implicit): increased required return required by the shareholder
- Firm value is expected cashflow/cost of capital
- Assumptions
- The impact of taxes on capital strucuture
- Claasical tax system
- Leverage will increase firm value because interest on debt is a tax deductible expense resulting in an increase in the after tax net CF to investors
- PV of tax shield= tcD
- M&M Proposition1 with taxes
- value of levered firm is equal to value of an unlevered firm of the same risk class plus the present value of the tax saving
- VL=VU+tcD
- k=ke(E/V)+kd(1-tc)(D/V)
- VL=VU+tcD
- value of levered firm is equal to value of an unlevered firm of the same risk class plus the present value of the tax saving
- Leverage will increase firm value because interest on debt is a tax deductible expense resulting in an increase in the after tax net CF to investors
- Imputation tax system
- The imputation system implies that firm income distributed as dividends is effectively taxed at the shareholder's marginal rate - just like interest income
- capital gains may be tax-advantaged for some investors
- t interest = t dividends t dividends > t cap gain hence, t interest >t cap gain
- There might be a tax-induced reason to issue equity rather than debt where shareholders generate their returns via capital gains
- t interest = t dividends t dividends > t cap gain hence, t interest >t cap gain
- capital gains may be tax-advantaged for some investors
- The imputation system implies that firm income distributed as dividends is effectively taxed at the shareholder's marginal rate - just like interest income
- Claasical tax system
- Non tax impact on cap structure
- Bankruptcy cost: The trade off theory
- As debt increases, financial risk increases and thus the probability of default (bankruptcy or risk of financial distress also increases
- Debtholder bear realised bankruptcy costs
- Greater default probability, higher interest rate charged by debtholder
- Higher interest charged, lower leveraged
- Greater default probability, higher interest rate charged by debtholder
- Shareholder bear expected bankruptcy costs in the form of more expensive debt
- Debtholder bear realised bankruptcy costs
- The possibility of a tradeoff between opposing effects of benefits of debt finance and cost of financial distress may mean that optimal capital structure exists
- VL=VU+tcD-PV(expected bankruptcy costs)
- GRAPH! VERY IMPORTANT
- VL=VU+tcD-PV(expected bankruptcy costs)
- As debt increases, financial risk increases and thus the probability of default (bankruptcy or risk of financial distress also increases
- Agency cost: Pecking-order theory
- Management's announcement of a new equity issue may be interpreted as a sign that management believes that its equity is overpriced
- cause a decrease in share price
- prefer debt than equity
- but debt involves transaction costs and open company to external scrutiny
- Preference for using retained earnings over debt finance
- but debt involves transaction costs and open company to external scrutiny
- prefer debt than equity
- cause a decrease in share price
- This theory does not lead to optimal cap structure
- Rather cap structure is reflection of the firm;s need for external finance
- It explains that
- negative inta-industry correlation between profitability and D/E
- Negative share price reaction on annonucement of equity issue
- It explains that
- Rather cap structure is reflection of the firm;s need for external finance
- Management's announcement of a new equity issue may be interpreted as a sign that management believes that its equity is overpriced
- Asset type
- Companies with general used assets can borrow more than firm specific assets
- Company with tangible assets are able to borrow more than the intangible assets
- Free Cash Flow
- Unless CF is paid to investors, manager could destroy value
- Invest in -ve NPV
- Increase consumption of perquisites
- Increase leverage to soak up free CF
- Unless CF is paid to investors, manager could destroy value
- Agency cost
- Asset substitution problem
- Shareholder in a company with outstanding debt own a call option on the assets of the company Call option values increase with increasing volatility
- A company with outstanding debt may have an incentives to take higher risk projects, even the project may reduce overall market value of the firm
- Underinvestment problem
- Firm close to bankruptcy may pass up +ve NPV projects because nobody will be willing to finance them
- Existing s/h will not contribute equity as first gains from investing in +ve NPV projects accrue to debtholders New s/h will not buy equity at existing prices but require a substantial discount -Existing s/h will reject as their interest is diluted
- knowing this debtholder will
- build into their required return compensation for any expected losses from this activity, making debt more expensive
- insist on restrictive lending condition that inhibit these activities
- Asset substitution problem
- Bankruptcy cost: The trade off theory
- Mix of securities which serves to divide those CF between diff classes of investors