
Mapa mental
State of modern macro
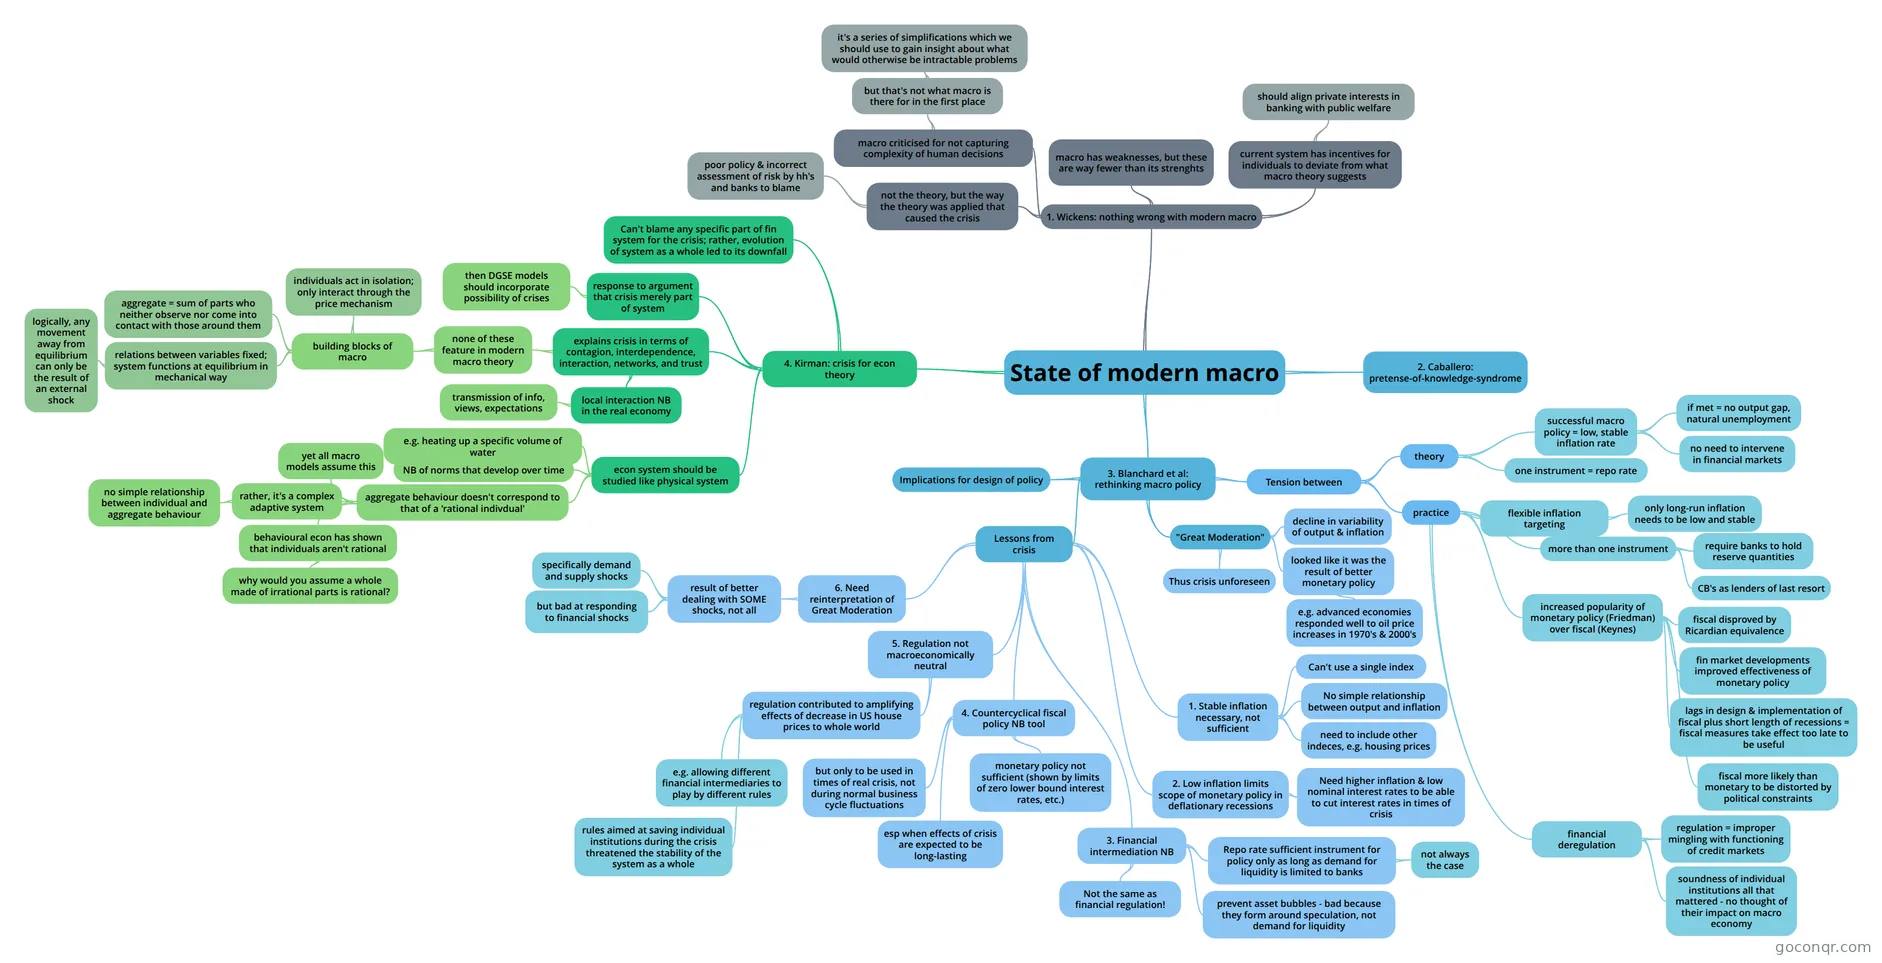
Mind map: State of modern macro
Contenido del mapa
State of modern macro
1. Wickens: nothing wrong with modern macro
- not the theory, but the way the theory was applied that caused the crisis
- poor policy & incorrect assessment of risk by hh's and banks to blame
- macro criticised for not capturing complexity of human decisions
- but that's not what macro is there for in the first place
- it's a series of simplifications which we should use to gain insight about what would otherwise be intractable problems
- but that's not what macro is there for in the first place
- macro has weaknesses, but these are way fewer than its strenghts
- current system has incentives for individuals to deviate from what macro theory suggests
- should align private interests in banking with public welfare
- not the theory, but the way the theory was applied that caused the crisis
2. Caballero: pretense-of-knowledge-syndrome
3. Blanchard et al: rethinking macro policy
- Tension between
- theory
- successful macro policy = low, stable inflation rate
- if met = no output gap, natural unemployment
- no need to intervene in financial markets
- one instrument = repo rate
- successful macro policy = low, stable inflation rate
- practice
- flexible inflation targeting
- only long-run inflation needs to be low and stable
- more than one instrument
- require banks to hold reserve quantities
- CB's as lenders of last resort
- increased popularity of monetary policy (Friedman) over fiscal (Keynes)
- fiscal disproved by Ricardian equivalence
- fin market developments improved effectiveness of monetary policy
- lags in design & implementation of fiscal plus short length of recessions = fiscal measures take effect too late to be useful
- fiscal more likely than monetary to be distorted by political constraints
- financial deregulation
- regulation = improper mingling with functioning of credit markets
- soundness of individual institutions all that mattered - no thought of their impact on macro economy
- flexible inflation targeting
- theory
- "Great Moderation"
- decline in variability of output & inflation
- looked like it was the result of better monetary policy
- e.g. advanced economies responded well to oil price increases in 1970's & 2000's
- Thus crisis unforeseen
- Lessons from crisis
- 1. Stable inflation necessary, not sufficient
- Can't use a single index
- No simple relationship between output and inflation
- need to include other indeces, e.g. housing prices
- 2. Low inflation limits scope of monetary policy in deflationary recessions
- Need higher inflation & low nominal interest rates to be able to cut interest rates in times of crisis
- 3. Financial intermediation NB
- Repo rate sufficient instrument for policy only as long as demand for liquidity is limited to banks
- not always the case
- prevent asset bubbles - bad because they form around speculation, not demand for liquidity
- Not the same as financial regulation!
- Repo rate sufficient instrument for policy only as long as demand for liquidity is limited to banks
- 4. Countercyclical fiscal policy NB tool
- monetary policy not sufficient (shown by limits of zero lower bound interest rates, etc.)
- esp when effects of crisis are expected to be long-lasting
- but only to be used in times of real crisis, not during normal business cycle fluctuations
- 5. Regulation not macroeconomically neutral
- regulation contributed to amplifying effects of decrease in US house prices to whole world
- e.g. allowing different financial intermediaries to play by different rules
- rules aimed at saving individual institutions during the crisis threatened the stability of the system as a whole
- regulation contributed to amplifying effects of decrease in US house prices to whole world
- 6. Need reinterpretation of Great Moderation
- result of better dealing with SOME shocks, not all
- specifically demand and supply shocks
- but bad at responding to financial shocks
- result of better dealing with SOME shocks, not all
- 1. Stable inflation necessary, not sufficient
- Implications for design of policy
- Tension between
4. Kirman: crisis for econ theory
- Can't blame any specific part of fin system for the crisis; rather, evolution of system as a whole led to its downfall
- response to argument that crisis merely part of system
- then DGSE models should incorporate possibility of crises
- explains crisis in terms of contagion, interdependence, interaction, networks, and trust
- none of these feature in modern macro theory
- building blocks of macro
- individuals act in isolation; only interact through the price mechanism
- aggregate = sum of parts who neither observe nor come into contact with those around them
- relations between variables fixed; system functions at equilibrium in mechanical way
- logically, any movement away from equilibrium can only be the result of an external shock
- building blocks of macro
- local interaction NB in the real economy
- transmission of info, views, expectations
- none of these feature in modern macro theory
- econ system should be studied like physical system
- e.g. heating up a specific volume of water
- NB of norms that develop over time
- aggregate behaviour doesn't correspond to that of a 'rational indivdual'
- rather, it's a complex adaptive system
- no simple relationship between individual and aggregate behaviour
- yet all macro models assume this
- behavioural econ has shown that individuals aren't rational
- why would you assume a whole made of irrational parts is rational?
- rather, it's a complex adaptive system
Información
- Descripción
- Mindmap of different views of the state of modern macro, including Eichengreen, Cabellero etc.
- Creado por
- Heleen Hofmeyr
- Visitas
- 61
- Etiquetas
- Valoración