
Mapa mental
Standard costing
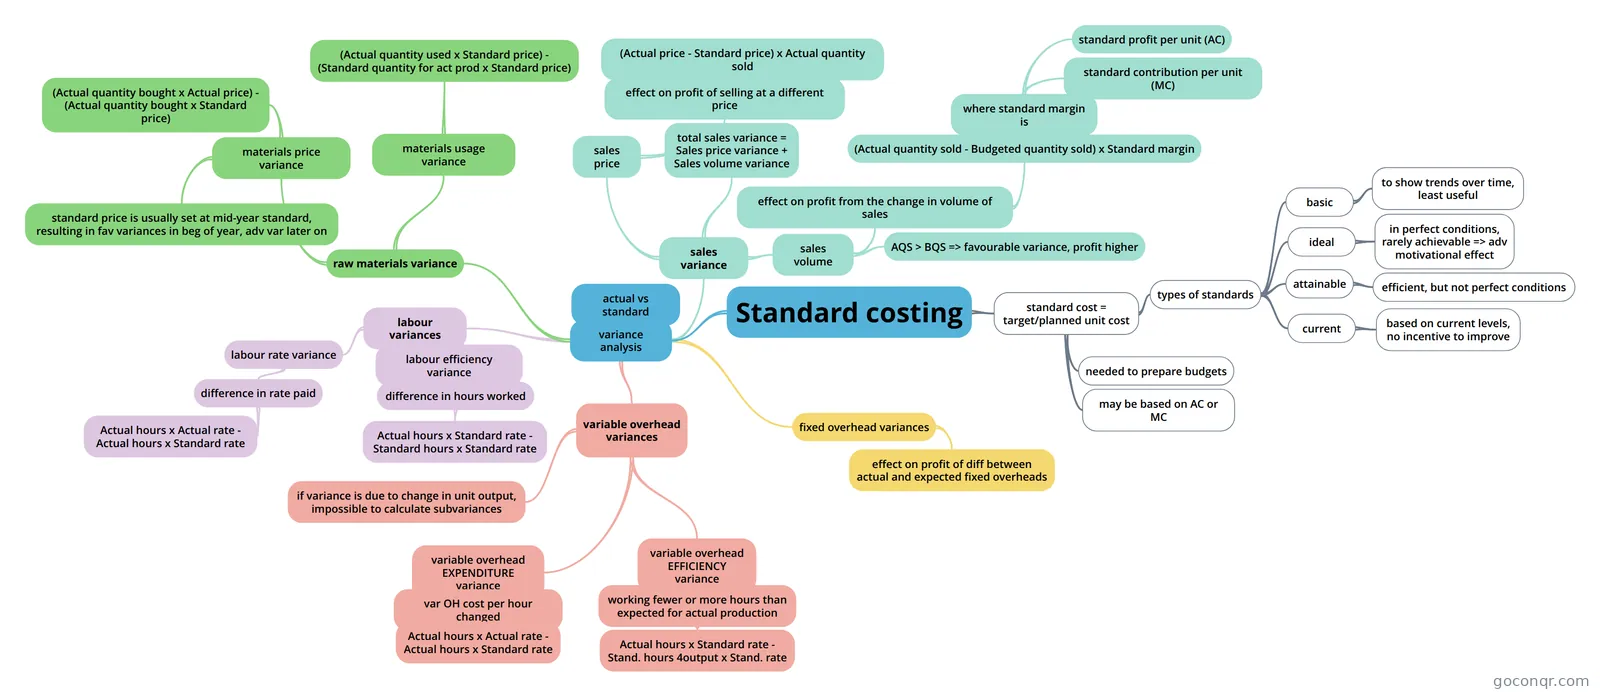
Mind map: standard costing
Contenido del mapa
Standard costing
standard cost = target/planned unit cost
- types of standards
- basic
- to show trends over time, least useful
- ideal
- in perfect conditions, rarely achievable => adv motivational effect
- attainable
- efficient, but not perfect conditions
- current
- based on current levels, no incentive to improve
- basic
- needed to prepare budgets
- may be based on AC or MC
- types of standards
variance analysis
- actual vs standard
- sales variance
- sales price
- effect on profit of selling at a different price
- (Actual price - Standard price) x Actual quantity sold
- effect on profit of selling at a different price
- sales volume
- effect on profit from the change in volume of sales
- (Actual quantity sold - Budgeted quantity sold) x Standard margin
- where standard margin is
- standard profit per unit (AC)
- standard contribution per unit (MC)
- where standard margin is
- (Actual quantity sold - Budgeted quantity sold) x Standard margin
- AQS > BQS => favourable variance, profit higher
- effect on profit from the change in volume of sales
- total sales variance = Sales price variance + Sales volume variance
- sales price
- raw materials variance
- materials price variance
- (Actual quantity bought x Actual price) - (Actual quantity bought x Standard price)
- standard price is usually set at mid-year standard, resulting in fav variances in beg of year, adv var later on
- materials usage variance
- (Actual quantity used x Standard price) - (Standard quantity for act prod x Standard price)
- materials price variance
- labour variances
- labour rate variance
- difference in rate paid
- Actual hours x Actual rate - Actual hours x Standard rate
- difference in rate paid
- labour efficiency variance
- difference in hours worked
- Actual hours x Standard rate - Standard hours x Standard rate
- difference in hours worked
- labour rate variance
- variable overhead variances
- variable overhead EXPENDITURE variance
- var OH cost per hour changed
- Actual hours x Actual rate - Actual hours x Standard rate
- var OH cost per hour changed
- variable overhead EFFICIENCY variance
- working fewer or more hours than expected for actual production
- Actual hours x Standard rate - Stand. hours 4output x Stand. rate
- working fewer or more hours than expected for actual production
- if variance is due to change in unit output, impossible to calculate subvariances
- variable overhead EXPENDITURE variance
- fixed overhead variances
- effect on profit of diff between actual and expected fixed overheads
Información
- Descripción
- Mapa Mental sobre Standard costing, creado por Evgeniya Kachan el 08/03/2015.
- Creado por
- Evgeniya Kachan
- Visitas
- 542
- Valoración