
Mapa mental
Cost Accounting
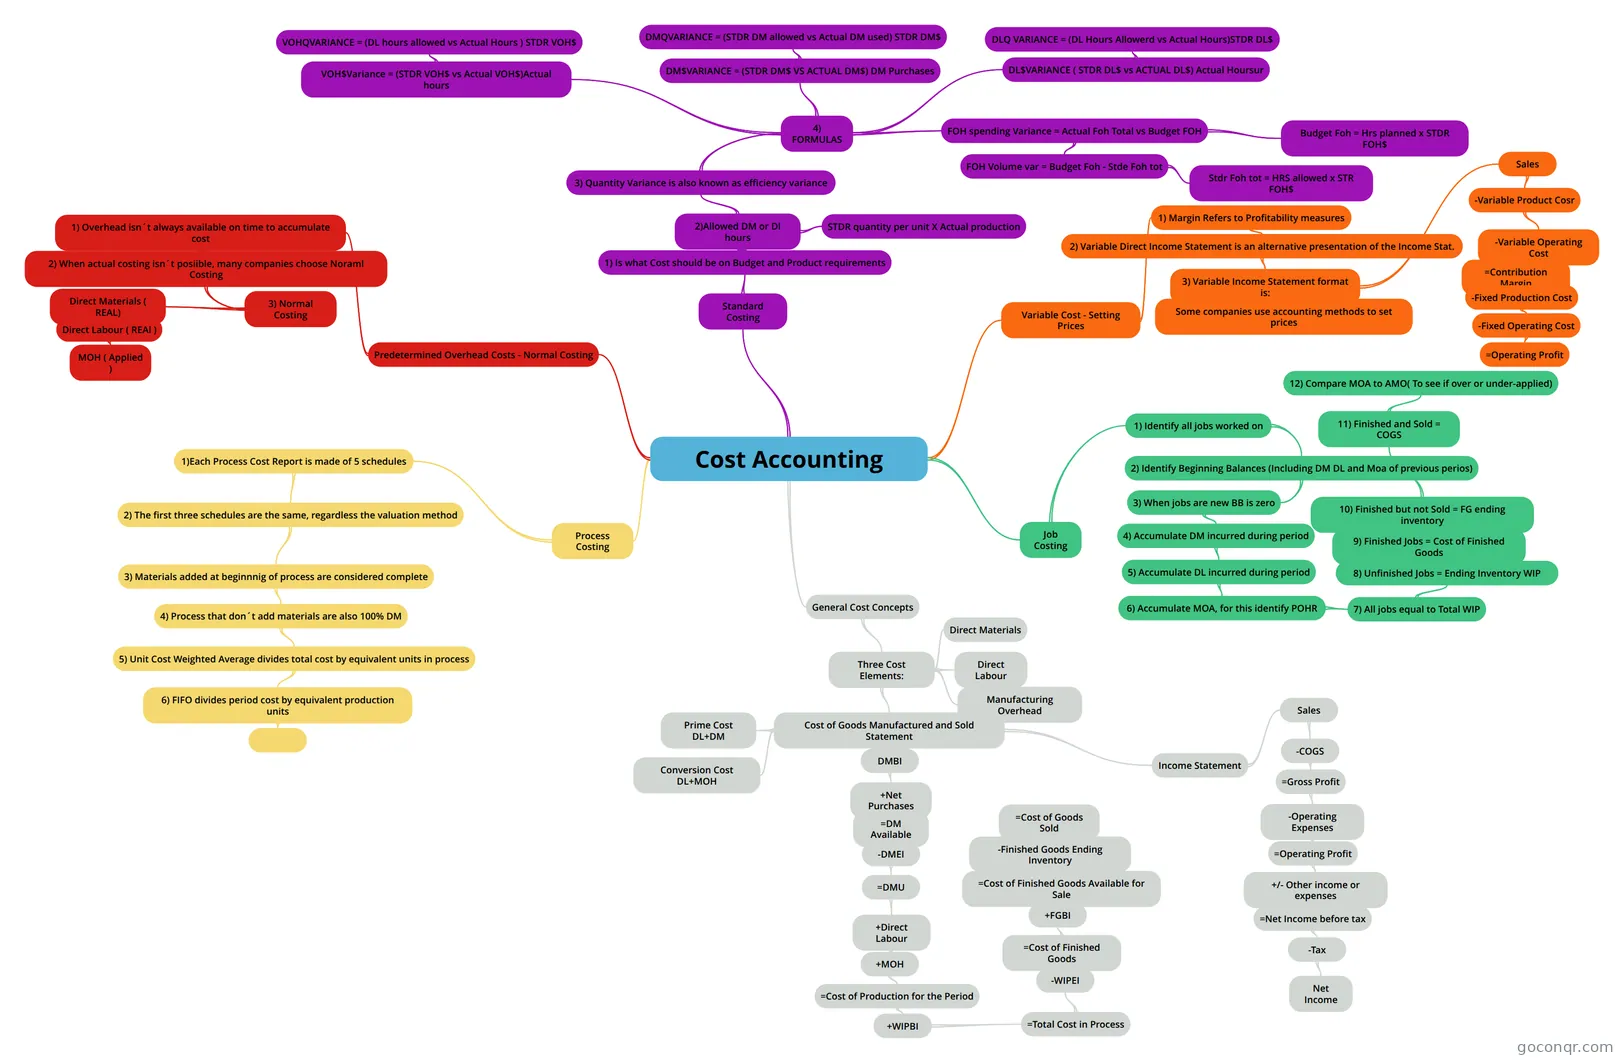
Mind map: Cost Accounting
Contenido del mapa
Cost Accounting
General Cost Concepts
- Three Cost Elements:
- Direct Materials
- Direct Labour
- Manufacturing Overhead
- Cost of Goods Manufactured and Sold Statement
- DMBI
- +Net Purchases
- =DM Available
- -DMEI
- =DMU
- +Direct Labour
- +MOH
- =Cost of Production for the Period
- +WIPBI
- =Total Cost in Process
- -WIPEI
- =Cost of Finished Goods
- +FGBI
- =Cost of Finished Goods Available for Sale
- -Finished Goods Ending Inventory
- =Cost of Goods Sold
- -Finished Goods Ending Inventory
- =Cost of Finished Goods Available for Sale
- +FGBI
- =Cost of Finished Goods
- -WIPEI
- =Total Cost in Process
- +WIPBI
- =Cost of Production for the Period
- +MOH
- +Direct Labour
- =DMU
- -DMEI
- =DM Available
- +Net Purchases
- Income Statement
- Sales
- -COGS
- =Gross Profit
- -Operating Expenses
- =Operating Profit
- +/- Other income or expenses
- =Net Income before tax
- -Tax
- Net Income
- -Tax
- =Net Income before tax
- +/- Other income or expenses
- =Operating Profit
- -Operating Expenses
- =Gross Profit
- -COGS
- Sales
- Prime Cost DL+DM
- Conversion Cost DL+MOH
- DMBI
- Three Cost Elements:
Job Costing
- 1) Identify all jobs worked on
- 2) Identify Beginning Balances (Including DM DL and Moa of previous perios)
- 3) When jobs are new BB is zero
- 4) Accumulate DM incurred during period
- 5) Accumulate DL incurred during period
- 6) Accumulate MOA, for this identify POHR
- 7) All jobs equal to Total WIP
- 8) Unfinished Jobs = Ending Inventory WIP
- 9) Finished Jobs = Cost of Finished Goods
- 10) Finished but not Sold = FG ending inventory
- 11) Finished and Sold = COGS
- 12) Compare MOA to AMO( To see if over or under-applied)
- 11) Finished and Sold = COGS
- 10) Finished but not Sold = FG ending inventory
- 9) Finished Jobs = Cost of Finished Goods
- 8) Unfinished Jobs = Ending Inventory WIP
- 7) All jobs equal to Total WIP
- 6) Accumulate MOA, for this identify POHR
- 5) Accumulate DL incurred during period
- 4) Accumulate DM incurred during period
- 3) When jobs are new BB is zero
- 2) Identify Beginning Balances (Including DM DL and Moa of previous perios)
- 1) Identify all jobs worked on
Standard Costing
- 1) Is what Cost should be on Budget and Product requirements
- 2)Allowed DM or Dl hours
- STDR quantity per unit X Actual production
- 3) Quantity Variance is also known as efficiency variance
- 4) FORMULAS
- DM$VARIANCE = (STDR DM$ VS ACTUAL DM$) DM Purchases
- DMQVARIANCE = (STDR DM allowed vs Actual DM used) STDR DM$
- DL$VARIANCE ( STDR DL$ vs ACTUAL DL$) Actual Hoursur
- DLQ VARIANCE = (DL Hours Allowerd vs Actual Hours)STDR DL$
- VOH$Variance = (STDR VOH$ vs Actual VOH$)Actual hours
- VOHQVARIANCE = (DL hours allowed vs Actual Hours ) STDR VOH$
- FOH spending Variance = Actual Foh Total vs Budget FOH
- Budget Foh = Hrs planned x STDR FOH$
- FOH Volume var = Budget Foh - Stde Foh tot
- Stdr Foh tot = HRS allowed x STR FOH$
- DM$VARIANCE = (STDR DM$ VS ACTUAL DM$) DM Purchases
- 4) FORMULAS
- 2)Allowed DM or Dl hours
- 1) Is what Cost should be on Budget and Product requirements
Predetermined Overhead Costs - Normal Costing
- 1) Overhead isn´t always available on time to accumulate cost
- 2) When actual costing isn´t posiible, many companies choose Noraml Costing
- 3) Normal Costing
- Direct Materials ( REAL)
- Direct Labour ( REAl )
- MOH ( Applied )
- Direct Labour ( REAl )
- Direct Materials ( REAL)
- 3) Normal Costing
- 2) When actual costing isn´t posiible, many companies choose Noraml Costing
- 1) Overhead isn´t always available on time to accumulate cost
Process Costing
- 1)Each Process Cost Report is made of 5 schedules
- 2) The first three schedules are the same, regardless the valuation method
- 3) Materials added at beginnnig of process are considered complete
- 4) Process that don´t add materials are also 100% DM
- 5) Unit Cost Weighted Average divides total cost by equivalent units in process
- 6) FIFO divides period cost by equivalent production units
- 6) FIFO divides period cost by equivalent production units
- 5) Unit Cost Weighted Average divides total cost by equivalent units in process
- 4) Process that don´t add materials are also 100% DM
- 3) Materials added at beginnnig of process are considered complete
- 2) The first three schedules are the same, regardless the valuation method
- 1)Each Process Cost Report is made of 5 schedules
Variable Cost - Setting Prices
- 1) Margin Refers to Profitability measures
- 2) Variable Direct Income Statement is an alternative presentation of the Income Stat.
- 3) Variable Income Statement format is:
- Some companies use accounting methods to set prices
- Sales
- -Variable Product Cosr
- -Variable Operating Cost
- =Contribution Margin
- -Fixed Production Cost
- -Fixed Operating Cost
- =Operating Profit
- -Fixed Operating Cost
- -Fixed Production Cost
- =Contribution Margin
- -Variable Operating Cost
- -Variable Product Cosr
- 3) Variable Income Statement format is:
- 2) Variable Direct Income Statement is an alternative presentation of the Income Stat.
- 1) Margin Refers to Profitability measures
Información
- Descripción
- Mapa Mental sobre Cost Accounting, creado por Beny Pérez el 26/11/2015.
- Creado por
- Beny Pérez
- Visitas
- 0
- Valoración