
Mind map
TILA-RESPA (TRID) Rule
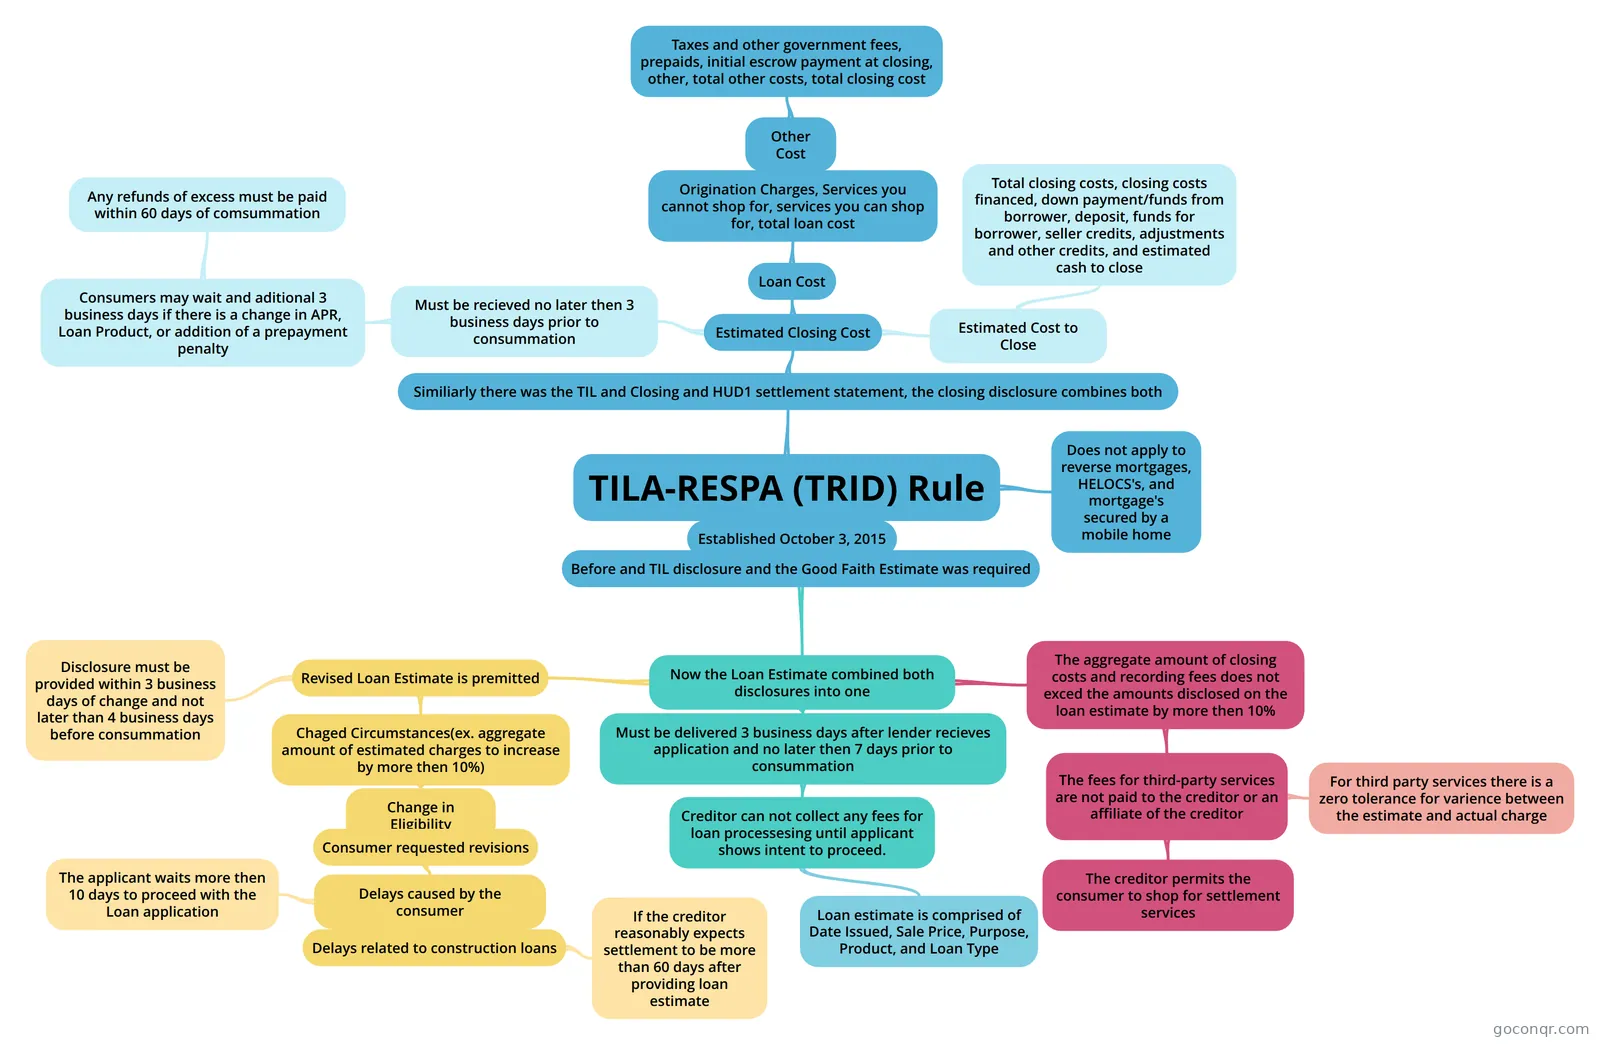
Mind map: TILA-RESPA (TRID) rule
Map content
TILA-RESPA (TRID) Rule
Established October 3, 2015
- Before and TIL disclosure and the Good Faith Estimate was required
- Now the Loan Estimate combined both disclosures into one
- Must be delivered 3 business days after lender recieves application and no later then 7 days prior to consummation
- Creditor can not collect any fees for loan processesing until applicant shows intent to proceed.
- Loan estimate is comprised of Date Issued, Sale Price, Purpose, Product, and Loan Type
- Creditor can not collect any fees for loan processesing until applicant shows intent to proceed.
- The aggregate amount of closing costs and recording fees does not exced the amounts disclosed on the loan estimate by more then 10%
- The fees for third-party services are not paid to the creditor or an affiliate of the creditor
- The creditor permits the consumer to shop for settlement services
- For third party services there is a zero tolerance for varience between the estimate and actual charge
- The fees for third-party services are not paid to the creditor or an affiliate of the creditor
- Revised Loan Estimate is premitted
- Chaged Circumstances(ex. aggregate amount of estimated charges to increase by more then 10%)
- Change in Eligibility
- Consumer requested revisions
- Delays caused by the consumer
- The applicant waits more then 10 days to proceed with the Loan application
- Delays related to construction loans
- If the creditor reasonably expects settlement to be more than 60 days after providing loan estimate
- Delays caused by the consumer
- Consumer requested revisions
- Change in Eligibility
- Disclosure must be provided within 3 business days of change and not later than 4 business days before consummation
- Chaged Circumstances(ex. aggregate amount of estimated charges to increase by more then 10%)
- Must be delivered 3 business days after lender recieves application and no later then 7 days prior to consummation
- Now the Loan Estimate combined both disclosures into one
- Before and TIL disclosure and the Good Faith Estimate was required
Similiarly there was the TIL and Closing and HUD1 settlement statement, the closing disclosure combines both
- Estimated Closing Cost
- Loan Cost
- Origination Charges, Services you cannot shop for, services you can shop for, total loan cost
- Other Cost
- Taxes and other government fees, prepaids, initial escrow payment at closing, other, total other costs, total closing cost
- Other Cost
- Origination Charges, Services you cannot shop for, services you can shop for, total loan cost
- Estimated Cost to Close
- Total closing costs, closing costs financed, down payment/funds from borrower, deposit, funds for borrower, seller credits, adjustments and other credits, and estimated cash to close
- Must be recieved no later then 3 business days prior to consummation
- Consumers may wait and aditional 3 business days if there is a change in APR, Loan Product, or addition of a prepayment penalty
- Any refunds of excess must be paid within 60 days of comsummation
- Consumers may wait and aditional 3 business days if there is a change in APR, Loan Product, or addition of a prepayment penalty
- Loan Cost
- Estimated Closing Cost
Does not apply to reverse mortgages, HELOCS's, and mortgage's secured by a mobile home
Information
- Description
- TRID Loan Closing and loan estimate
- Created by
- andrea.browne
- Views
- 89
- Tags
- Rating