
Mapa mental
CeMAP 1: Financial Regulation
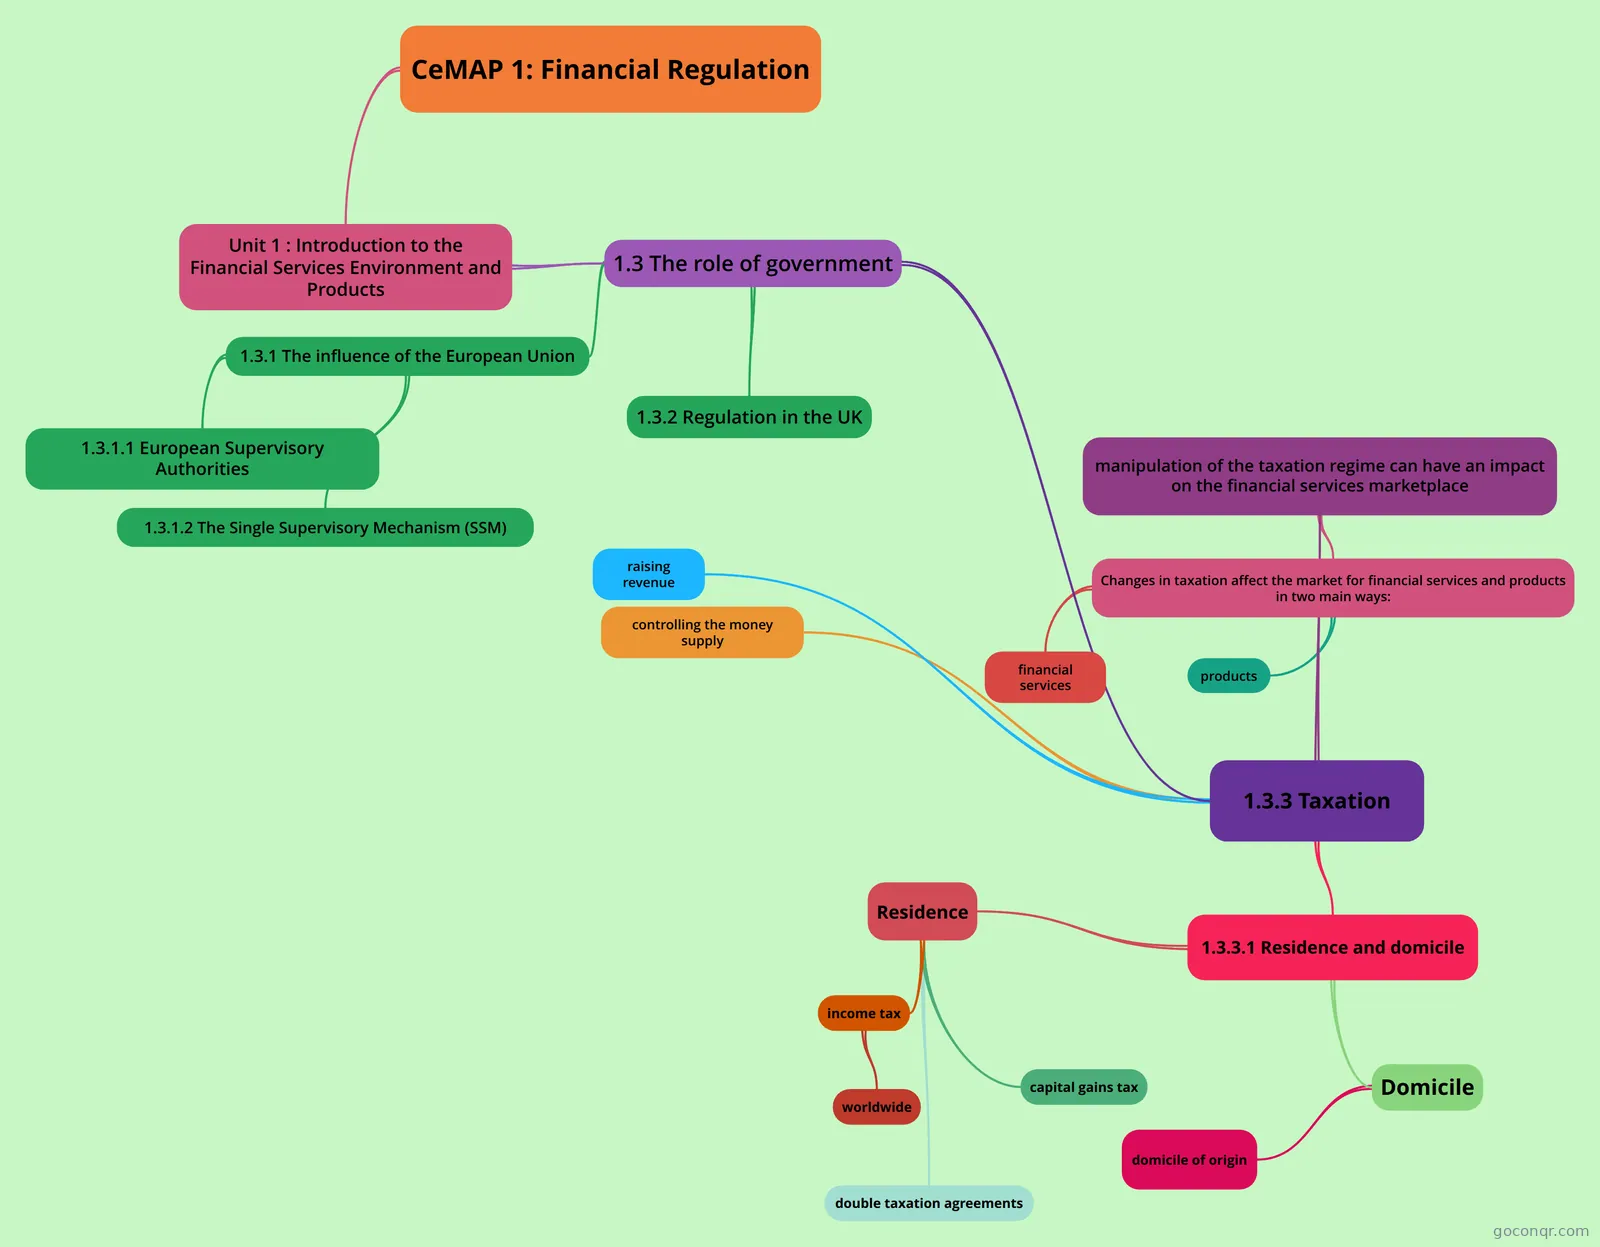
Mind map: CeMAP 1 financial regulation
Conteúdo do mapa
CeMAP 1: Financial Regulation
Unit 1 : Introduction to the Financial Services Environment and Products
- 1.3 The role of government
- 1.3.1 The influence of the European Union
- 1.3.1.1 European Supervisory Authorities
- 1.3.1.2 The Single Supervisory Mechanism (SSM)
- 1.3.2 Regulation in the UK
- 1.3.3 Taxation
- raising revenue
- controlling the money supply
- manipulation of the taxation regime can have an impact on the financial services marketplace
- Changes in taxation affect the market for financial services and products in two main ways:
- 1) increased general taxation reduces the amount of money available for investment or to fund loan repayments;
- 2) tightening of the taxation regime for particular products makes them less attractive to investors. An example of this is the government’s decision, in 1998, to remove the right of pension fund managers to reclaim tax deducted from dividends received.The effect of this step is that pension funds are now taxed on a proportion of their income, whereas previously they were effectively tax-free. Although this move was clearly made in order to bring in more tax revenue, it seems to be in conflict with the government’s acknowledged need to persuade individuals to contribute more towards their own pension provision.
- It is worth mentioning that, with many of the more popular investment schemes, such as unit trusts and investment trusts, there are two possible levels at which taxation can occur: the fund managers can be taxed and the investor can be taxed. It is essential to view both aspects when assessing the tax position of an investment.
- financial services
- products
- Changes in taxation affect the market for financial services and products in two main ways:
- 1.3.3.1 Residence and domicile
- Whether or not a person is liable to pay income tax, capital gains tax and inheritance tax will depend on the taxpayer’s residence or domicile according to UK law.
- Residence
- Residence mainly affects income tax and capital gains tax.Any person who is present in the UK for at least 183 days in a given tax year is regarded as automatically UK-resident for tax purposes.Where someone is not resident for at least 183 days in a tax year the statutory residence test is applied.This determines whether or not they will be treated as resident for a particular tax year.The nature and conditions of the tests are complex.
- income tax and capital gains tax
- present in the UK for at least 183 days in a given tax year is regarded as automatically UK-resident for tax purposes
- Where someone is not resident for at least 183 days in a tax year the statutory residence test is applied.
- income tax
- worldwide
- earned and unearned income
- whether or not such income is brought into the UK
- worldwide
- capital gains tax
- ...charged on the realisation of gains
- anywhere in the world.
- double taxation agreements
- the purpose of which is to ensure that....
- individuals are not taxed....
- twice....
- on the same income or gains.
- Domicile
- e is best described as....
- e is best described as....
- their home
- domicile of origin
- 1.3.1 The influence of the European Union
- 1.3 The role of government
Informações
- Descrição
- Mortgage Advisor course part 1
- Criado por
- Rajendra Manandhar
- Visualizações
- 98
- Tags
- Avaliação