
Mapa mental
Master Budgeting CH8
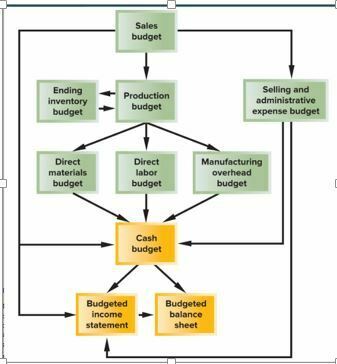
Conteúdo do mapa
Master Budgeting CH8
Budget A detailed plan for the future that is usually in formal quantitative terms
Perpetual budget 12-month budget that continuously rolls forward 1 month or 1 quarter
Planning developing goals and preparing various budgets to achieve those goals
- Control gathering feedback to ensure that the plan is being properly executed or modified as circumstances change
Organizations create budgets:
- 1. Encourage managers to think and plan for the future
- 2. communicate financial goals to the organization
- 3. allocate resources where they can be used most effectively
- 4. coordinate the plans and activities of managers
- 5. uncover bottlenecks before they happen
- 6. Improve efficiency and effectiveness of operations
- 7. Evaluate and reward employees
- 6. Improve efficiency and effectiveness of operations
- 5. uncover bottlenecks before they happen
- 4. coordinate the plans and activities of managers
- 3. allocate resources where they can be used most effectively
- 2. communicate financial goals to the organization
- 1. Encourage managers to think and plan for the future
Self-imposed budget or participative budget A method of preparing budgets in which managers prepare their own budgets. These budgets are then reviewed by higher-level managers, and any issues are resolved by mutual agreement.
Master budget A number of separate but interdependent budgets that formally lay out the company’s sales, production, and financial goals and that culminates in a cash budget, budgeted income statement, and budgeted balance sheet.
Sales budget A detailed schedule showing expected sales expressed in both dollars and units.
Production budget A detailed plan showing the number of units that must be produced during a period in order to satisfy both sales and inventory needs
Merchandise purchases budget A detailed plan used by a merchandising company that shows the amount of goods that must be purchased from suppliers during the period.
Direct materials budget A detailed plan showing the amount of raw materials that must be purchased to fulfill the production budget and to provide for adequate inventories.
Direct labor budget A detailed plan that shows the direct labor-hours required to fulfill the production budge
Manufacturing overhead budget A detailed plan showing the production costs, other than direct materials and direct labor, that will be incurred over a specified time period.
Ending finished goods inventory budget A budget showing the dollar amount of unsold finished goods inventory that will appear on the ending balance sheet.
Selling and administrative expense budget A detailed schedule of planned expenses that will be incurred in areas other than manufacturing during a budget period.
Cash Budget has 4 main sections: Cash receipts, cash distributions, excess or deficiency, financing
Budget income statement shows the company’s planned profits and serves as a benchmark against which subsequent company performance can be measured
Budgeted balance sheet developed from data from the balance sheet and various schedules