
Notas
1102AFE Notes
Conteúdo das notas (1)
Página 1
The Five-Step Decision Making Model
Natural sequence of thought to make not only big descisions but a whole range of small decisions in the daily life, which may have cumulative effects.
Define/identify the objective
Clearly know what are we trying to achieve.
Obtain relevant information
The current problem is Information Overload, but more information does not mean better decisions.
Relevant information is information really needed to make the decision. Answer the question: Is this relevant?
Generate feasible options/alternatives
Include all possibilities capable of being done or realised (four or five options).
Discard the worst options to have no more than two or three alternatives
Make a decision
Establish the selection criteria divided into different levels of priority (e.g. must, should or highly desirable and might).
Examine consequences of each course and weight the risks against the expected gain (is acceptable the worst scenario?
Implement and evaluate
This is the action phase, after the cut off point (when thinking ends), but decision is still being evaluated until the point of no return committed.
The point of no return is the point at which it cost you more to turn back or change your mind than to continue with a decision that you know to be an imperfect one.
Evaluate Did you get it right? (comparison between your expected results with the actual results after the decision was implemented.
A unified model for Decision Making and Problem Solving
Relationship between problem and decision making
Obstacle. A problem is an obstacle or difficulties placed in front of us but secondary to the result of decision making. Decisions create problems. To solve a problem:
Alter your decision or at least your plan Plan B
Find a way to overcoming the problem to stick with the decision.
System problem. System is a whole made up of integrated parts. To solve a system problem:
Find the point of deviation and establish what caused it.
Define the objective/identify the problem analysis.
Where are you now and where do you want to get to?
Do you need more information?
“A problem properly defined is a problem half-solved”
Generating feasible options synthesis.
Have you checked the main assumptions?
Possible solutions or courses?
Criteria how to judge each option?
Evaluate the decision and implement it valuation.
Have you used all available and relevant information?
Have you a realistic implementation plan?
Do you have a contingency plan?
Types of businesses
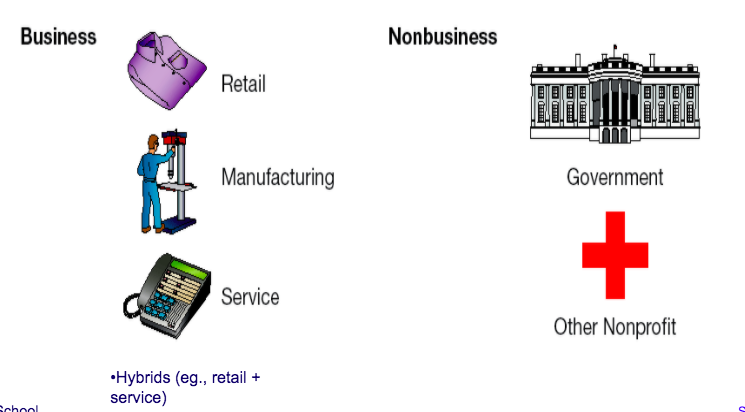
Organisations can be classified as business and non-business organisations depending on the type of goods and services they offer and if “profit” is a goal.
Types of business
Business
Retail
A retail business buys products from a manufacturer or wholesaler and sells them to consumers. e.g. Bunnings, Kmart, JB Hi-Fi, Woolworths.
Manufacturing
A manufacturing business buys and uses components, parts or raw materials to make a finished good. These finished goods can be sold directly to consumers, to wholesalers, to retailers or to other manufacturing businesses that use them for making a different product. e.g. CSL (pharmaceutical), Orica (chemical), Amcor (polymer product).
Service
A service business provides work performed by an individual or team to its clients or customers. e.g. accounting, banking, consulting and education.
Non-business or not for profit
An organization with other purposes other than generating profit, such as hospitals, universities, national charities, churches and foundations.
Business Structures
A BUSINESS is an entity or organisation that engages in the trading of goods and/or services, but most frequently is established for enhancing the wealth of the owners Profit.
ACCOUNTING ENTITY All forms of businesses are a separate entity from the owner(s) of the business for accounting purposes (i.e. business transactions are recorded separately from personal transactions involving the owner(s)).
LEGAL ENTITY Entity that is legally separated from its owners and recognised as a legal person (i.e. it has the same rights and obligations as a natural person, for example, a legal person can enter into contracts, incur debts, own property and pay taxes independently of its owners)
The basic forms of business structure are:
Sole trader/Proprietorship
A sole proprietorship is a business owned and operated by one person for profit.
Gives you full control of your assets and business decisions.
Minimal regulation:
No Act governs sole traders.
No particular reporting requirements.
No extensive costs of set-up. Limited requirements (e.g. the general registration requirements involve applying for an ABN*).
Limited life (restricted to the period during which the owner continues to operate the business)
Unlimited liability (the owner is personally responsible for the debts and obligations of the business) it is not a separate legal entity
Limited access to funds (restricted to the personal resources of a single owner)
e.g. Plumbers, Electricians, Hairdressers, Carpenters etc.
Advantages:
Simple and inexpensive to establish and operate
Minimal financial reporting regulations
Financial rewards flow directly to the owner
Timely decision-making is possible
Disadvantages
Unlimited liability – bears full responsibility for business debts, any legal actions such as negligence
Limited by skill, time and investment of owner
Business will cease to exist if owner leaves, retires or dies
Partnership
Two or more persons carrying on a business with a view to profit
Evidence of a partnership?
formal partnership agreement OR
informal arrangement between the parties
Limited life (Dissolved on death or withdrawal of one of partners)
Unlimited liability
Mutual agency (each partner is responsible for the actions of the other partners, has the right to enter in contracts on behalf of the partnership, and each of them have unlimited liability for the debts and obligations of the partnership)
Co-ownership of assets (the partnership assets are owned by the partners in aggregate, not individually
Numbers limited - normally 20 is the maximum.
While there is no Act governing a sole trader, the Partnership Act 1891 (Qld) directs the activities and rights and responsibilities of partners.
Issues not covered by the partnership agreement will be governed by the Partnership Act (e.g. all profits and losses will be shared equally between the partners).
Partnership agreements include details such as:
Name of partnership
Partner contributions of cash and other assets
Profit and loss sharing ratios (based on financial and non-financial contributions)
Entry and exit information
Advantages:
Relatively easy and simple to set up. An ABN must be applied for.
Informal business structure – not bound by accounting standards
Ability to share capital, skills, talents, knowledge and workload between two or more people
The partnership doesn't pay income tax on the profit it earns – each partner reports their share of the partnership income in their own tax return. However, the partnership has to prepare an annual tax return.
Disadvantages:
Unlimited liability for business debts and obligations
Limited life – if a partner withdraws from the partnership, or if a partner dies, then the partnership must dissolve
Company
Independent legal entity (i.e. separate from the people who own, control and manage it) can sue and be sued, buy, borrow, lend and employ in its own right as a legal person
Owners of a company are shareholders
Shareholders have limited liability. Limited to the unpaid purchase price (if any) of their shares.
A company has unlimited life – not dissolved when there is a change of ownership, or when owners die
Assets are owned by the company in its own right (as a legal person)
Company profits belong to shareholders. Either distributed (as dividends) or retained in the firm (retained earnings, which means “retained profits”)
Separation of ownership and management
Managers may also be shareholders, but often a separate specialist management team (not owners) exists
Extensive regulation. In addition to legislative requirements, companies have extensive reporting requirements to shareholders and markets.
Regulation:
1. Legislation (Corporations Act 2001 (Cwlth)), and
2. Organisations such as the following (Birt p 13-16):
Australian Securities & Investments Commission (ASIC)
Australian Securities Exchange (ASX)
Australian Competition & Consumer Commission (ACCC)
Reserve Bank of Australia (RBA)
Australian Prudential Regulation Authority (APRA)
Australian Taxation Office (ATO)
Other government agencies
Advantages:
Perpetual existence
Owners (shareholders) have limited liability
Greater access to funds:
More equity available because more owners
Potentially greater access to debt (borrowing)
Potential taxation advantages – tax rate 30%. Top rate for individuals is much higher.
Disadvantages:
Higher establishment costs and time consuming to establish
Extensive regulation
Owners not able to watch everything (separation of ownership and management)
Limited liability aspect may cause problems, e.g. Banks lending to companies may require director’s personal guarantee
Types of companies:
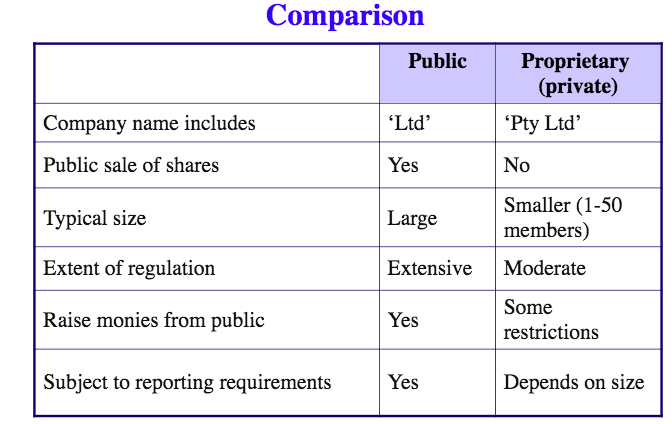
Proprietary company (Pty Ltd)
A proprietary company is a private company designed for a relatively small group of shareholders (they should have at least one shareholder) .
It cannot have more than 50 shareholders (owners) and cannot invite the public to subscribe for share (does not sell its shares to the general public).
Public companies (Ltd)
A public company can generally be identified by the company name ending with the word 'limited' or the abbreviation ‘Ltd’.
Types of public companies:
Limited by shares (offer shares to the public, at least 1 shareholder and 3 directors)
Limited by guarantee (owners guarantee to contribute specific amount in case of the company winding up)
No-liability company (NL) (not liable for amounts owed on shares)
Unlimited company (shareholders have no limit placed on their liability)
Limit to liability
If your shares are fully paid-up your liability is ZERO.
eg. If you buy 1,000 $6 shares ($6,000 worth) and you have paid 2/3 of that amount ($4,000), then in the event of difficulties for the company the limit of your liability to the company is $2,000 (which is the amount unpaid on your shares).
Business Structure and Decision Making
The advantages and disadvantages of the different business structures would be considered in choosing a structure for your business.
Some things to consider:
Tax issues
Funding issues
Expertise issues
Prefer working by yourself?
Risk preference?
Support issues
Accounting Information and its Role in Decision Making
Accounting is the process of identifying, measuring and communicating relevant economic information (Business Transactions) about a particular business to a variety of users for making informed decisions.
What does this tell us?
Purpose of accounting – making informed decisions
Accounting has a number of components:
analytical (identifying data – business transactions)
technical (measuring data)
communication – to whom? what form?
- Implies information has value in the decision making process.
Business transactions:
They involve the:
External exchange of something of value between two or more entities (one of which is the business firm).
They can be reliably measured and recorded
They affect assets, liabilities and equity (see topic 2)
What is relevant information:
Information that makes a difference in decision making
Accounting information is designed to meet the needs of both:
Internal Users (Management) = Special Purpose Reports
External Users (Investors, Suppliers, Banks, Govt. Authorities etc.) = General Purpose Reports
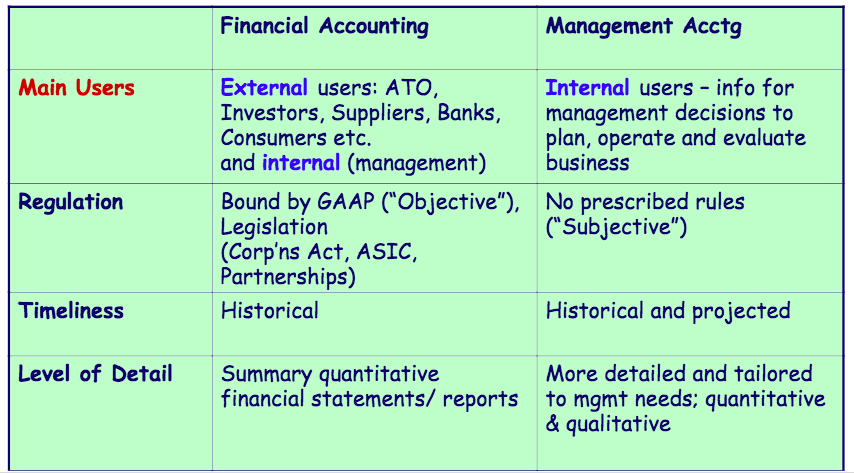
Financial Accounting vs Management Accounting
[Main Users, External users: ATO, Investors, Suppliers, Banks, Consumers etc. and internal (management), Internal users – info for management decisions to plan, operate and evaluate business, regulation, Bound by GAAP (“Objective”), Legislation
(Corp’ns Act, ASIC, Partnerships), No prescribed rules (“Subjective”), Historical, Historical and projected, Summary quantitative financial statements/ reports, More detailed and tailored to mgmt needs; quantitative & qualitative]
Financial accounting
Preparing and presenting financial statements primarily for external parties. Statements are prepared in accordance with Generally Accepted Accounting Principles (GAAP)
Financial statements (general purpose reports). They are accounting reports that summarize and communicate financial information about a company primarily to external users. They consist of:
Income statement
Statement of changes in equity
Balance sheet
Statement of cash flows
Management accounting
Preparing internal reports for management to assist decision making (e.g. budgets, production cost report, cost analysis)
Not regulated by rules like financial accounting
Core activities include
Formulating plans and budgets
Providing information used in monitoring and controlling performance
Some management accounting reports are used by financial accountants in preparing the firm’s external reports.
Managers of firms make use of both internal (management accounting) reports and external (financial accounting) reports for decision making.
How businesses create value
A common purpose of organisations: to transform resources from one form to another (goods and services)
What resources? Any: natural, physical and financial resources, management skills, labour, information…
What is the purpose of the transformation of resources?
To create value
How value is created?
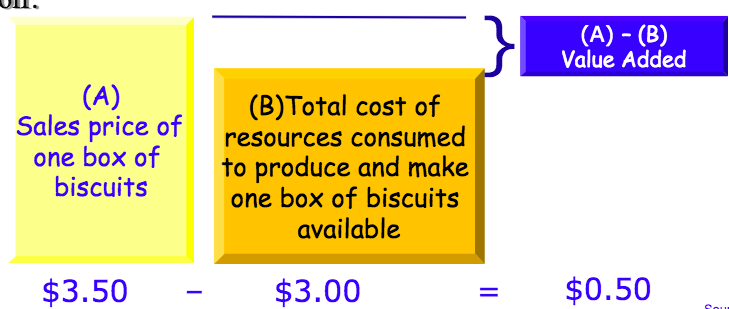
Value is created when resources in existing form (resources consumed) are transformed to another more valuable form (resources created). Value added is the difference between resources created and resources consumed.
Value is added to society when an organisation transforms resources from a less desirable form or location to a more desirable form or location.
Value is created
Providing a product or service that customers value, a business organization generates sales (revenue).
Ensuring that the value for customers, and hence the revenue, exceeds the cost of providing the product or service, an organization’s customers will be satisfied, the organization will make a profit and society will be better off.
Informações
- Descrição
- 1102AFE Accounting Notas sobre 1102AFE Notes, criado por Juliette Cross em 08-11-2020.
- Criado por
- Juliette Cross
- Visualizações
- 0
- Avaliação