
Mindmap
PHILIPPINE FRAMEWORK FOR ASSURANCE ENGAGEMENTS
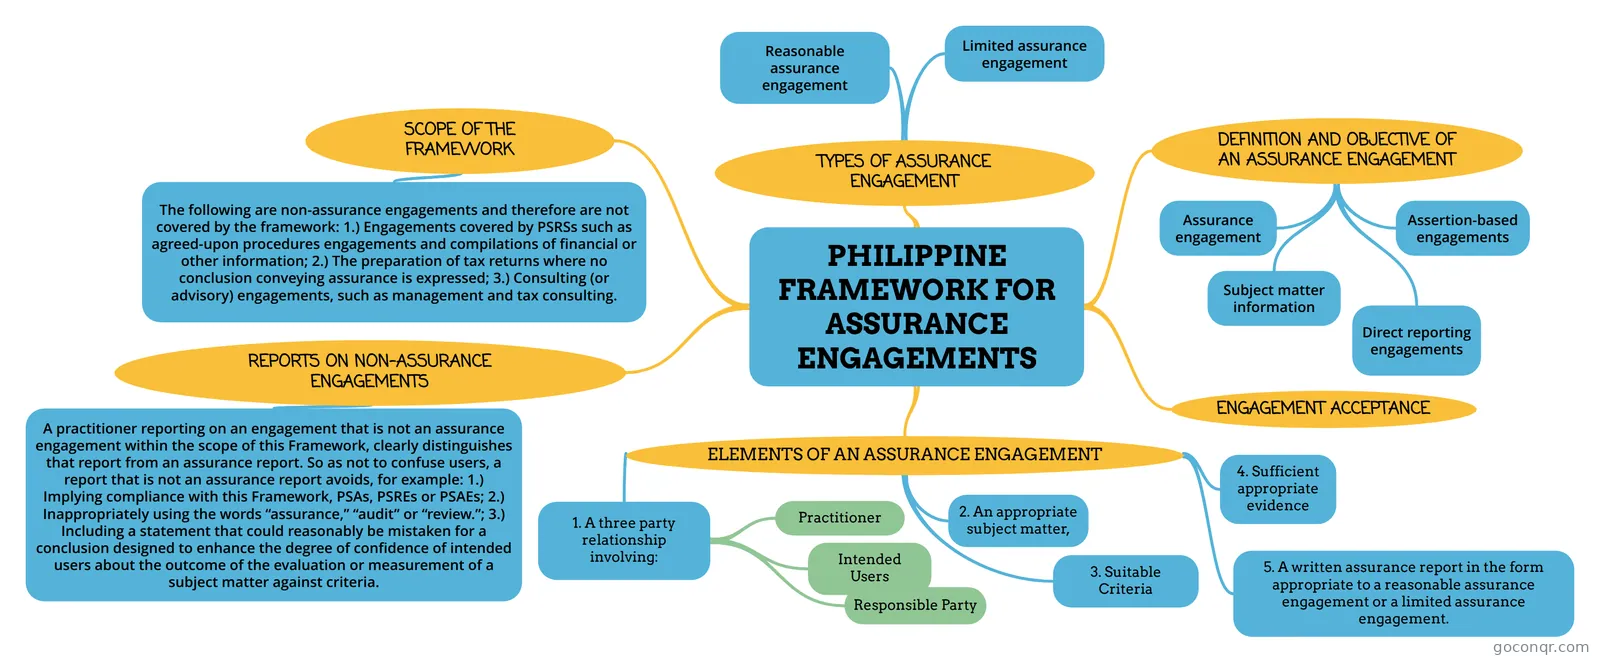
Mind map: Philippine framework for assurance engagements
Inhalt der Mindmap
PHILIPPINE FRAMEWORK FOR ASSURANCE ENGAGEMENTS
DEFINITION AND OBJECTIVE OF AN ASSURANCE ENGAGEMENT
- Assurance engagement
- Subject matter information
- Assertion-based engagements
- Direct reporting engagements
TYPES OF ASSURANCE ENGAGEMENT
- Reasonable assurance engagement
- Limited assurance engagement
SCOPE OF THE FRAMEWORK
- The following are non-assurance engagements and therefore are not covered by the framework: 1.) Engagements covered by PSRSs such as agreed-upon procedures engagements and compilations of financial or other information; 2.) The preparation of tax returns where no conclusion conveying assurance is expressed; 3.) Consulting (or advisory) engagements, such as management and tax consulting.
REPORTS ON NON-ASSURANCE ENGAGEMENTS
- A practitioner reporting on an engagement that is not an assurance engagement within the scope of this Framework, clearly distinguishes that report from an assurance report. So as not to confuse users, a report that is not an assurance report avoids, for example: 1.) Implying compliance with this Framework, PSAs, PSREs or PSAEs; 2.) Inappropriately using the words “assurance,” “audit” or “review.”; 3.) Including a statement that could reasonably be mistaken for a conclusion designed to enhance the degree of confidence of intended users about the outcome of the evaluation or measurement of a subject matter against criteria.
ENGAGEMENT ACCEPTANCE
ELEMENTS OF AN ASSURANCE ENGAGEMENT
- 1. A three party relationship involving:
- Practitioner
- Responsible Party
- Intended Users
- 2. An appropriate subject matter,
- 3. Suitable Criteria
- 4. Sufficient appropriate evidence
- 5. A written assurance report in the form appropriate to a reasonable assurance engagement or a limited assurance engagement.
- 1. A three party relationship involving: