
Mapa mental
PBKT
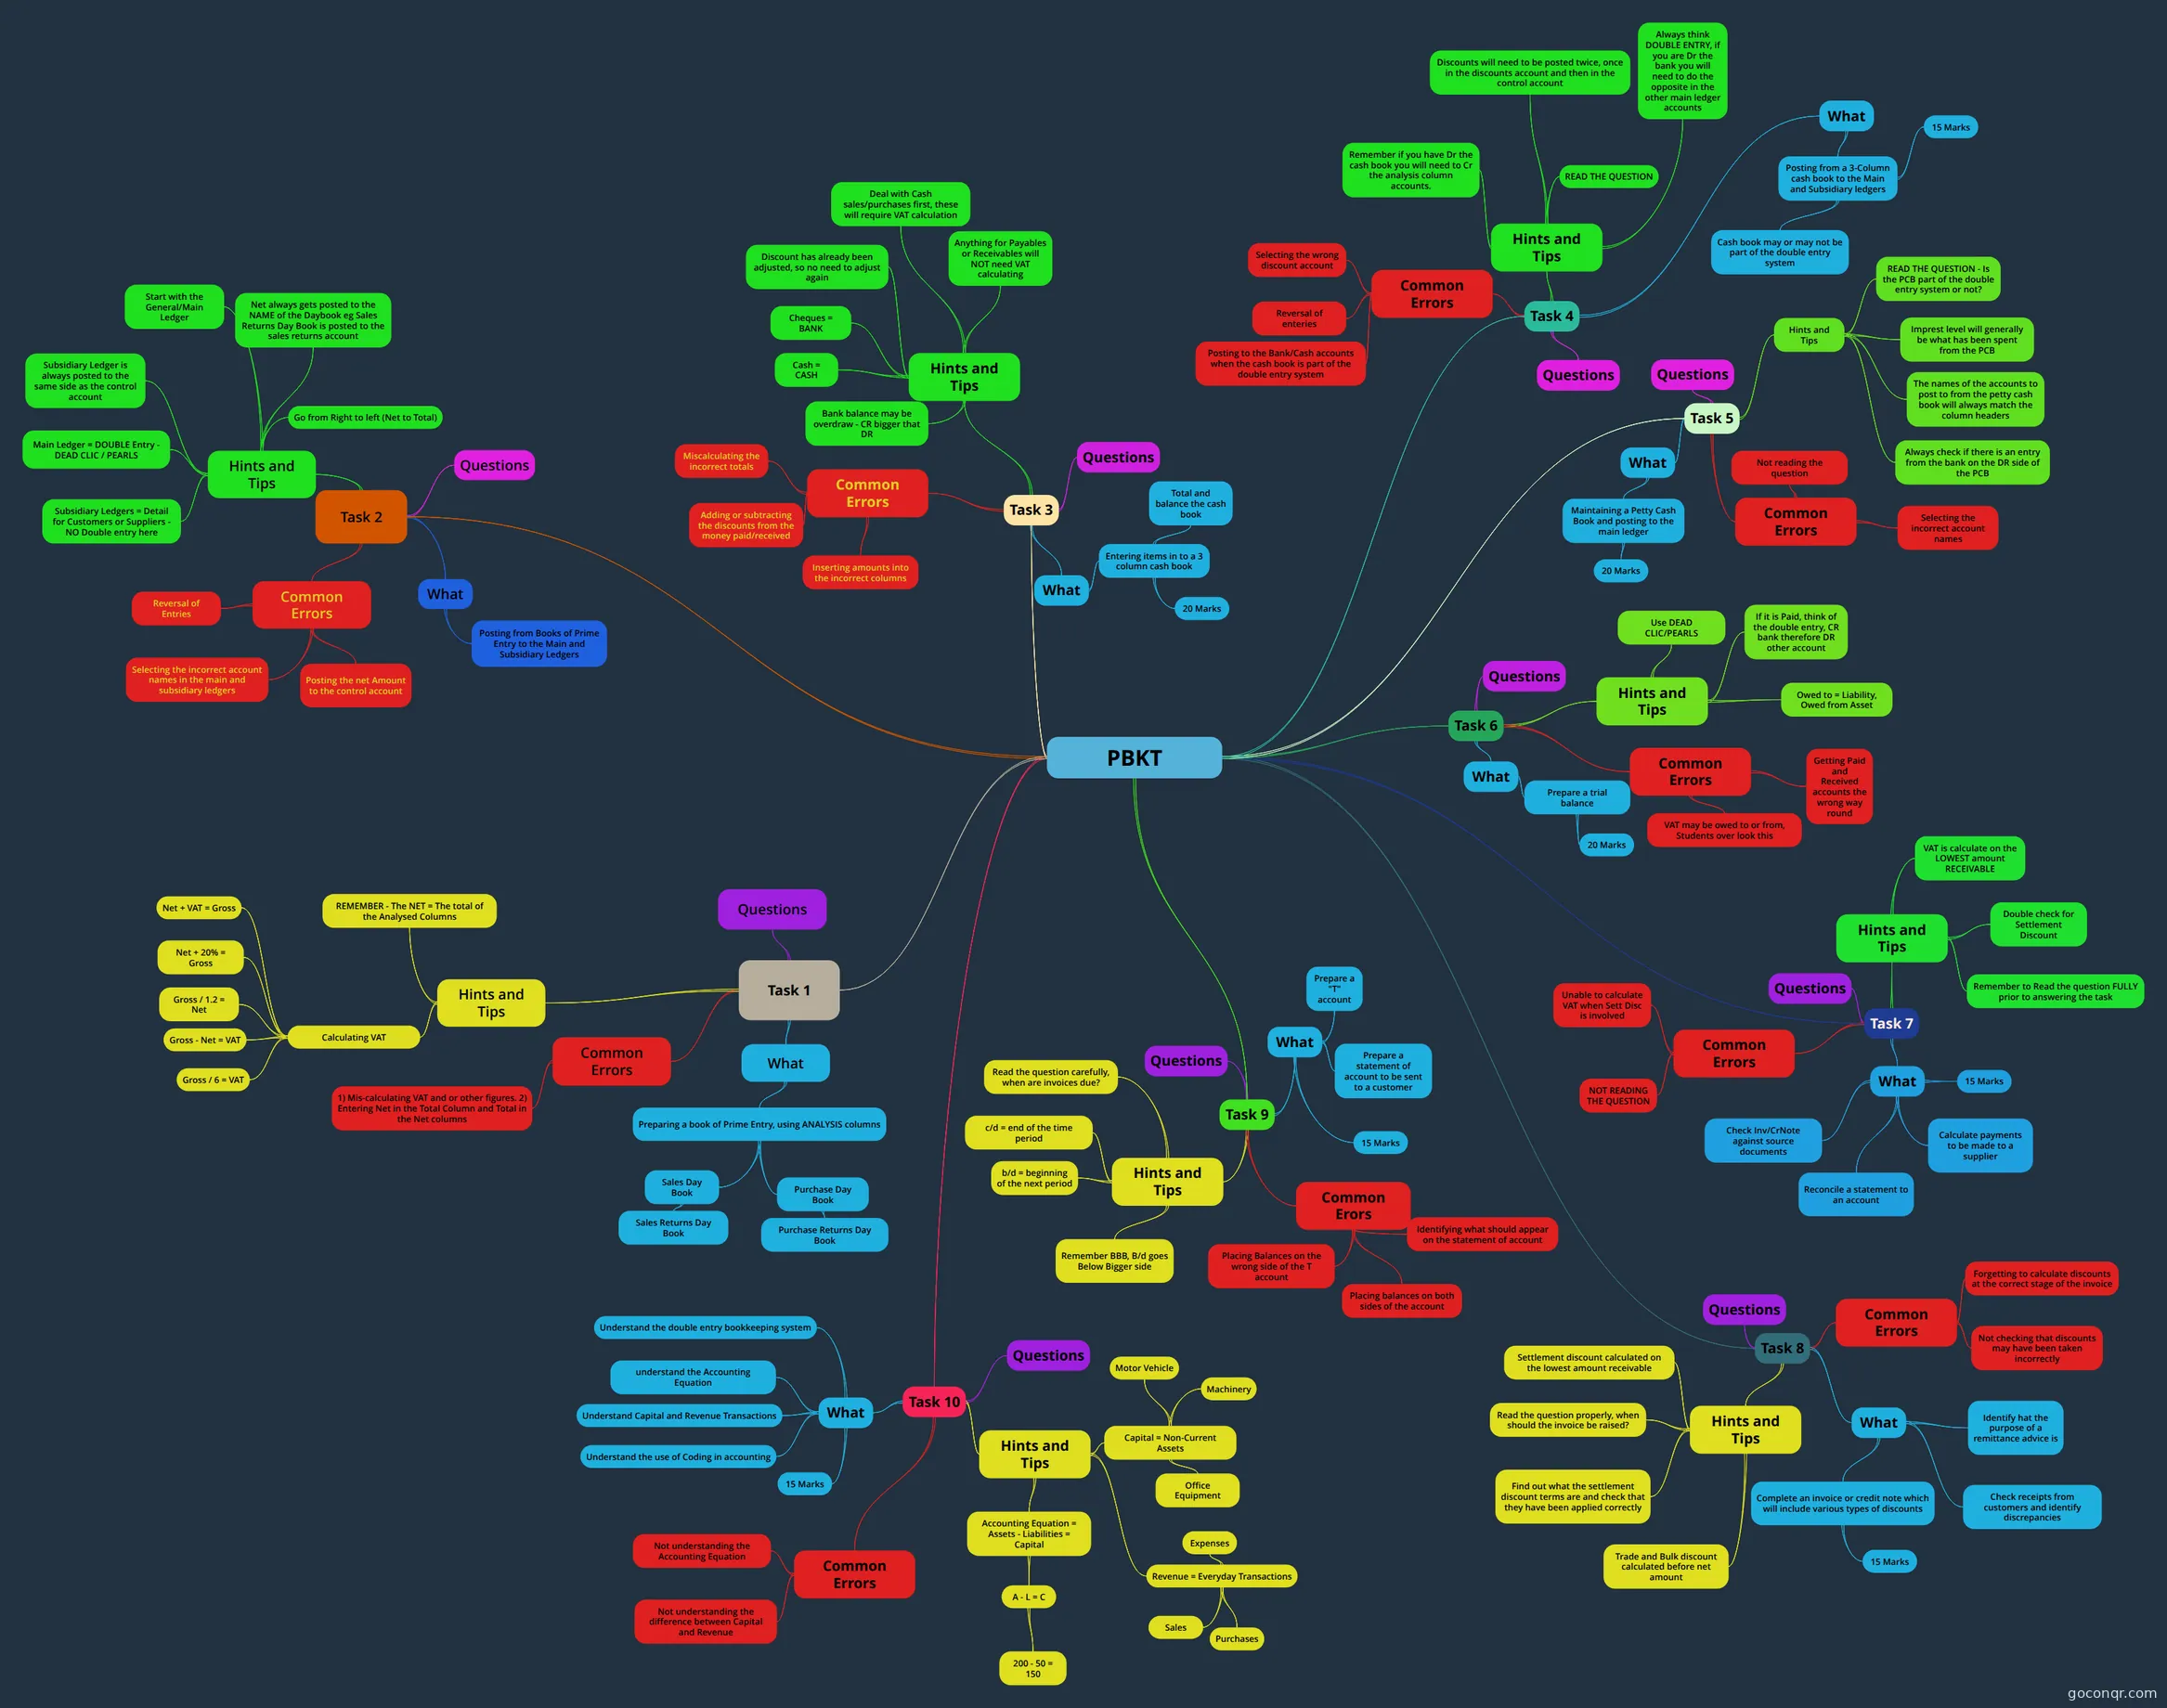
Mind map: PBKT tasks
Contenido del mapa
PBKT
Task 1
- What
- Preparing a book of Prime Entry, using ANALYSIS columns
- Sales Day Book
- Sales Returns Day Book
- Purchase Day Book
- Purchase Returns Day Book
- Sales Day Book
- Preparing a book of Prime Entry, using ANALYSIS columns
- Hints and Tips
- Calculating VAT
- Net + 20% = Gross
- Gross / 6 = VAT
- Gross / 1.2 = Net
- Gross - Net = VAT
- Net + VAT = Gross
- REMEMBER - The NET = The total of the Analysed Columns
- Calculating VAT
- Common Errors
- 1) Mis-calculating VAT and or other figures. 2) Entering Net in the Total Column and Total in the Net columns
- Questions
- What
Task 2
- What
- Posting from Books of Prime Entry to the Main and Subsidiary Ledgers
- Common Errors
- Reversal of Entries
- Posting the net Amount to the control account
- Selecting the incorrect account names in the main and subsidiary ledgers
- Questions
- Hints and Tips
- Main Ledger = DOUBLE Entry - DEAD CLIC / PEARLS
- Subsidiary Ledgers = Detail for Customers or Suppliers - NO Double entry here
- Start with the General/Main Ledger
- Go from Right to left (Net to Total)
- Net always gets posted to the NAME of the Daybook eg Sales Returns Day Book is posted to the sales returns account
- Subsidiary Ledger is always posted to the same side as the control account
- What
Task 3
- What
- Entering items in to a 3 column cash book
- 20 Marks
- Total and balance the cash book
- Entering items in to a 3 column cash book
- Common Errors
- Adding or subtracting the discounts from the money paid/received
- Inserting amounts into the incorrect columns
- Miscalculating the incorrect totals
- Questions
- Hints and Tips
- Discount has already been adjusted, so no need to adjust again
- Cheques = BANK
- Cash = CASH
- Bank balance may be overdraw - CR bigger that DR
- Deal with Cash sales/purchases first, these will require VAT calculation
- Anything for Payables or Receivables will NOT need VAT calculating
- What
Task 4
- What
- Posting from a 3-Column cash book to the Main and Subsidiary ledgers
- Cash book may or may not be part of the double entry system
- 15 Marks
- Posting from a 3-Column cash book to the Main and Subsidiary ledgers
- Common Errors
- Reversal of enteries
- Posting to the Bank/Cash accounts when the cash book is part of the double entry system
- Selecting the wrong discount account
- Questions
- Hints and Tips
- Remember if you have Dr the cash book you will need to Cr the analysis column accounts.
- Discounts will need to be posted twice, once in the discounts account and then in the control account
- READ THE QUESTION
- Always think DOUBLE ENTRY, if you are Dr the bank you will need to do the opposite in the other main ledger accounts
- What
Task 5
- What
- Maintaining a Petty Cash Book and posting to the main ledger
- 20 Marks
- Maintaining a Petty Cash Book and posting to the main ledger
- Common Errors
- Not reading the question
- Selecting the incorrect account names
- Questions
- Hints and Tips
- The names of the accounts to post to from the petty cash book will always match the column headers
- Always check if there is an entry from the bank on the DR side of the PCB
- READ THE QUESTION - Is the PCB part of the double entry system or not?
- Imprest level will generally be what has been spent from the PCB
- What
Task 6
- What
- Prepare a trial balance
- 20 Marks
- Prepare a trial balance
- Common Errors
- Getting Paid and Received accounts the wrong way round
- VAT may be owed to or from, Students over look this
- Questions
- Hints and Tips
- If it is Paid, think of the double entry, CR bank therefore DR other account
- Owed to = Liability, Owed from Asset
- Use DEAD CLIC/PEARLS
- What
Task 7
- What
- Check Inv/CrNote against source documents
- 15 Marks
- Reconcile a statement to an account
- Calculate payments to be made to a supplier
- Common Errors
- NOT READING THE QUESTION
- Unable to calculate VAT when Sett Disc is involved
- Hints and Tips
- VAT is calculate on the LOWEST amount RECEIVABLE
- Remember to Read the question FULLY prior to answering the task
- Double check for Settlement Discount
- Questions
- What
Task 8
- What
- Complete an invoice or credit note which will include various types of discounts
- 15 Marks
- Check receipts from customers and identify discrepancies
- Identify hat the purpose of a remittance advice is
- Complete an invoice or credit note which will include various types of discounts
- Common Errors
- Forgetting to calculate discounts at the correct stage of the invoice
- Not checking that discounts may have been taken incorrectly
- Hints and Tips
- Trade and Bulk discount calculated before net amount
- Settlement discount calculated on the lowest amount receivable
- Find out what the settlement discount terms are and check that they have been applied correctly
- Read the question properly, when should the invoice be raised?
- Questions
- What
Task 9
- What
- Prepare a "T" account
- Prepare a statement of account to be sent to a customer
- 15 Marks
- Common Erors
- Placing Balances on the wrong side of the T account
- Placing balances on both sides of the account
- Identifying what should appear on the statement of account
- Hints and Tips
- Remember BBB, B/d goes Below Bigger side
- c/d = end of the time period
- b/d = beginning of the next period
- Read the question carefully, when are invoices due?
- Questions
- What
Task 10
- What
- Understand the double entry bookkeeping system
- understand the Accounting Equation
- Understand Capital and Revenue Transactions
- Understand the use of Coding in accounting
- 15 Marks
- Common Errors
- Not understanding the Accounting Equation
- Not understanding the difference between Capital and Revenue
- Hints and Tips
- Accounting Equation = Assets - Liabilities = Capital
- A - L = C
- 200 - 50 = 150
- A - L = C
- Capital = Non-Current Assets
- Motor Vehicle
- Machinery
- Office Equipment
- Revenue = Everyday Transactions
- Sales
- Purchases
- Expenses
- Accounting Equation = Assets - Liabilities = Capital
- Questions
- What
Información
- Descripción
- Mind map with questions for the AAT level 2 Processing Bookkeeping Transactions (PBKT) examination.
- Creado por
- stephen.ainswort
- Visitas
- 124
- Etiquetas
- Valoración