
Mapa mental
Subunit 1: Applicable Standards
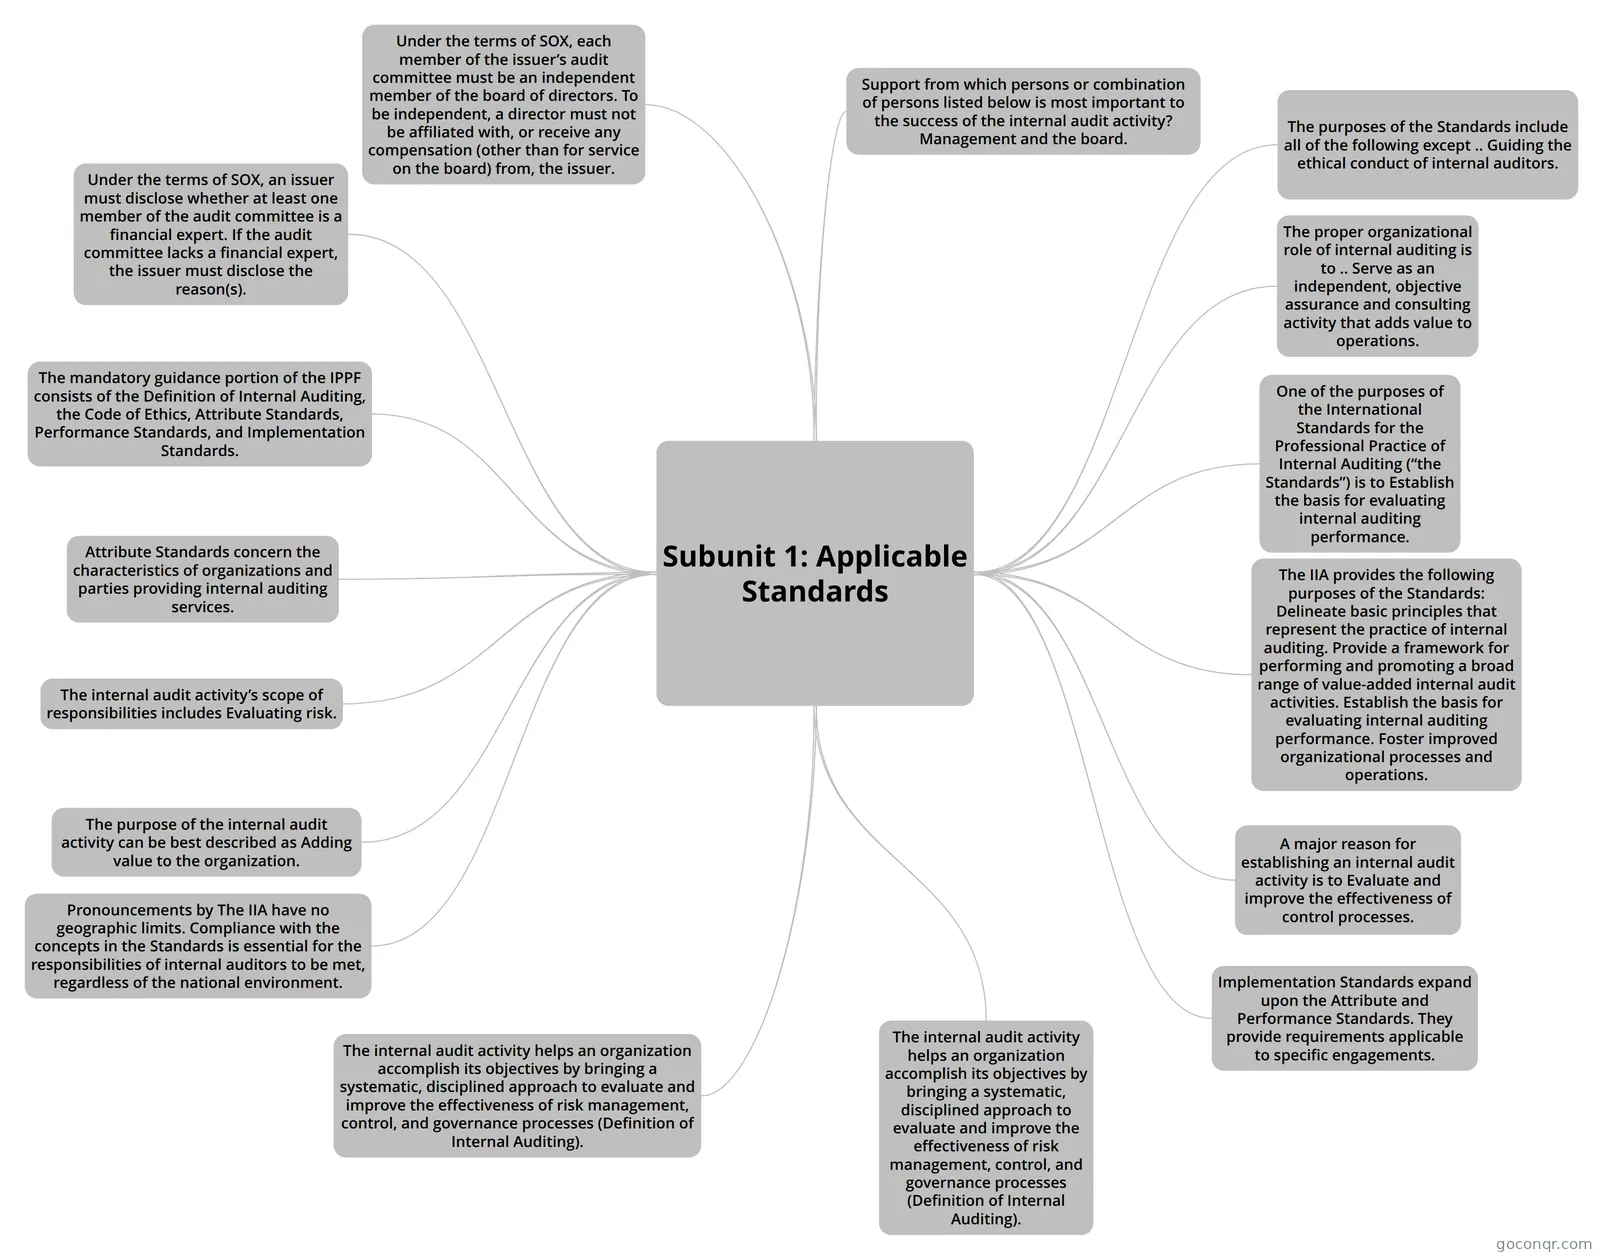
Mind map: Internal auditing standards and purposes
Contenido del mapa
Subunit 1: Applicable Standards
The purposes of the Standards include all of the following except .. Guiding the ethical conduct of internal auditors.
The proper organizational role of internal auditing is to .. Serve as an independent, objective assurance and consulting activity that adds value to operations.
One of the purposes of the International Standards for the Professional Practice of Internal Auditing (“the Standards”) is to Establish the basis for evaluating internal auditing performance.
The IIA provides the following purposes of the Standards: Delineate basic principles that represent the practice of internal auditing. Provide a framework for performing and promoting a broad range of value-added internal audit activities. Establish the basis for evaluating internal auditing performance. Foster improved organizational processes and operations.
Implementation Standards expand upon the Attribute and Performance Standards. They provide requirements applicable to specific engagements.
A major reason for establishing an internal audit activity is to Evaluate and improve the effectiveness of control processes.
The internal audit activity helps an organization accomplish its objectives by bringing a systematic, disciplined approach to evaluate and improve the effectiveness of risk management, control, and governance processes (Definition of Internal Auditing).
The internal audit activity helps an organization accomplish its objectives by bringing a systematic, disciplined approach to evaluate and improve the effectiveness of risk management, control, and governance processes (Definition of Internal Auditing).
Pronouncements by The IIA have no geographic limits. Compliance with the concepts in the Standards is essential for the responsibilities of internal auditors to be met, regardless of the national environment.
The purpose of the internal audit activity can be best described as Adding value to the organization.
The internal audit activity’s scope of responsibilities includes Evaluating risk.
Attribute Standards concern the characteristics of organizations and parties providing internal auditing services.
The mandatory guidance portion of the IPPF consists of the Definition of Internal Auditing, the Code of Ethics, Attribute Standards, Performance Standards, and Implementation Standards.
Under the terms of SOX, an issuer must disclose whether at least one member of the audit committee is a financial expert. If the audit committee lacks a financial expert, the issuer must disclose the reason(s).
Under the terms of SOX, each member of the issuer’s audit committee must be an independent member of the board of directors. To be independent, a director must not be affiliated with, or receive any compensation (other than for service on the board) from, the issuer.
Support from which persons or combination of persons listed below is most important to the success of the internal audit activity? Management and the board.
Información
- Descripción
- 1 Basic audit and Controls Mapa Mental sobre Subunit 1: Applicable Standards, creado por murtaza.sunelwala el 04/02/2016.
- Creado por
- murtaza.sunelwala
- Visitas
- 1
- Valoración
Más sobre Internal Audit Standards and Ethics