
Mapa mental
Trade and other receivables
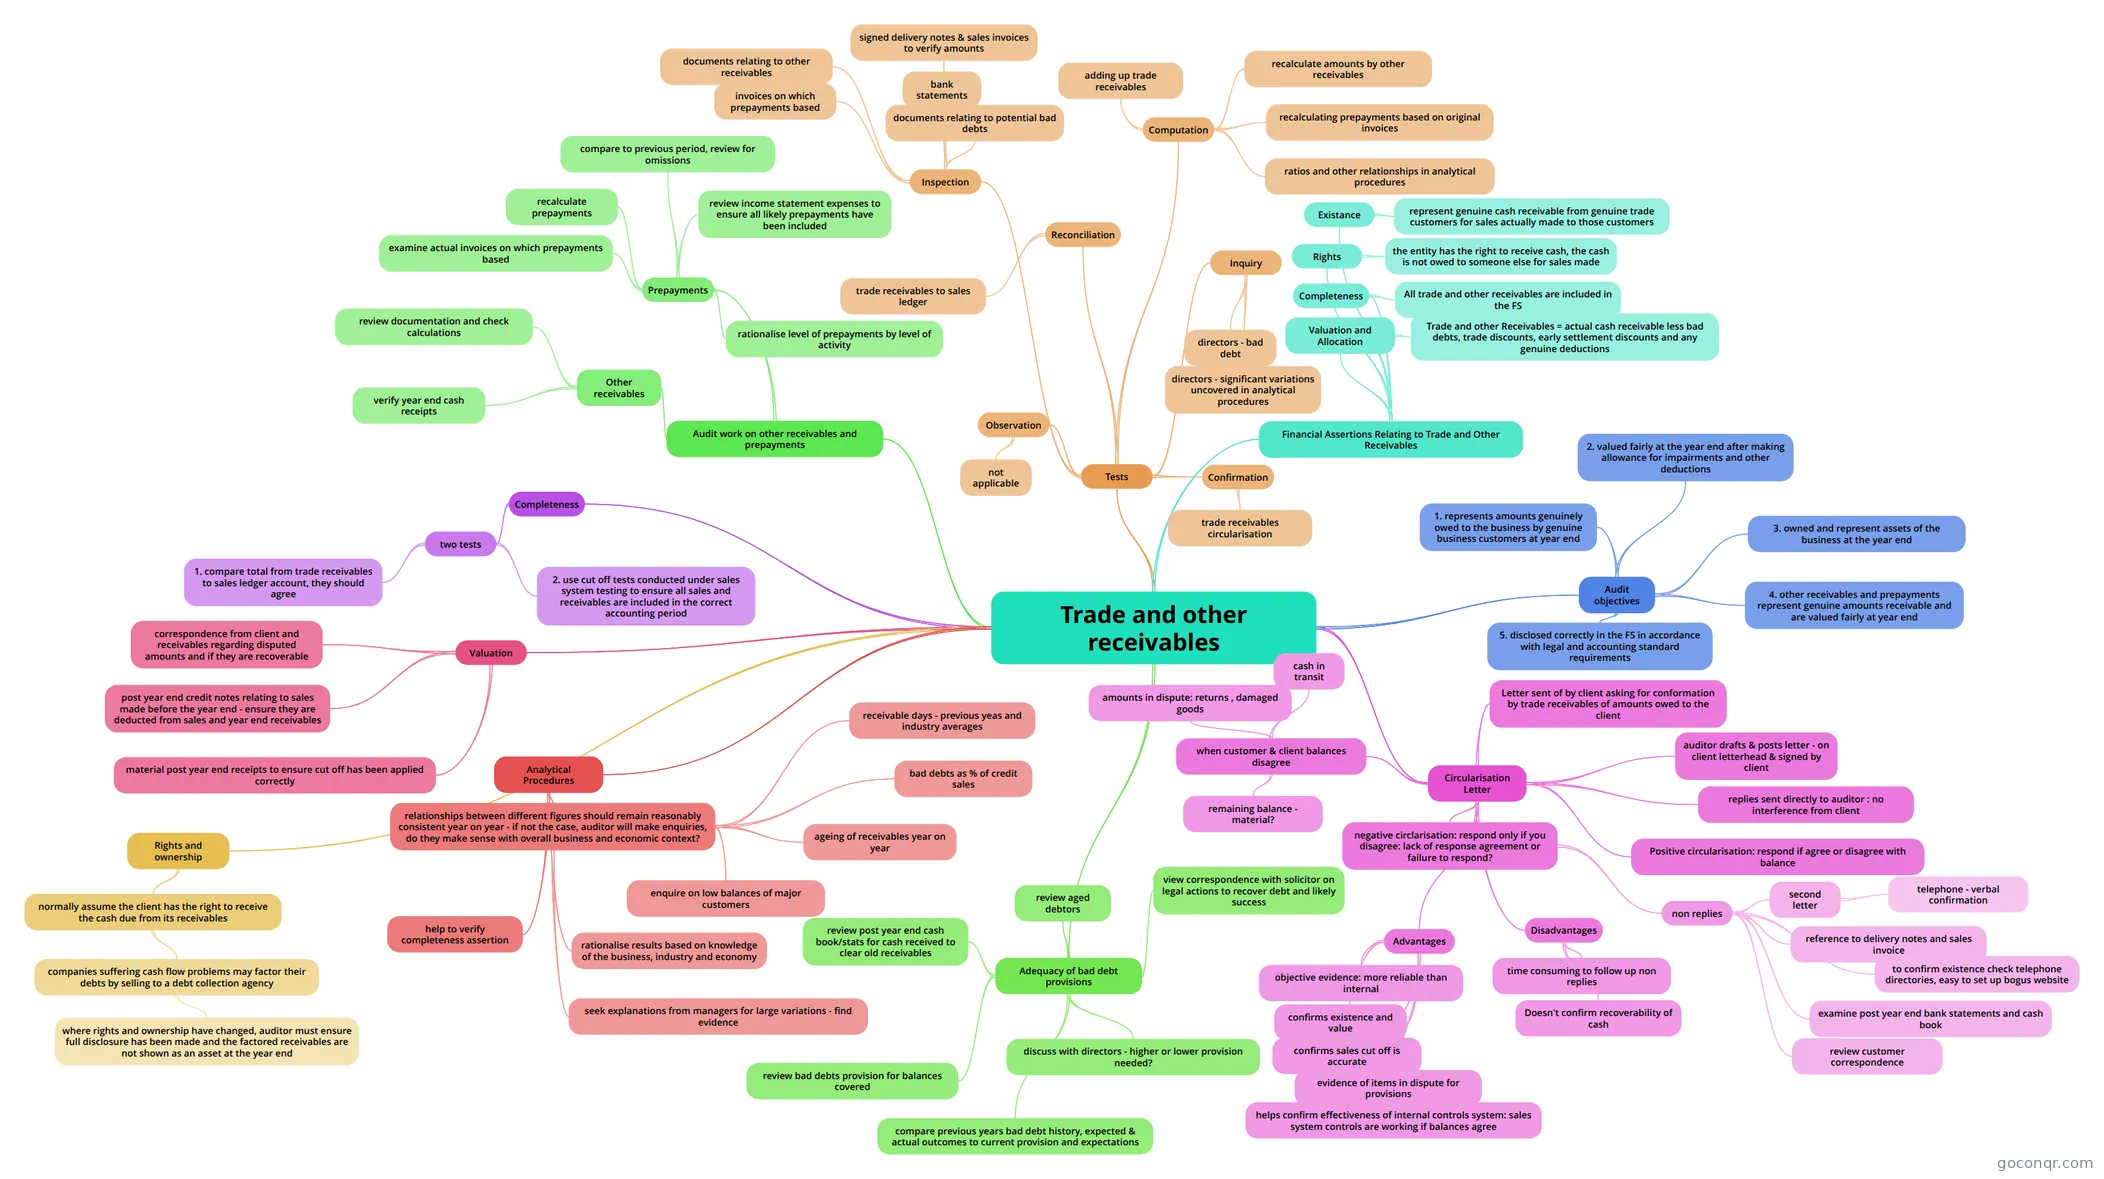
Mind map: Trade and other receivables audit
Contenido del mapa
Trade and other receivables
Financial Assertions Relating to Trade and Other Receivables
- Existance
- represent genuine cash receivable from genuine trade customers for sales actually made to those customers
- Rights
- the entity has the right to receive cash, the cash is not owed to someone else for sales made
- Completeness
- All trade and other receivables are included in the FS
- Valuation and Allocation
- Trade and other Receivables = actual cash receivable less bad debts, trade discounts, early settlement discounts and any genuine deductions
- Existance
Audit objectives
- 1. represents amounts genuinely owed to the business by genuine business customers at year end
- 2. valued fairly at the year end after making allowance for impairments and other deductions
- 3. owned and represent assets of the business at the year end
- 4. other receivables and prepayments represent genuine amounts receivable and are valued fairly at year end
- 5. disclosed correctly in the FS in accordance with legal and accounting standard requirements
Circularisation Letter
- Letter sent of by client asking for conformation by trade receivables of amounts owed to the client
- auditor drafts & posts letter - on client letterhead & signed by client
- replies sent directly to auditor : no interference from client
- Positive circularisation: respond if agree or disagree with balance
- negative circlarisation: respond only if you disagree: lack of response agreement or failure to respond?
- non replies
- second letter
- telephone - verbal confirmation
- reference to delivery notes and sales invoice
- to confirm existence check telephone directories, easy to set up bogus website
- examine post year end bank statements and cash book
- review customer correspondence
- second letter
- non replies
- Advantages
- objective evidence: more reliable than internal
- confirms existence and value
- confirms sales cut off is accurate
- evidence of items in dispute for provisions
- helps confirm effectiveness of internal controls system: sales system controls are working if balances agree
- Disadvantages
- time consuming to follow up non replies
- Doesn't confirm recoverability of cash
- when customer & client balances disagree
- cash in transit
- amounts in dispute: returns , damaged goods
- remaining balance - material?
Adequacy of bad debt provisions
- review aged debtors
- review post year end cash book/stats for cash received to clear old receivables
- review bad debts provision for balances covered
- discuss with directors - higher or lower provision needed?
- view correspondence with solicitor on legal actions to recover debt and likely success
- compare previous years bad debt history, expected & actual outcomes to current provision and expectations
Analytical Procedures
- relationships between different figures should remain reasonably consistent year on year - if not the case, auditor will make enquiries, do they make sense with overall business and economic context?
- receivable days - previous yeas and industry averages
- bad debts as % of credit sales
- ageing of receivables year on year
- enquire on low balances of major customers
- rationalise results based on knowledge of the business, industry and economy
- seek explanations from managers for large variations - find evidence
- help to verify completeness assertion
- relationships between different figures should remain reasonably consistent year on year - if not the case, auditor will make enquiries, do they make sense with overall business and economic context?
Rights and ownership
- normally assume the client has the right to receive the cash due from its receivables
- companies suffering cash flow problems may factor their debts by selling to a debt collection agency
- where rights and ownership have changed, auditor must ensure full disclosure has been made and the factored receivables are not shown as an asset at the year end
- companies suffering cash flow problems may factor their debts by selling to a debt collection agency
- normally assume the client has the right to receive the cash due from its receivables
Valuation
- post year end credit notes relating to sales made before the year end - ensure they are deducted from sales and year end receivables
- correspondence from client and receivables regarding disputed amounts and if they are recoverable
- material post year end receipts to ensure cut off has been applied correctly
Completeness
- two tests
- 1. compare total from trade receivables to sales ledger account, they should agree
- 2. use cut off tests conducted under sales system testing to ensure all sales and receivables are included in the correct accounting period
- two tests
Audit work on other receivables and prepayments
- Other receivables
- review documentation and check calculations
- verify year end cash receipts
- Prepayments
- examine actual invoices on which prepayments based
- recalculate prepayments
- compare to previous period, review for omissions
- review income statement expenses to ensure all likely prepayments have been included
- rationalise level of prepayments by level of activity
- Other receivables
Tests
- Observation
- not applicable
- Confirmation
- trade receivables circularisation
- Inspection
- invoices on which prepayments based
- documents relating to other receivables
- signed delivery notes & sales invoices to verify amounts
- bank statements
- documents relating to potential bad debts
- Computation
- adding up trade receivables
- recalculate amounts by other receivables
- recalculating prepayments based on original invoices
- ratios and other relationships in analytical procedures
- Reconciliation
- trade receivables to sales ledger
- Inquiry
- directors - bad debt
- directors - significant variations uncovered in analytical procedures
- Observation
Información
- Descripción
- Degree (Audit work) Audit & Assurance Mapa Mental sobre Trade and other receivables, creado por Sara Sefton el 13/04/2014.
- Creado por
- Sara Sefton
- Visitas
- 36
- Valoración