
Mind map
Art.110 Internal Taxation
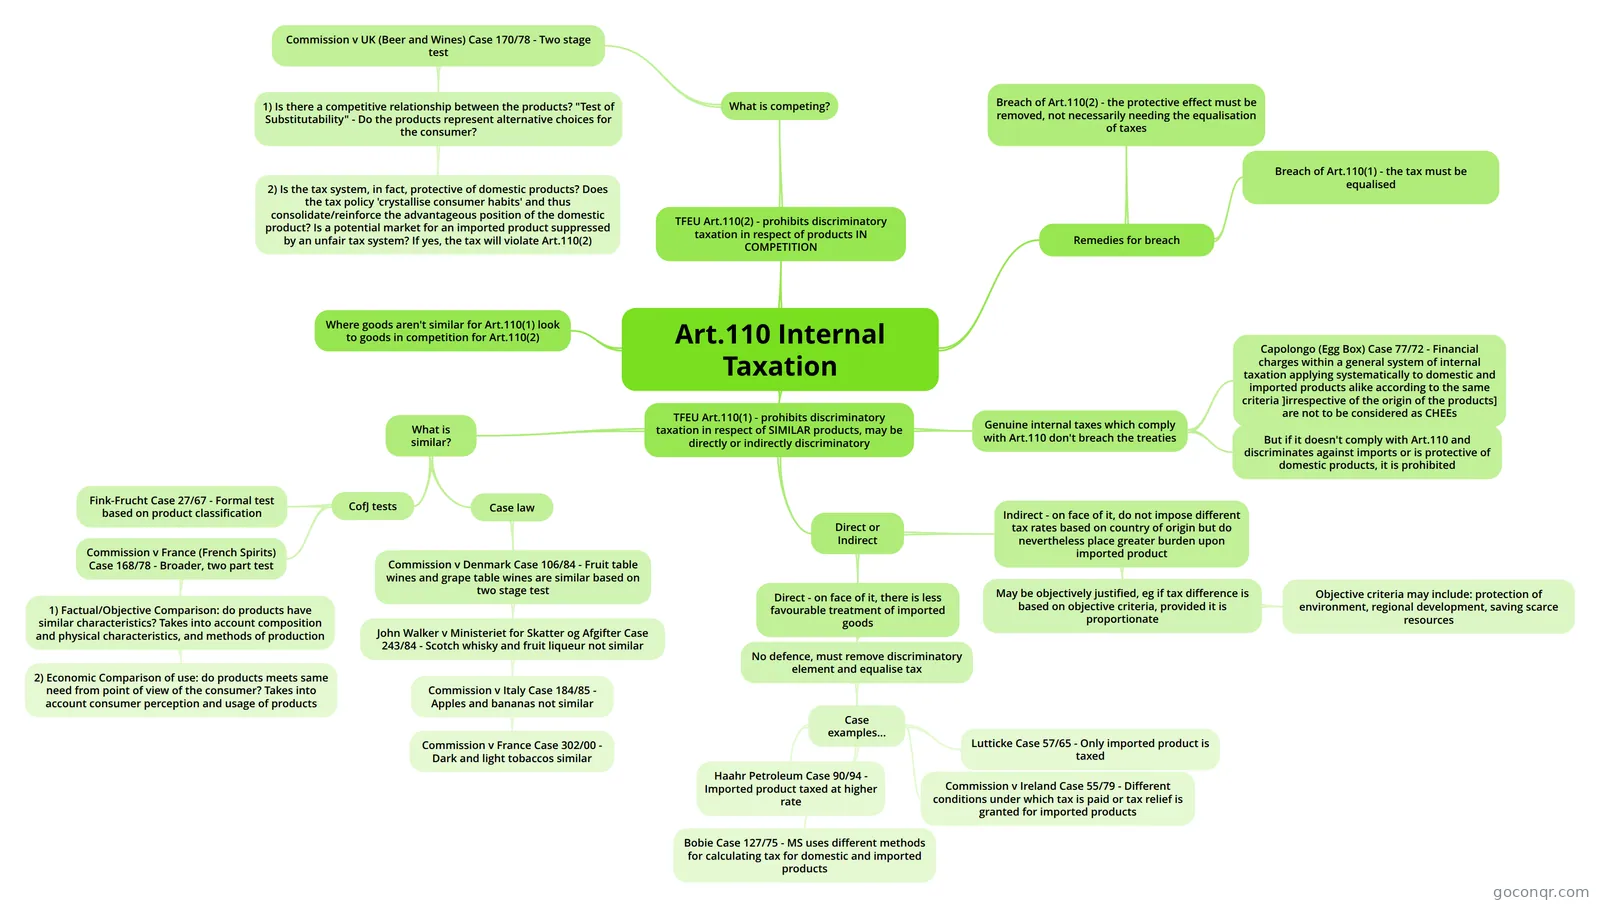
Mind map: TFEU Article 110 internal taxation
Map content
Art.110 Internal Taxation
TFEU Art.110(1) - prohibits discriminatory taxation in respect of SIMILAR products, may be directly or indirectly discriminatory
- Genuine internal taxes which comply with Art.110 don't breach the treaties
- Capolongo (Egg Box) Case 77/72 - Financial charges within a general system of internal taxation applying systematically to domestic and imported products alike according to the same criteria ]irrespective of the origin of the products] are not to be considered as CHEEs
- But if it doesn't comply with Art.110 and discriminates against imports or is protective of domestic products, it is prohibited
- What is similar?
- Case law
- Commission v Denmark Case 106/84 - Fruit table wines and grape table wines are similar based on two stage test
- John Walker v Ministeriet for Skatter og Afgifter Case 243/84 - Scotch whisky and fruit liqueur not similar
- Commission v Italy Case 184/85 - Apples and bananas not similar
- Commission v France Case 302/00 - Dark and light tobaccos similar
- Commission v Italy Case 184/85 - Apples and bananas not similar
- John Walker v Ministeriet for Skatter og Afgifter Case 243/84 - Scotch whisky and fruit liqueur not similar
- Commission v Denmark Case 106/84 - Fruit table wines and grape table wines are similar based on two stage test
- CofJ tests
- Fink-Frucht Case 27/67 - Formal test based on product classification
- Commission v France (French Spirits) Case 168/78 - Broader, two part test
- 1) Factual/Objective Comparison: do products have similar characteristics? Takes into account composition and physical characteristics, and methods of production
- 2) Economic Comparison of use: do products meets same need from point of view of the consumer? Takes into account consumer perception and usage of products
- 1) Factual/Objective Comparison: do products have similar characteristics? Takes into account composition and physical characteristics, and methods of production
- Case law
- Direct or Indirect
- Direct - on face of it, there is less favourable treatment of imported goods
- No defence, must remove discriminatory element and equalise tax
- Case examples...
- Lutticke Case 57/65 - Only imported product is taxed
- Haahr Petroleum Case 90/94 - Imported product taxed at higher rate
- Bobie Case 127/75 - MS uses different methods for calculating tax for domestic and imported products
- Commission v Ireland Case 55/79 - Different conditions under which tax is paid or tax relief is granted for imported products
- Case examples...
- No defence, must remove discriminatory element and equalise tax
- Indirect - on face of it, do not impose different tax rates based on country of origin but do nevertheless place greater burden upon imported product
- May be objectively justified, eg if tax difference is based on objective criteria, provided it is proportionate
- Objective criteria may include: protection of environment, regional development, saving scarce resources
- May be objectively justified, eg if tax difference is based on objective criteria, provided it is proportionate
- Direct - on face of it, there is less favourable treatment of imported goods
- Genuine internal taxes which comply with Art.110 don't breach the treaties
TFEU Art.110(2) - prohibits discriminatory taxation in respect of products IN COMPETITION
- What is competing?
- Commission v UK (Beer and Wines) Case 170/78 - Two stage test
- 1) Is there a competitive relationship between the products? "Test of Substitutability" - Do the products represent alternative choices for the consumer?
- 2) Is the tax system, in fact, protective of domestic products? Does the tax policy 'crystallise consumer habits' and thus consolidate/reinforce the advantageous position of the domestic product? Is a potential market for an imported product suppressed by an unfair tax system? If yes, the tax will violate Art.110(2)
- 1) Is there a competitive relationship between the products? "Test of Substitutability" - Do the products represent alternative choices for the consumer?
- Commission v UK (Beer and Wines) Case 170/78 - Two stage test
- What is competing?
Where goods aren't similar for Art.110(1) look to goods in competition for Art.110(2)
Remedies for breach
- Breach of Art.110(2) - the protective effect must be removed, not necessarily needing the equalisation of taxes
- Breach of Art.110(1) - the tax must be equalised
Information
- Description
- EU (Free Movement of Goods) Mind Map on Art.110 Internal Taxation, created by rhiannonfayemcdonald on 08/05/2013.
- Created by
- rhiannonfayemcdonald
- Views
- 716
- Tags
- Rating