
Notes
MIEC 3: Supply
Content of the notes (1)
Page 1
SUPPLY
Market equilibrium
Market disequilibrium
Forms of government intervention
Price Ceiling
Price Floor
Quantity supplied of a good
Amount which producers are able and willing to offer for sale in a given time period, at a particular price, ceteris paribus.
Supply
Entire range of quantities that producers are able and willing to offer for sale at different prices, in a given period of time, ceteris paribus.
Quantity supplied
At a particular point on the curve.
Supply
Refers to all the points on the supply curve, the entire supply curve.
Law of supply
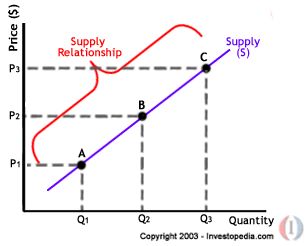
A direct relationship exists between price and quantity supplied of a good.
Price increases, quantity supplied of a good increases
Price decreases, quantity supplied of a good decreases.
Why direct relationship
Producers are more willing to sell greater amounts at higher price, because the good have become relatively more profitable to produce.
Higher price will help producers cover the higher opportunity cost.
Price changes
Movements along the supply curve. Quantity supplied changes.
Determinants of supply
Determinants
Factors other than the price which affects how much sellers are able and willing to sell a good
Constant
Shifts the entire curve (Quantity supplied changes at each and every price level)
Determinants
Factor/resource price
Technology
Price of related goods
Expectations of producers
Number of sellers in the market
Resource price
If higher costs or production were incurred. Less willing and able to sell at all price levels. (Shift left)
If higher costs or production, higher price may be charged at every output level. (Shift left)
Technology
Fewer resources are needed for production of a good
Leads to lower cost of production, at every price level suppliers are willing and able to sell more
Supply increases, (Shift right)
Or sellers are more able and willing to sell at lower price at every quantity (Shift right)
Price of related goods
Substitutes: Require same resource to produce E.g. rubber bands, rubber erasers
Complements: Jointly produced with same resources E.g. Beef and leather
Substitutes (Price increase of one rubber quantity supplied of rubber increases, not enough resources for rubber bands. Left shift)
Complements (Price increase, Quantity supplied of beef increases, increasing number of cows slaughtered, increase in supply of leather. Right shift)
Expectations of future profits
If sellers expect price to fall they will sell more now. (Shift right)
Number of sellers
If increase in number of sellers, supply increases (Shift right)
Changes in quantity supplied
Price
Movement along the curve
Changes in supply
Non-price determinants (Resource/factor price, Technology, Price of related goods, Expectations of future profits, Number of sellers)
Shift of supply curve
Supply (Factors of production)
Comes from households and are sold to business firms, to produce goods and services
Positively shaped
Exceptional supply curve
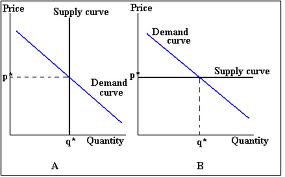
Vertical supply: Regardless of any price change, quantity supplied will not change.
Horizontal: At the existing price, the quantity supplied is infinite.
Market Equilibrium
What is equilibrium
A state in which opposing forces balance each other. No inherent tendency for change.
Market demand and market supply balance each other. No tendency for change.
Wishes of buyers and sellers match.
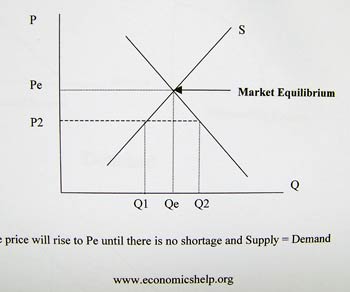
Quantity demanded equals quantity supplied.
Not in equilibrium
Shortage (Qd>Qs) / Surplus (Qs>Qd)
Surplus (Qs>Qd)
Occurs when quantity supplied exceeds quantity demanded.
Downward pressure on price as sellers are forced to reduce price.
As price decreases, buyers buy more sellers sell less, until equilibrium is attained.
Changes in Eqm Price & Qty
Once equilibrium is attained, there is no tendency to change, unless demand, supply or both market forces to change.
Demand and supply change if there is a change in non-price determinants.
SA
Shortage (Qd>Qs)
Occurs when quantity demanded exceeds quantity supplied.
Upward pressure on price as buyers increase price
As price increases, sellers sell more and buyers buy less, until equilibrium is attained.
If demand and supply increase simultaneously, equilibrium qty will definitely increase.
Equilibrium price will increase or decrease depends on. How much demand shifts relative to supply?
Market disequilibrium - Govt intervention
Govt step in to restrict the free operation of market. Price ceiling or price floor.
Price floor
A legally established minimum price above the market equilibrium.
Sales below price floor not permitted.
Imposed during a period of falling prices.
To ensure producers a higher and stable income
Ensure std of living
Price floor create surpluses govt intervention needed to prevent downward pressure on price. Buy the surplus. Distributed to poor, stored up wasteful if quality deteriorates over time.
Consumers pay a higher price than market eqm.
Consumers pay tax to cover govt support
Amount bought and sold with PF imposed is less than market eqm.
Price ceiling
A legally established maximum price below the market equilibrium.
Sales above price ceiling not permitted
Imposed during a period of rising prices.
Prevents consumers from being overcharged
Shortage: Caused by the price ceiling forces consumers to more time searching for an alternative. Lead to black market transactions.
Rent control leads to deteriorating quality of housing (Little incentive for landlords to maintain)
Amount bought and sold with a PC imposed is less than that at market eqm.
Supply
Determinants of supply
Market Equilibrium
Information
- Description
- International business MIEC Note on MIEC 3: Supply, created by pr2st on 30/11/2013.
- Created by
- pr2st · Nov 2013
- Updated
- Dec 12, 2016
- Views
- 124
- Tags
- Rating