
Mapa mental
Intangible Assets
Conteúdo do mapa
Intangible Assets
FRS 38
ASSETS
- Tangible Assets
- Have Physical Substance
- FRS 16
- Resource controlled by an enterprise that bring FEB
- Tangible Assets
Represent the rights & privileges that ownership brings
Identifiable Non-Monetary Asset w no physical substance
Recognition Citeria
- 3 Key Element
- Identifiable
- Separable from entity to be sold, transferred etc.
- Arise from contractual or legal rights
- Eg. Patent, Copyright
- Control
- Has power to obtain FEB
- Restrict access by others
- FEB
- Rev from sale, cost saving, benefits
- Identifiable
- Probable that FEB will flow to enterprise
- Using reasonable & supportable assumptions
- Cost can be measured reliably
- In monetary terms
- 3 Key Element
Internally Generated IA
- Research
- Expense Off
- Original & Planned Investigation
- Eg. Obtain NEW knowledge (Reserach)
- search for application of findings & alternatives
- formulation & design of possible alternatives for new or improves materials and others
- Development
- Application of research findings or other knowledge
- Prior to commencement of commercial production
- Eg. Pre- production Models
- Design new tools
- Design, construct, operate not on a scale feasible for commercial production
- testing of chosen alteratives
- Expense Off
- CAPITALIZED if meet 6 criterias
- Feasible to complete so can be sold
- Intend to complete it
- Able to Use or Sell it
- Generate FEB
- Enough Resources to complete
- Able to measure reliably the expediture
- Feasible to complete so can be sold
- CAPITALIZED if meet 6 criterias
- Research
Recognition Expense
- Expense Off
- Research
- Start-Up
- Training
- Advertising & Promotion
- Relocation/Reorganisation
- Expense Off
Measurement
- Initially at cost
- Expenditure on IA initially recognised as IA shall not be capitalized afterwards
- Subsequent
- Revaluation
- increase in value 10K, increase OCI (reserve)
- Subsequent Decrease of 20k
- Expense of 10k , reduce reserve 10k
- Subsequent Decrease of 20k
- decrease in value, expense off
- increase in value 10K, increase OCI (reserve)
- Cost Method
- Revaluation
- Initially at cost
Impairment Loss
- Carrying Amount > Recoverable Amount
- Recoverable Amount
- Higher of FV less cost to sell & Value in Use
- Recoverable Amount
- Carrying Amount > Recoverable Amount
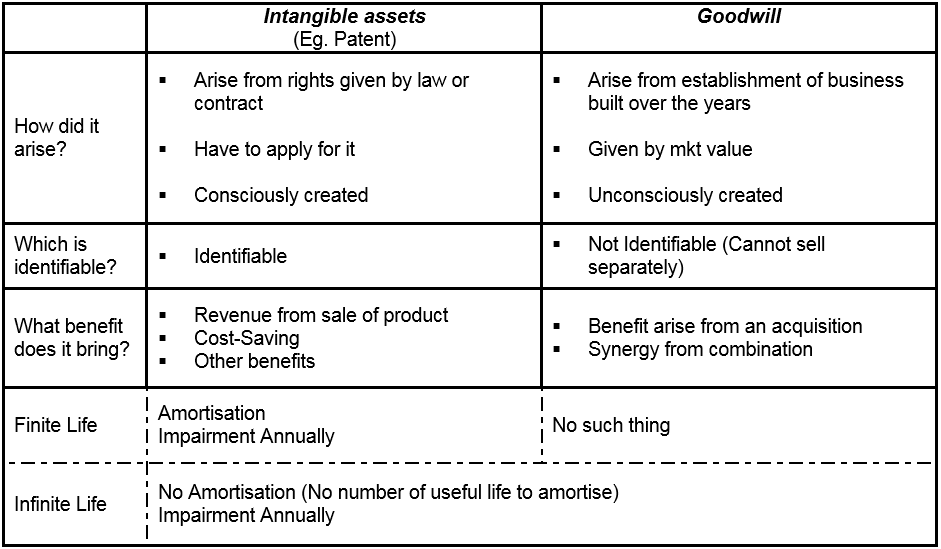
Intangible Assets Vs Goodwill
Amortisation / Imapirment
Imagens e arquivos do mapa
Informações
- Descrição
- Diploma AA Mapa Mental sobre Intangible Assets, criado por June Leong em 22-05-2015.
- Criado por
- June Leong
- Visualizações
- 4
- Avaliação