
Mapa mental
Financial Performance Measures
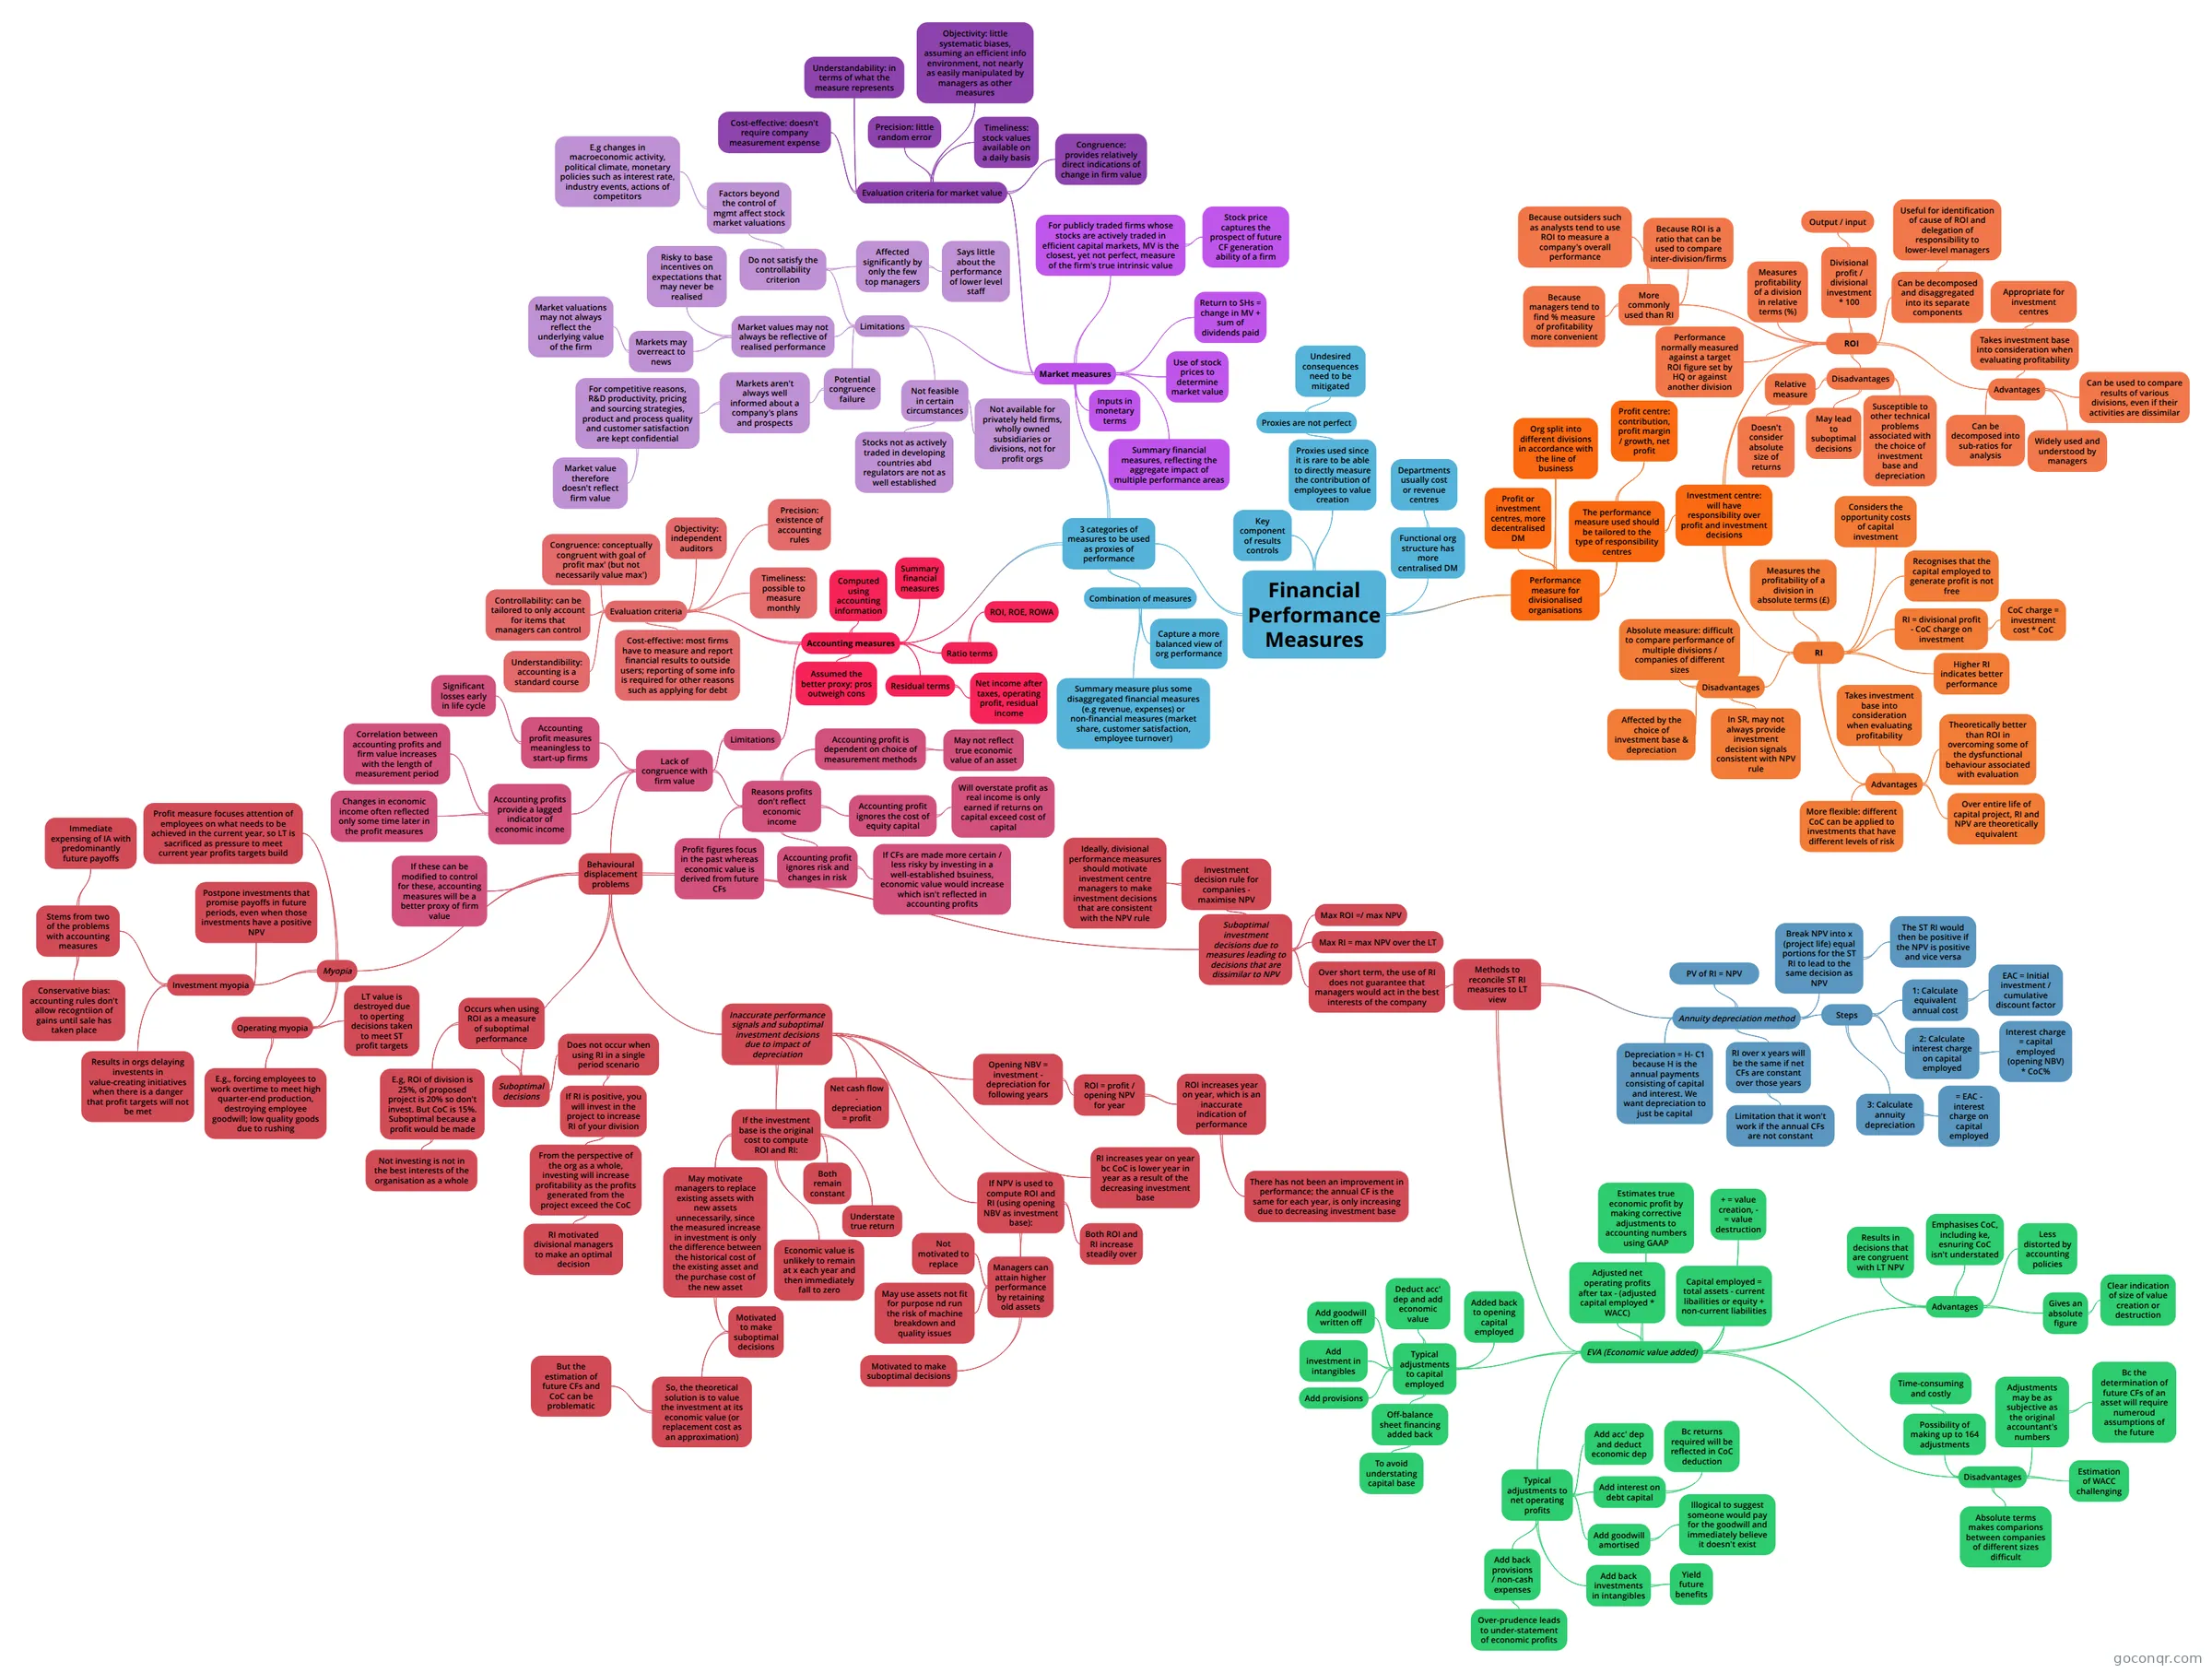
Mind map: Financial performance measures
Conteúdo do mapa
Financial Performance Measures
3 categories of measures to be used as proxies of performance
- Market measures
- Inputs in monetary terms
- Summary financial measures, reflecting the aggregate impact of multiple performance areas
- Use of stock prices to determine market value
- Return to SHs = change in MV + sum of dividends paid
- For publicly traded firms whose stocks are actively traded in efficient capital markets, MV is the closest, yet not perfect, measure of the firm's true intrinsic value
- Stock price captures the prospect of future CF generation ability of a firm
- Evaluation criteria for market value
- Congruence: provides relatively direct indications of change in firm value
- Timeliness: stock values available on a daily basis
- Precision: little random error
- Objectivity: little systematic biases, assuming an efficient info environment, not nearly as easily manipulated by managers as other measures
- Understandability: in terms of what the measure represents
- Cost-effective: doesn't require company measurement expense
- Limitations
- Do not satisfy the controllability criterion
- Affected significantly by only the few top managers
- Says little about the performance of lower level staff
- Factors beyond the control of mgmt affect stock market valuations
- E.g changes in macroeconomic activity, political climate, monetary policies such as interest rate, industry events, actions of competitors
- Affected significantly by only the few top managers
- Market values may not always be reflective of realised performance
- Risky to base incentives on expectations that may never be realised
- Markets may overreact to news
- Market valuations may not always reflect the underlying value of the firm
- Potential congruence failure
- Markets aren't always well informed about a company's plans and prospects
- For competitive reasons, R&D productivity, pricing and sourcing strategies, product and process quality and customer satisfaction are kept confidential
- Market value therefore doesn't reflect firm value
- For competitive reasons, R&D productivity, pricing and sourcing strategies, product and process quality and customer satisfaction are kept confidential
- Markets aren't always well informed about a company's plans and prospects
- Not feasible in certain circumstances
- Not available for privately held firms, wholly owned subsidiaries or divisions, not for profit orgs
- Stocks not as actively traded in developing countries abd regulators are not as well established
- Do not satisfy the controllability criterion
- Accounting measures
- Summary financial measures
- Computed using accounting information
- Residual terms
- Net income after taxes, operating profit, residual income
- Ratio terms
- ROI, ROE, ROWA
- Evaluation criteria
- Timeliness: possible to measure monthly
- Precision: existence of accounting rules
- Objectivity: independent auditors
- Congruence: conceptually congruent with goal of profit max' (but not necessarily value max')
- Controllability: can be tailored to only account for items that managers can control
- Understandibility: accounting is a standard course
- Cost-effective: most firms have to measure and report financial results to outside users; reporting of some info is required for other reasons such as applying for debt
- Limitations
- Lack of congruence with firm value
- Accounting profit measures meaningless to start-up firms
- Significant losses early in life cycle
- Accounting profits provide a lagged indicator of economic income
- Correlation between accounting profits and firm value increases with the length of measurement period
- Changes in economic income often reflected only some time later in the profit measures
- Behavioural displacement problems
- Myopia
- Profit measure focuses attention of employees on what needs to be achieved in the current year, so LT is sacrificed as pressure to meet current year profits targets build
- Investment myopia
- Postpone investments that promise payoffs in future periods, even when those investments have a positive NPV
- Stems from two of the problems with accounting measures
- Conservative bias: accounting rules don't allow recogntiion of gains until sale has taken place
- Immediate expensing of IA with predominantly future payoffs
- Results in orgs delaying investents in value-creating initiatives when there is a danger that profit targets will not be met
- Operating myopia
- LT value is destroyed due to operting decisions taken to meet ST profit targets
- E.g., forcing employees to work overtime to meet high quarter-end production, destroying employee goodwill; low quality goods due to rushing
- Suboptimal decisions
- Occurs when using ROI as a measure of suboptimal performance
- E.g, ROI of division is 25%, of proposed project is 20% so don't invest. But CoC is 15%. Suboptimal because a profit would be made
- Not investing is not in the best interests of the organisation as a whole
- E.g, ROI of division is 25%, of proposed project is 20% so don't invest. But CoC is 15%. Suboptimal because a profit would be made
- Does not occur when using RI in a single period scenario
- If RI is positive, you will invest in the project to increase RI of your division
- From the perspective of the org as a whole, investing will increase profitability as the profits generated from the project exceed the CoC
- RI motivated divisional managers to make an optimal decision
- From the perspective of the org as a whole, investing will increase profitability as the profits generated from the project exceed the CoC
- If RI is positive, you will invest in the project to increase RI of your division
- Occurs when using ROI as a measure of suboptimal performance
- If these can be modified to control for these, accounting measures will be a better proxy of firm value
- Inaccurate performance signals and suboptimal investment decisions due to impact of depreciation
- Net cash flow - depreciation = profit
- Opening NBV = investment - depreciation for following years
- ROI = profit / opening NPV for year
- ROI increases year on year, which is an inaccurate indication of performance
- There has not been an improvement in performance; the annual CF is the same for each year, is only increasing due to decreasing investment base
- ROI increases year on year, which is an inaccurate indication of performance
- ROI = profit / opening NPV for year
- RI increases year on year bc CoC is lower year in year as a result of the decreasing investment base
- If NPV is used to compute ROI and RI (using opening NBV as investment base):
- Both ROI and RI increase steadily over
- Managers can attain higher performance by retaining old assets
- Not motivated to replace
- May use assets not fit for purpose nd run the risk of machine breakdown and quality issues
- Motivated to make suboptimal decisions
- If the investment base is the original cost to compute ROI and RI:
- Both remain constant
- Understate true return
- Economic value is unlikely to remain at x each year and then immediately fall to zero
- May motivate managers to replace existing assets with new assets unnecessarily, since the measured increase in investment is only the difference between the historical cost of the existing asset and the purchase cost of the new asset
- Motivated to make suboptimal decisions
- So, the theoretical solution is to value the investment at its economic value (or replacement cost as an approximation)
- But the estimation of future CFs and CoC can be problematic
- So, the theoretical solution is to value the investment at its economic value (or replacement cost as an approximation)
- Motivated to make suboptimal decisions
- Suboptimal investment decisions due to measures leading to decisions that are dissimilar to NPV
- Investment decision rule for companies - maximise NPV
- Ideally, divisional performance measures should motivate investment centre managers to make investment decisions that are consistent with the NPV rule
- Max ROI =/ max NPV
- Max RI = max NPV over the LT
- Over short term, the use of RI does not guarantee that managers would act in the best interests of the company
- Methods to reconcile ST RI measures to LT view
- Annuity depreciation method
- PV of RI = NPV
- Break NPV into x (project life) equal portions for the ST RI to lead to the same decision as NPV
- The ST RI would then be positive if the NPV is positive and vice versa
- Steps
- 1: Calculate equivalent annual cost
- EAC = Initial investment / cumulative discount factor
- 2: Calculate interest charge on capital employed
- Interest charge = capital employed (opening NBV) * CoC%
- 3: Calculate annuity depreciation
- = EAC - interest charge on capital employed
- 1: Calculate equivalent annual cost
- Depreciation = H- C1 because H is the annual payments consisting of capital and interest. We want depreciation to just be capital
- RI over x years will be the same if net CFs are constant over those years
- Limitation that it won't work if the annual CFs are not constant
- EVA (Economic value added)
- Adjusted net operating profits after tax - (adjusted capital employed * WACC)
- Capital employed = total assets - current libailities or equity + non-current liabilities
- + = value creation, - = value destruction
- Estimates true economic profit by making corrective adjustments to accounting numbers using GAAP
- Typical adjustments to net operating profits
- Add acc' dep and deduct economic dep
- Add interest on debt capital
- Bc returns required will be reflected in CoC deduction
- Add goodwill amortised
- Illogical to suggest someone would pay for the goodwill and immediately believe it doesn't exist
- Add back investments in intangibles
- Yield future benefits
- Add back provisions / non-cash expenses
- Over-prudence leads to under-statement of economic profits
- Typical adjustments to capital employed
- Added back to opening capital employed
- Deduct acc' dep and add economic value
- Add goodwill written off
- Add investment in intangibles
- Add provisions
- Off-balance sheet financing added back
- To avoid understating capital base
- Advantages
- Results in decisions that are congruent with LT NPV
- Emphasises CoC, including ke, esnuring CoC isn't understated
- Less distorted by accounting policies
- Gives an absolute figure
- Clear indication of size of value creation or destruction
- Disadvantages
- Possibility of making up to 164 adjustments
- Time-consuming and costly
- Adjustments may be as subjective as the original accountant's numbers
- Bc the determination of future CFs of an asset will require numeroud assumptions of the future
- Estimation of WACC challenging
- Absolute terms makes comparions between companies of different sizes difficult
- Possibility of making up to 164 adjustments
- Annuity depreciation method
- Methods to reconcile ST RI measures to LT view
- Investment decision rule for companies - maximise NPV
- Myopia
- Reasons profits don't reflect economic income
- Accounting profit is dependent on choice of measurement methods
- May not reflect true economic value of an asset
- Accounting profit ignores the cost of equity capital
- Will overstate profit as real income is only earned if returns on capital exceed cost of capital
- Accounting profit ignores risk and changes in risk
- If CFs are made more certain / less risky by investing in a well-established bsuiness, economic value would increase which isn't reflected in accounting profits
- Profit figures focus in the past whereas economic value is derived from future CFs
- Accounting profit is dependent on choice of measurement methods
- Accounting profit measures meaningless to start-up firms
- Lack of congruence with firm value
- Assumed the better proxy; pros outweigh cons
- Combination of measures
- Capture a more balanced view of org performance
- Summary measure plus some disaggregated financial measures (e.g revenue, expenses) or non-financial measures (market share, customer satisfaction, employee turnover)
- Market measures
Key component of results controls
Proxies used since it is rare to be able to directly measure the contribution of employees to value creation
- Proxies are not perfect
- Undesired consequences need to be mitigated
- Proxies are not perfect
Performance measure for divisionalised organisations
- Profit or investment centres, more decentralised DM
- Org split into different divisions in accordance with the line of business
- The performance measure used should be tailored to the type of responsibility centres
- Profit centre: contribution, profit margin / growth, net profit
- Investment centre: will have responsibility over profit and investment decisions
- ROI
- Measures profitability of a division in relative terms (%)
- Divisional profit / divisional investment * 100
- Output / input
- Performance normally measured against a target ROI figure set by HQ or against another division
- Can be decomposed and disaggregated into its separate components
- Useful for identification of cause of ROI and delegation of responsibility to lower-level managers
- Advantages
- Takes investment base into consideration when evaluating profitability
- Appropriate for investment centres
- Can be used to compare results of various divisions, even if their activities are dissimilar
- Widely used and understood by managers
- Can be decomposed into sub-ratios for analysis
- Takes investment base into consideration when evaluating profitability
- Disadvantages
- Relative measure
- Doesn't consider absolute size of returns
- May lead to suboptimal decisions
- Susceptible to other technical problems associated with the choice of investment base and depreciation
- Relative measure
- More commonly used than RI
- Because ROI is a ratio that can be used to compare inter-division/firms
- Because outsiders such as analysts tend to use ROI to measure a company's overall performance
- Because managers tend to find % measure of profitability more convenient
- RI
- Measures the profitability of a division in absolute terms (£)
- Considers the opportunity costs of capital investment
- Recognises that the capital employed to generate profit is not free
- RI = divisional profit - CoC charge on investment
- CoC charge = investment cost * CoC
- Higher RI indicates better performance
- Advantages
- Takes investment base into consideration when evaluating profitability
- Theoretically better than ROI in overcoming some of the dysfunctional behaviour associated with evaluation
- Over entire life of capital project, RI and NPV are theoretically equivalent
- More flexible: different CoC can be applied to investments that have different levels of risk
- Disadvantages
- Absolute measure: difficult to compare performance of multiple divisions / companies of different sizes
- Affected by the choice of investment base & depreciation
- In SR, may not always provide investment decision signals consistent with NPV rule
- ROI
Functional org structure has more centralised DM
- Departments usually cost or revenue centres
Informações
- Descrição
- Mapa Mental sobre Financial Performance Measures, criado por Abbie Goffin em 01-01-2023.
- Criado por
- Abbie Goffin
- Visualizações
- 0
- Avaliação