
Quiz
Intermediate Accounting (Chapter 4)
Create a free account to finish this quiz
Save your progress and see your final score.
Already have an account? Sign in
Questions in this quiz (115)
1The Income statement is .....
- Aoften called the statement of earnings
- Bthe report that measures the success of a company's operations for a given period of time.
- Cinflows or other enhancements of assets of an entity or settlements of its liability during a period for delivering or producing goods and services or other activities that constitutes the entity's ongoing and major operations
2The business and investment community uses the income statement to
determine profitability, investment value, and creditworthiness- ATrue
- BFalse
3The income statement provides investors and creditors with information that helps them predict the ...
- Aamounts
- Btiming
- Cand uncertainty of future cash flows
- Drecurring items are more certain in the future
4Which of the following is an example of a usefulness of the income statement
- Aanalysts use the income data provided by Ford to compare its
performance to that of Toyota - Bhelps assess the risk of uncertainty of achieving future cash flows
- Cprovides a basis for predicting future performances
- Devaluate the past performance of the company
- Aanalysts use the income data provided by Ford to compare its
5match the usefulness of the income statement with the following statement
- AProvide a basis for predicting future performance.
- Binvestors and creditors often segregate IBM’s operating performance from other non-recurring sources of income because IBM primarily generates revenues and cash through its
operations. Thus, results from continuing operations usually have greater
significance for predicting future performance than do results from non-recurring
activities and events - CGeneral Electric at one time reported consistent increases in revenues. Obviously, past success does not necessarily translate into future success. However, analysts can better predict future revenues, and hence earnings and cash flows, if a reasonable correlation exists between past and future performance
- DHelp assess the risk or uncertainty of achieving future cash flows
6match the following usefulness of income statements:
- Ainvestors and
creditors often segregate IBM’s operating performance from other non-recurring
sources of income because IBM primarily generates revenues and cash through its
operations. Thus, results from continuing operations usually have greater
signifi cance for predicting future performance than do results from non-recurring
activities and events. - BInformation on
the various components of income—revenues, expenses, gains, and losses—
highlights the relationships among them. It also helps to assess the risk of not
achieving a particular level of cash fl ows in the future - CHelp assess the risk or uncertainty of achieving future cash flows
- DProvide a basis for predicting future performance
- Ainvestors and
7information from the income statement uses ...
- Arevenues, expenses, gains and losses to help users evaluate past performances
- Btrue
- Cfalse
8some limitations involved with using the income statement ....
- Ait is unreliable
- Bit reflects a number of assumptions
- Ccompanies omit information when that they cannot measure the reliability of an item
9Some examples of why an item will be left out of the income statement is because...
- Asome items are uncertain
- Ba company may not record unrealized gains and
losses on certain investment securities in income when there is uncertainty that it will ever realize the changes in value
10a company may not include realized gains and losses on certain investment securities when there is an uncertainty that the value of these investments will ever be realized
- ATrue
- BFalse
11another limitation of the income statement is that ....
- Aa company that reports thier income statement using the accelerated method to depreciate plant assets will normally have a lower income
- Bincome numbers are affected by the accounting method employed. One example of this would be when a company decides to use a straight line method and another company decides to use the accelerated method to depreciate plant assets
12another limit to income statements is that ...
- Aincome measurements require good judgement
- Bthese limitations affect predicting information for the amounts, timing, and uncertainty of future cash flows
13Earnings management is the planned timing of revenues, expenses, gains and losses to smooth out bumps in earnings.
- ATrue
- BFalse
14companies establish reserves by using unrealistic assumptions to estimate liabilities such as:
loan losses
reconstructing charges
warranty items- ATrue
- BFalse
15earnings management negatively affects:
- AInvestors or others losing faith in the numbers reported in the financial statements
will damage U.S. capital markets - Bquality of earnings
- AInvestors or others losing faith in the numbers reported in the financial statements
16the central element of the financial reporting in income statements are:
- Atiming, uncertainty of cash flows, assessing the amount of funds
- Bnone of the above
17net income results from
- Arevenues
- Bexpenses
- Cgains
- Dloss transactions
- Enone of the above
18true or false. when the income statement uses revenues, gains, expense and loss transaction to summarize an income statement this approach is called THE TRANSACTION APPORACH
- ATrue
- BFalse
19Income statements can be categorized as
- ACustomer
- BProduct Line
- CFunction
- DOperating
- ENon Operating
- FContinuing
- GDiscontinued
- HRegular and Non recurring items
- IAll of the above are major elements of a income statement
- Jnone of the above are major elements of an income statement
20Some of the Major Elements on the Income Statement are:
- ARevenues
- BExpenses
- CGains
- DLosses
21Match the following income statement elements to its definition
- Arevenue
- BInflows or other enhancements of assets of an entity or settlements of its liabilities
during a period from delivering or producing goods, rendering services, or other
activities that constitute the entity’s ongoing major or central operations. - Closses
- DIncreases in equity (net assets) from peripheral or incidental transactions of an
entity except those that result from revenues or investments by owners.
22Match the following income statement elements to its definition
- Aexpenses
- Bgains
- COutflows or other using-up of assets or incurrences of liabilities during a
period from delivering or producing goods, rendering services, or carrying out other activities that constitute the entity’s ongoing major or central operations - DDecreases in equity (net assets) from peripheral or incidental transactions of an
entity except those that result from expenses or distributions to owners
23Match the following income statement elements to its definition
- Agains
- BIncreases in equity (net assets) from peripheral or incidental transactions of an
entity except those that result from revenues or investments by owners - CDecreases in equity (net assets) from peripheral or incidental transactions of an
entity except those that result from expenses or distributions to owners
24Match the following income statement elements to its definition
- Alosses
- BIncreases in equity (net assets) from peripheral or incidental transactions of an
entity except those that result from revenues or investments by owners - CDecreases in equity (net assets) from peripheral or incidental transactions of an
entity except those that result from expenses or distributions to owners
25List some of the forms that revenue takes
- Asales, fees, interest, LIST THE OTHER 2
- BLIST THE OTHER 2
26EXPENSES TAKE THE FORM OF
- ACOST OF GOODS SOLD, DEPRECIATION, INTEREST (LIST THE OTHER 3)
- B(LIST THE OTHER 3)
27GAINS AND LOSSES ALSO RESULT FROM MANY ITEMS SELECT FROM THE FOLLOWING WHICH ARE GAINS:
- ASALE OF INVESTMENT PLANT AND PROPERTY
- BSETTLEMENT OF LIABILITIES
- CWRITE OFF OF ASSETS DUE TO IMPAIRMENT AND CASUALTY
28The distinction between revenues and gains, and between expenses and losses,
depend to a great extent on the typical activities of the company.- ATrue
- BFalse
29 investors and creditors are interested in predicting the amounts, timing, and uncertainty of future income and cash flows
- ATrue
- BFalse
30The term “non-recurring” encompasses transactions and other events that are derived from developments
outside the normal operations of the business- ATrue
- BFalse
31The income statement consist of 6 sections they are: (list in order)
- Aoperating section, non operating section, income tax, discontinued operations, non-controlling interest and earnings per share
- Bsales/revenue, cost of goods sold, selling expenses, administrative or general expenses
32The OPERATING SECTION of the income statement consists of
- Aother revenues and gains; other expenses and losses
- Bsales/revenue, cost of goods sold, selling expenses, administrative and general expenses
33what are sales returns and allowances?
- Asales revenues are always subtracted from sales returns and allowances and sales discounts
- BA contra revenue account that reports 1) merchandise returned by a customer, and 2) the allowances granted to a customer because the seller shipped improper or defective merchandise.
34The income statement organizes the income statement showing that ....
- Aoperating and non-operating expenses are separate. and it matches costs and expenses with related revenues
- Bhighlights intermediate features of the income statement that are used to compute ratios for the assessment of a companies performance
35inventing a intermediate income statement
- Ahelps readers evaluate earnings information in assessing the amounts, timing and uncertainty of future cash flows.
- Bbefore arriving at net income the following is shown: gross profit, income from operations, income before income tax and net income
36List the headings of the income statement in order: (choose the list below)
- ASales, Cost of goods, gross profit, operating expenses (below operating expenses are selling expenses); administrative expenses, income from operations, other revenues and gains, other expenses and losses, net income for the year
- Bsales, cost of goods sold, administrative expenses, other revenues and gains, other expenses and losses
37stating other revenues from revenues has the following benefit:
- Aanalysts can more easily understand and assess trends in revenue from continuing operations.
- Bgross profit is used to determine how successfully a company uses its resources.
38Select the following ways in which a company may measure the success of a company
- Ausing gross profit
- Blooking at how other revenues and gains are separated from the revenues (operating revenues) in the sales account
- Ccompanies may also use gross profit to understand how competitive pressure affected profit margins.
39A single income statement cannot possibly present all the desired expense details so to solve this a company includes only the total expenses groups in the statement of income. it then also prepares supplementary schedules to support the totals. this is called a comparative income statement
- ATrue
- BFalse
40the single step income statement consists of two groupings: revenues and expenses.
- ATrue
- BFalse
41the reason why single step income statement has its name is to show that expenses are deducted from revenues to arrive at net income or loss.
- ATrue
- BFalse
42one reason why single step income statement is used by companies is for its simplicity it contains the absence of any implication that one type of revenue or expense item has priority over another.
- ATrue
- BFalse
43companies usually have flexibility in the presentation of the items in the income statement however, FASB developed specific guidelines in two important areas list these two important areas:
- Awhat to include in income/
- Bhow to report certain unusual or infrequent items/
- Cfasb has complete control over every item in the companies income statement
44what should be reported in net income and where it should be reported is controversial
- ATrue
- BFalse
45To reduce the risk of lack of detail or false advertisement for promotional purposes in a business companies adapt a "MODIFIED ALL-INCLUSIVE CONCEPT" In this approach:
- A1. Unusual and infrequent gains and losses
2. Discontinued operations
3. Non-controlling interest
4. Earnings per share - Bcompanies report most items, including unusual or infrequent ones, as part of net income. These income items are listed in 4 different categories to better determining the long-run earning power of the company. This is done to decrease net income manipulation measures.
- A1. Unusual and infrequent gains and losses
46under each subheading unusual and infrequent gains and losses
- Acompanies that have usual or infrequent gains and losses or both are required to disclose this information int he income statement or in the notes to the financial statements.
- Bconsists of unusual and infrequency of occurrence
47To review a companies long-term earning power the modified all inclusive approach is used which states that a company MUST include all unusual/infrequent items as part of the net income, these sections include:
- Aunusual and infrequent gains and losses (which is subsectioned into unusual and infrequency of occurance)
- Bdiscontinued operations
- Cnon controlling interest
- Dearnings per share
- Eall of the above
- Fnone of the above
48companies that have unusual or infrequent gains and losses are required to state this on the income statement or on the financial statements.
- ATrue
- BFalse
49Some examples of unusual/infrequent gains and losses are:
- Alosses on write-down (impairment) of receivables, inventories, PPE, goodwill and other intangible assets
- Brestructuring chargers
- Cother gains and losses from sale or the abandonment of PPE
- Deffects of a strike including those against major competitors and suppliers
- Egains and losses on redemption of debt obligations, gains and losses on related casualties )fires, floods, earthquakes) gains and losses on sale of investment securities
50select the two most commons types of unsual gains and losses
- Arestructuring charges
- Bthere are none
- Cwrite-down, gains/losses on asset sales
51discontinues operations occurs when 2 things happen:
- Awhen a company eliminates the results of operations of a component of the business
- Bthe elimination of a competent that represents a strategic shift having a major effect on the company's operations and financial results.
52A strategic shift generally includes the disposal of (1)a major line of business (2) a major geographical area, (3) a major equity method investment
- ATrue
- BFalse
53companies report discontinued operations the gain or loss from "DISPOSAL OF A COMPONENT OF A BUSINESS". In addition companies report the RESULTS OF OPERATIONS OF A COMPONENT THAT HAS BEEN OR WILL BE DISPOSED OF seperatly from continuing operations.
- ATrue
- BFalse
54a company that reports a discontinued operation must report on the face of the income statement the per share effect of income from continuing operations and net income
- ATrue
- BFalse
55per share information is listed underneath NET INCOME. per share information has EPS information from "INCOME FROM CONTINUING OPERATIONS; INCOME FROM OPERATIONS DISCONTINUED DIVISION (NET OF TAX); LOSS ON DISPOSAL OF DISCONTINUED OPERATION (NET OF TAX); NET INCOME
- ATrue
- BFalse
56intraperiod tax allocation relates the income tax expense of the fiscal period to the specific items that give rise to the amount of the income tax. Sometimes the income tax expense is referred to as
- Athe income tax provision
- Bincome from continuing operations
57intraperiod tax allocation helps financial statement users better understand the impact of income taxes on the various components of net income. for example, it helps readers better estimate how much income tax expenses relates to income from continuing operations and how much to discontinues operations. Select another advantage of using intraperiod tax allocations
- Ait helps users predict the amount, timing, and uncertainty of future cash flows.
- Bit also helps the discourage statment readers from using pretax measures of performance when evaluating financial results and therby recognizing that income tax expense is a real cost
58companies like coke own substantial interests in other companies, It generally consolidates the financial results of these companies of into its own financial statements. In these cases, Coke is considered a parent company and the other companies are referred to as
- Asubsidiaries
- Bparent companies
59noncontrolling intrest amounts are not an expense or dividend but they are allocations of net income (loss) to the noncontrolling intrest
- ATrue
- BFalse
60noncontrolling interest is the portion of equity (net assets) interest in a subsidiary not attributable to the parent company.
- ATrue
- BFalse
61when a company prepares a consolidated income statement, GAAP requires that net income be allocated to the controlling and non controlling interest. this allocations is reported at the bottom of the income statement, after net income
- ATrue
- BFalse
62what is the earnings per share usual calculation?
- AE.P.S= net income (-) preferred dividends (income available to common stockholders),/ weighted average of common shares outstanding
- BE.P.S: income from operations+interest income - income taxes
63select which of the following uses net income per share/earnings per share ratio
- Aprospectuses
- Bproxy material
- Cannual reports to stockholders
- Dnone of the above
- Eall of the above
64a company that reports a discontinued operation must report per share amounts for line item either on the face of the income statement or on the notes to the financial statement
- ATrue
- BFalse
65at times businesses would have simple common stock as their capital structures. for these companies a presentation such as earnings per common share is appropriate on the income statement. in many instances, however,companies earnings per share are subject to being reduced in the future because future allowances permit the issuance of additional common stock
- ATrue
- BFalse
66some examples of an unusual or infrequent gain or loss are:
- Awrite downs of receivables, inventories, Property and intangibles, restructurings gains or losses from sales of assets used in business
- Bnet income (loss) attributable to non-controlling shareholders
- Cnet income minus preferred dividends divided by weighted-average shares outstanding
67discontinued operations occur when:
- Aelimination of the results of operations of a component of the business with cash flows that can be clearly distinguished and for which the elimination represents a strategic shift.
- Ballocation of net income or loss divided between two classes: (1) the majority interest represented by the shareholders who own the controlling interest and (2) non controlling interest (often referred to as the minority interest)
68select which of the following is best represented by its correspondent: sales by diversified company major division that represents only activities in electronics industry.
food distributor that sells wholesale to supermarket chains and through fast-food restaurants decides to discontinue the division that sells to one of two classes of customers- Aunusual or infrequent gain or loss
- Bdiscontinued operation
- Cnoncontrolling interest
69non controlling interest is reported below the net income or loss as an allocation of the net income or loss. One example of a non-controlling interest is a:
- Awrite downs of receivables, inventories, property, intangibles, restructurings, gains or losses from sales of assets used in business
- Bnet income (loss) attributable to non-controlling shareholders
70E.P.S is reported on the face of the income statement, E.P.S is calculated: net income minus preferred dividends divided by weighted average shares outstanding;report separate E.P.S for income from continuing operations (if applicable) and net income.
- ATrue
- BFalse
71On the income statement under the operating section the following are listed:
Sales or revenue
Cost of goods sold
Selling expense
Administrative or General Expenses
For the Sales and revenue line pick on the of following that best fit the description for this line- Aa subsection that shows the cost of goods that were sold to produce the sales.
- Ba subsection presenting sales, discounts, allowances and returns and other other related information. Its purpose is to arrive at the net amount of sales revenue.
- Ca list of expenses that the company has used in an attempt to make sales
- Da subsection reporting the general administration of sales.
72On the income statement under the operating section the following are listed:
Sales or revenue
Cost of goods sold
Selling expense
Administrative or General Expenses
For the Cost of goods sold line pick on the of following that best fit the description for this line:- Aa subsection that shows the cost of goods that were sold to produce the sales.
- Ba subsection presenting sales, discounts, allowances and returns and other other related information. Its purpose is to arrive at the net amount of sales revenue.
- Ca list of expenses that the company has used in an attempt to make sales.
- Da subsection reporting the general administration of sales.
73On the income statement under the operating section the following are listed:
Sales or revenue
Cost of goods sold
Selling expense
Administrative or General Expenses
For the selling expense line pick on the of following that best fit the description for this line:- Aa subsection that shows the cost of goods that were sold to produce the sales.
- Ba subsection presenting sales, discounts, allowances and returns and other other related information. Its purpose is to arrive at the net amount of sales revenue.
- Ca list of expenses that the company has used in an attempt to make sales
- Da subsection reporting the general administration of sales.
74On the income statement under the operating section the following are listed:
Sales or revenue
Cost of goods sold
Selling expense
Administrative or General Expenses
For the administrative or general expenses line pick on the of following that best fit the description for this line:- Aa subsection that shows the cost of goods that were sold to produce the sales.
- Ba subsection presenting sales, discounts, allowances and returns and other other related information. Its purpose is to arrive at the net amount of sales revenue.
- Ca list of expenses that the company has used in an attempt to make sales
- Da subsection reporting the general administration of sales.
75non operating expenses:
- Aa section reporting federal and state taxes
- Bare expenses and revenues resulting from auxiliary activities of the company in addition to special gains and losses that are infrequent or unusual activities
- Cmaterial gains/losses resulting from the disposal of a business component
76non operating section are expenses and revenues resulting from auxiliary activities of the company in addition to special gains and losses that are infrequent or unusual activities . they normally consist of:
- Aother revenues and gains and other expenses and losses
- Bother revenues and gains: a list of revenues recognized or gains incurred generally net of related expenses from non operating transactions
- Cother expenses and losses: a list of expenses or losses incurred generally net of related incomes from non operating transactions
77INCOME TAX
- AA measure of performance over the reporting period.
- BAllocation of income to noncontrolling shareholders.
- CMaterial gains or losses resulting from the disposition of a component of the business.
- DA section reporting federal and state taxes levied on income from continuing operations.
78DISCONTINUED OPERATIONS
- AMaterial gains or losses resulting from the disposition of a component of the business.
- BAllocation of income to noncontrolling shareholders.
- CA measure of performance over the reporting period.
79 NONCONTROLLING INTEREST
- AA section reporting federal and state taxes levied on income from continuing operations.
- BMaterial gains or losses resulting from the disposition of a component of the business.
- CAllocation of income to noncontrolling shareholders.
80EARNINGS PER SHARE (eps)
- AA measure of performance over the reporting period
- BMaterial gains or losses resulting from the disposition of a component of the business.
- C. A list of the revenues recognized or gains incurred,
generally net of related expenses, from nonoperating transactions.
81click which of the following is listed first on the income statement
- Anonoperating section
other revenues and gains
other expenses and losses - Bincome tax
discontinued operations
noncontrolling interests
earnings per share - COperating expenses
sales or revenues
cost of goods sold
selling expenses
administrative expenses
- Anonoperating section
82click which of the following is listed second on the income statement
- Anonoperating section
other revenues and gains
other expenses and losses - Bincome tax
discontinued operations
noncontrolling interests
earnings per share - COperating expenses
sales or revenues
cost of goods sold
selling expenses
administrative expenses
- Anonoperating section
83click which of the following is listed 3rd on the income statement
- Aincome tax
- Bnonoperating section
other revenues and gains
other expenses and losses - Cnoncontrolling interests
84click which of the following is listed 4rd on the income statement
- ADiscontinued operations
- Bnoncontrolling interests
- Cearnings per share
85click which of the following is listed 5rd on the income statement
- Anoncontrolling interest
- Bdiscontinued operations
- Cearnings per share
86click which of the following is listed 6rd on the income statement
- AEPS
- BINCOME TAX
- CNONCONTROLLING INTEREST
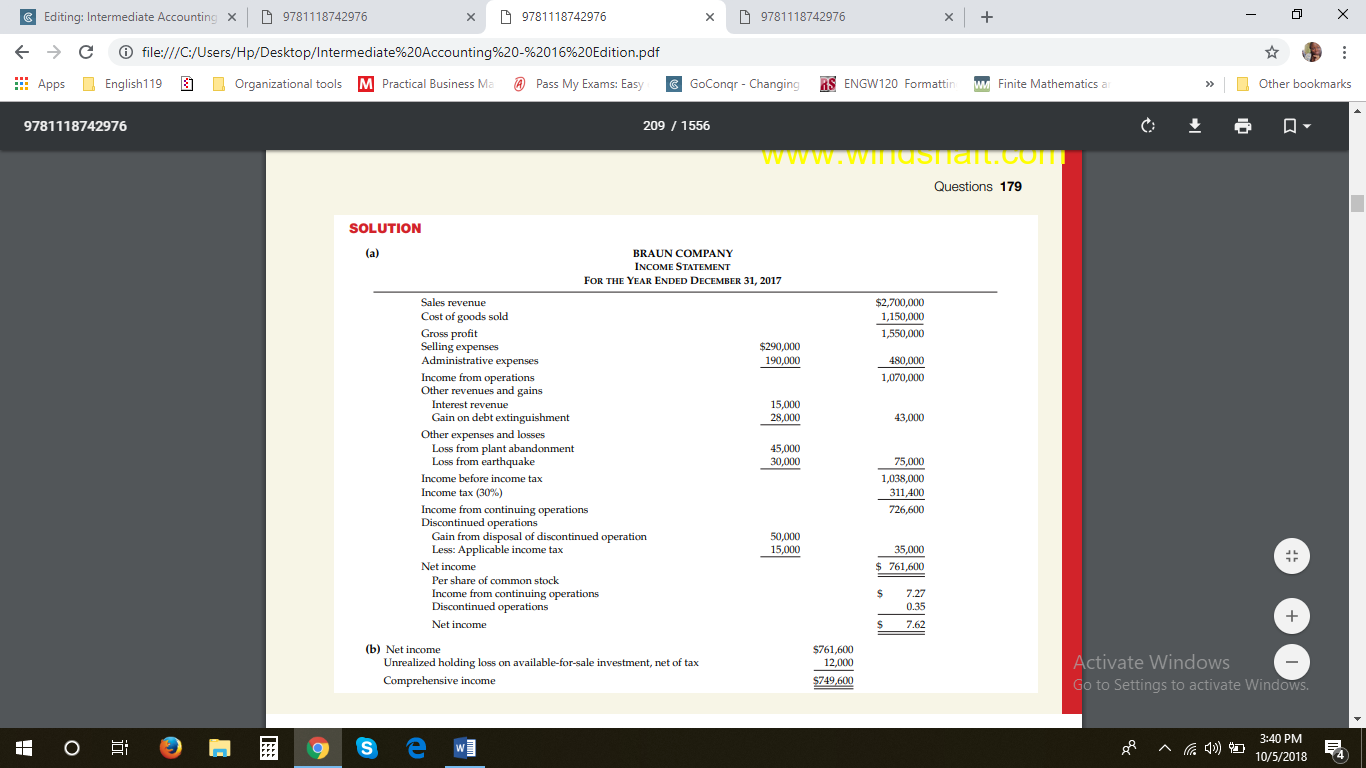
87Presented below are 11 income statement items from Braun Company for the year ended December 31, 2017.
Sales revenue $2,700,000
Cost of goods sold 1,150,000
Interest revenue 15,000
Loss from abandonment of plant assets 45,000
Gain from extinguishment of debt 28,000
Selling expenses 290,000
Administrative expenses 190,000
Effect of change in estimated useful lives of fixed assets
(included in administrative expenses) 35,000
Loss from earthquake 30,000
Gain on disposal of discontinued operation 50,00
(a) Using the information above, prepare a condensed multiple-step income statement. Assume a tax rate of 30% and 100,000 shares of common stock outstanding during 2017.
(b) Compute comprehensive income for Braun in 2017, assuming Braun had an unrealized holding loss on an available-for-sale
debt investment, net of tax, $12,000.- Anet income: 761,600
- BUnderneath the earnings per share section: there should be
INCOME FROM CONTINUING OPERATIONS
DISCONTINUED OPERATIONS
EXTRAORDINARY ITEMS
NET INCOME
- Anet income: 761,600
88Intraperiod tax allocations helps readers of financial statements will understand how much income tax expense relates to “Income from continuing operations” and how much to discontinued operations.
- ATrue
- BFalse
89Companies use intraperiod tax allocation on the income statement for (1) income
from continuing operations and (2) discontinued operations. The general concept is “let
the tax follow the income.- ATrue
- BFalse
90how do companies compute intraperiod tax allocation
- ACompanies then associate a separate tax effect for discontinued operations.
- BTo compute the income tax expense attributable to “Income from continuing operations,”
a company computes the income tax expense related to both the revenue and
expense transactions as well as other income and expense used in determining this
income subtotal.
91discontinued operations is normally listed in its separate section underneath:
- Aincome from operations
- Bincome from continuing operations after other expenses and losses are subtracted from amount after other revenues amount
92for noncontrolling GAAP requires that net income be allocated to controlling and noncontrolling
- ATrue
- BFalse
93The noncontrolling interest amounts are not an expense or dividend, but are allocations
of net income (loss) to the noncontrolling interest.- ATrue
- BFalse
94A company customarily sums up the results of its operations in one important figure: net
income.- ATrue
- BFalse
95the financial world has widely accepted an even more distilled and
compact figure as the most significant business indicator—earnings per share (EPS)- ATrue
- BFalse
96The computation of earnings per share is usually straightforward. Earnings per
share is net income minus preferred dividends (income available to common stockholders),
divided by the weighted average of common shares outstanding- ATrue
- BFalse
97assume that Lancer, Inc. reports net income of $350,000. It declares and
pays preferred dividends of $50,000 for the year. The weighted-average number of common
shares outstanding during the year is 100,000 shares- A2.00
- B3.00
- C1.00
98discontinued items are listed on the earnings per share section
- ATrue
- BFalse
99state where the following items should be placed on the income statement:
--->>>> unusual or infrequent gains or losses
discontinued operations
non controlling interest
earnings per share
- Aother revenues and other expenses (not shown net of tax)
- Bshown in separate section after income from continuing operations
100state where the following items should be placed on the income statement:
unusual or infrequent gains or losses
discontinued operations
--->>>> non controlling interest
earnings per share
- Areports as a separate item below net income or loss as an allocation of the net income or loss
- Breports seperate eps for income from continuing operations
101reporting issues related to (1) accounting changes and errors,
(2) retained earnings statement, and (3) comprehensive income- Atrue
- Bfalse
102when a company adapts a new GAAP method this is called a change in accounting. One example would be ...
- AChanges in accounting principle include a change in the method of inventory pricing from FIFO to average-cost, or a change in accounting for construction contracts from the percentage of-completion to the completed-contract method
- BFIFO--->WEIGHTED AVERAGE COST
103A company recognizes a change in accounting principle by making a retrospective
adjustment to the financial statements- ATrue
- BFalse
104select the following that apply to changes in estimate:
- Achanging from one accounting principle to another
- Bestimates in the usefulness of live, salvage value of appreciable assets
- Cuncollectable receivables, inventory obsolescence, the number of periods expected to benefit from a particular expenditure
105select the examples that apply to changes in error:
- Aimproper reporting of revenue, accounting for stock compensation, allowances for receivables, inventories, and other provisions.
- Bcorrections n errors are treated as prior period adjustments. Companies record a correction of an error in the year in which it is discovered. One example is:
Retained earnings $100,000
Accounts receivables $100,000
106cash and stock dividends decrease retained earnings. Changes in accounting principles
(generally) and prior period adjustments may increase or decrease retained earning.- ATrue
- BFalse
107Net income increases retained earnings. A net loss decreases retained earnings.
- ATrue
- BFalse
108Companies often restrict retained earnings to comply with contractual requirements,
board of directors’ policy, or current necessity.- ATrue
- BFalse
109In some cases, companies transfer the amount of retained earnings restricted to an account titled:
- AAppropriated Retained Earnings
- Bprior period adjustments
110 The retained earnings section may therefore report two separate
amounts—(1) retained earnings free (unrestricted) and (2) retained earnings appropriated
(restricted)- ATrue
- BFalse
111Changes in accounting principles and corrections of errors are excluded from the calculation of net income because their effects relate to prior periods
- ATrue
- BFalse
112Comprehensive income includes all changes in equity during a period except those resulting from investments by owners and distributions
to owner- ATrue
- BFalse
113 Companies often prepare in columnar form the statement of stockholders’ equity
- ATrue
- BFalse
114 Stockholders’ equity is generally
comprised of contributed capital (common and preferred stock and additional paidin
capital) retained earnings, and the accumulated balances in other comprehensive
income- ATrue
- BFalse
115other links for chapter 4 quizes
- Ahttps://quizlet.com/192791474/acct315-exam-1-flash-cards/
- Bhttps://quizlet.com/29869174/financial-account-exam-2-flash-cards/
Information
- Description
- Income Statements
- Author
- Jaymie Curry
- Language
- English
- Views
- 8
- Rating
- No ratings yet Rate this quiz