
Quiz
CH 7,11
Create a free account to finish this quiz
Save your progress and see your final score.
Already have an account? Sign in
Questions in this quiz (43)
1The budget or schedule that provides necessary input data for the direct labour budget is the:
- Araw materials purchases budget.
- Bproduction budget.
- Cschedule of cash collections.
- Dcash budget.
2The cash budget must be prepared before you can complete the:
- Aproduction budget.
- Bbudgeted balance sheet.
- Craw materials purchases budget.
- Dschedule of cash disbursements.
3Which of the following is not a benefit of budgeting?
- AIt uncovers potential bottlenecks before they occur.
- BIt coordinates the activities of the entire organization by integrating the plans and objectives of the
various parts. - CIt ensures that accounting records comply with generally accepted accounting principles.
- DIt provides benchmarks for evaluating subsequent performance.
4The direct materials budget:
- Ais the beginning point in the budget process.
- Bmust provide for desired ending inventory as well as for production.
- Cis accompanied by a schedule of cash collections.
- Dis completed after the cash budget.
5The master budget process usually begins with the:
- Aproduction budget
- Boperating budget.
- Csales budget.
- Dcash budget.
6There are various budgets within the master budget. One of these budgets is the production budget.
Which of the following BEST describes the production budget?- AIt details the required direct labour hours.
- BIt details the required raw materials purchases.
- CIt is calculated based on the sales budget, the desired beginning inventory and the desired ending
inventory. - DIt summarizes the costs of producing required units for the budget period.
7Fairmont Inc. uses an accounting system that charges costs to the manager who has been delegated the authority to make decisions concerning the costs. For example, if the sales manager accepts a rush order that will result in higher than normal manufacturing costs, these additional costs are charged
to the sales manager because the authority to accept or decline the rush order was given to the sales manager. This type of accounting system is known as:- Aresponsibility accounting.
- Bcontribution accounting.
- Cabsorption accounting.
- Dperational budgeting.
8Parlee Company's sales are 30% in cash and 70% on credit. Sixty percent of the credit sales are
collected in the month of sale, 25% in the month following sale, and 12% in the second month following sale. The remainder are uncollectible. The following are budgeted sales data:

Total cash receipts in April would be budgeted to be: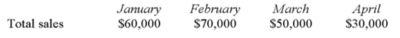
- A$27,230.
- B$36,230.
- C$38,900.
- D$47,900.
9The standards that allow for no machine breakdowns or other work interruptions and that require peak efficiency at all times are referred to as:
- Anormal standards.
- Bpractical standards.
- Cideal standards.
- Dbudgeted standards.
10To measure controllable production inefficiencies, which of the following is the best basis for a
company to use in establishing the standard hours allowed for the output of one unit of product?- AAverage historical performance for the last several years.
- BEngineering estimates based on ideal performance.
- CEngineering estimates based on attainable performance.
- DThe hours per unit that would be required for the present workforce to satisfy expected demand over the long run.
11Which of the following statements concerning practical standards is incorrect?
- APractical standards can be used for product costing and cash budgeting.
- BPractical standards can be attained by the average worker.
- CWhen practical standards are used, there is no reason to adjust standards if an old machine is
replaced by a newer, faster machine. - DUnder practical standards, large variances are less likely than under ideal standards.
12If a company follows a practice of isolating variances at the earliest point in time, what would be the appropriate time to isolate and recognize a direct material price variance?
- AWhen material is issued.
- BWhen material is purchased.
- CWhen material is used in production.
- DWhen production is completed.
13An unfavourable labour efficiency variance indicates that:
- Athe actual labour rate was higher than the standard labour rate.
- Bthe labour rate variance must also be unfavourable.
- Cactual labour hours worked exceeded standard labour hours for the production level achieved.
- Dovertime labour was used during the period.
14A favourable labour rate variance indicates that:
- Aactual hours exceed standard hours.
- Bstandard hours exceed actual hours.
- Cthe actual rate exceeds the standard rate.
- Dthe standard rate exceeds the actual rate.
15What does a credit balance in a direct labour efficiency variance account indicate?
- AThe average wage rate paid to direct labour employees was less than the standard rate.
- BThe standard hours allowed for the units produced were greater than actual direct labour hours
used. - CActual total direct labour costs incurred were less than standard direct labour costs allowed for the
units produced. - DThe number of units produced was less than the number of units budgeted for the period.
16If the actual labour hours worked exceed the standard labour hours allowed, what type of variance will
occur?- AFavourable labour efficiency variance.
- BFavourable labour rate variance.
- CUnfavourable labour efficiency variance.
- DUnfavourable labour rate variance.
17Which of the following is the most probable reason a company would experience an unfavourable labour rate variance and a favourable labour efficiency variance?
- Athe mix of workers assigned to the particular job was heavily weighted towards the use of higher
paid, experienced individuals. - Bthe mix of workers assigned to the particular job was heavily weighted towards the use of new
relatively low paid, unskilled workers. - Cbecause of the production schedule, workers from other production areas were assigned to assist
this particular process. - Ddefective materials caused more labour to be used in order to produce a standard unit.
- Athe mix of workers assigned to the particular job was heavily weighted towards the use of higher
18Which department is usually held responsible for an unfavourable materials quantity variance?
- AMarketing.
- BPurchasing.
- CEngineering.
- DProduction.
19A favourable material price variance coupled with an unfavourable material usage variance would
most likely result from:- Aproblems with processing machines.
- Bthe purchase of low quality material
- Cproblems with labour efficiency.
- Dchanges in the product mix.
20Tower Company planned to produce 3,000 units of its single product, Titactium, during November.
The standards for one unit of Titactium specify six grams of materials at $0.30 per gram. Actual production in November was 3,100 units of Titactium. There was a favourable materials price variance of $380 and an unfavourable materials quantity variance of $120. Based on these variances, one could conclude that:- Amore materials were purchased than were used.
- Bmore materials were used than were purchased.
- Cthe actual cost per gram for materials was less than the standard cost per gram.
- Dthe actual usage of materials was less than the standard allowed.
21A labour efficiency variance resulting from the use of poor quality materials should be charged to:
- Athe production manager.
- Bthe purchasing agent.
- Cmanufacturing overhead.
- Dthe engineering department.
22Drake Company purchased materials on account. The entry to record the purchase of materials having a standard cost of $1.50 per gram from a supplier at $1.60 per gram would include a:
- Acredit to raw materials inventory.
- Bdebit to work in process.
- Ccredit to materials price variance.
- Ddebit to materials price variance.
23Which of the following entries would correctly record the charging of direct labour costs to work in
process given an unfavourable labour efficiency variance and a favourable labour rate variance?- AWork in process Labour efficiency variance Labour rate variance Wages payable
- BWork in process Wages payable
- CWork in process Labour rate variance Labour efficiency variance Wages payable
24Under a standard cost system, the material price variances are usually the responsibility of the:
- Aproduction manager.
- Bsales manager.
- Cpurchasing manager.
- Dengineering manager.
25The terms "standard quantity allowed" or "standard hours allowed" mean:
- Athe actual output in units multiplied by the standard output allowed.
- Bthe actual input in units multiplied by the standard output allowed.
- Cthe actual output in units multiplied by the standard input allowed.
- Dthe standard output in units multiplied by the standard input allowed.
26Dahl Company, a clothing manufacturer, uses a standard costing system. Each unit of a finished
product contains 2 metres of cloth. However, there is unavoidable waste of 20%, calculated on input quantities, when the cloth is cut for assembly. The cost of the cloth is $3 per metre. The standard direct material cost for cloth per unit of finished product is:- A$4.80.
- B$6.00
- C$7.20.
- D7.50.
27Budgeted sales in Allen Company over the next four months are given below:
Twenty-five percent of the company's sales are for cash and 75% are on credit. Collections for sales on credit follow a stable pattern as follows: 50% of a month's sales are collected in the month of sale, 30% are collected in the month following sale, and 15% are collected in the second month following sale. The remainder are uncollectible. Given these data, cash collections in December should be?- A$103,500.
- B$120,000.
- C$133,500.
- D$153,000.
28The PDQ Company makes collections on credit sales according to the following schedule:
25% in month of sale
70% in month following sale
4% in second month following sale
1% uncollectible
The following sales have been budgeted:
The budget for cash collections in June will be:- A$110,000.
- B$111,000.
- C$113,400.
- D$115,500.
29Orion Corporation is preparing a cash budget for the six months beginning January 1. Shown below
are the company's expected collection pattern and the budgeted sales for the period.
Expected collection pattern:
65% collected in the month of sale
20% collected in the month after sale
10% collected in the second month after sale 4% collected in the third month after sale 1% uncollectible
The estimated total cash collections during April from sales and accounts receivables will be:- A$155,900.
- B$167,000.
- C$171,666.
- D$173,400.
30Pardee Company plans to sell 12,000 units during the month of August. If the company has 2,500 units on hand at the start of the month, and plans to have 2,000 units on hand at the end of the month, how many units must be produced during the month?
- A11,500 units.
- B12,000 units.
- C12,500 units.
- D14,000 units.
31ABC Company has a cash balance of $9,000 on April 1. The company must maintain a minimum cash
balance of $6,000. During April expected cash receipts are $45,000. Expected cash disbursements during the month total $52,000. During April the company will need to borrow:- A2,000.
- B4000
- C6000
- D8000
32A cash budget by quarters for the Carney Company is given below (note that some data are missing). Missing data amounts have been keyed with either question marks or lower case letters (a, b, c,
etc.); these lower case letters will be referred to in the questions that follow. (It may be necessary to calculate a value for items where a question mark appears.) The company requires a minimum cash balance of at least $10,000 to start a quarter. All data are in thousands.
The collections from customers during the first quarter (item a in thousands) are:- A$50.
- B$57
- C$60.
- D$73
33A cash budget by quarters for the Carney Company is given below (note that some data are missing). Missing data amounts have been keyed with either question marks or lower case letters (a, b, c,
etc.); these lower case letters will be referred to in the questions that follow. (It may be necessary to calculate a value for items where a question mark appears.) The company requires a minimum cash balance of at least $10,000 to start a quarter. All data are in thousands.
The borrowing required during the first quarter to meet the minimum cash balance (item b in
thousands) is:- A$0.
- B$3
- C$7
- D$10
34A cash budget by quarters for the Carney Company is given below (note that some data are missing). Missing data amounts have been keyed with either question marks or lower case letters (a, b, c,
etc.); these lower case letters will be referred to in the questions that follow. (It may be necessary to calculate a value for items where a question mark appears.) The company requires a minimum cash balance of at least $10,000 to start a quarter. All data are in thousands.
The cash disbursed for purchases during the second quarter (item c in thousands) is:- A$9.
- B$13
- C$21
- D$55
35A cash budget by quarters for the Carney Company is given below (note that some data are missing). Missing data amounts have been keyed with either question marks or lower case letters (a, b, c,
etc.); these lower case letters will be referred to in the questions that follow. (It may be necessary to calculate a value for items where a question mark appears.) The company requires a minimum cash balance of at least $10,000 to start a quarter. All data are in thousands.
The repayment (including interest) of financing during the second quarter (item d in thousands) is:- A$0
- B$4
- C$7
- D$17
36
A cash budget by quarters for the Carney Company is given below (note that some data are missing). Missing data amounts have been keyed with either question marks or lower case letters (a, b, c,
etc.); these lower case letters will be referred to in the questions that follow. (It may be necessary to calculate a value for items where a question mark appears.) The company requires a minimum cash balance of at least $10,000 to start a quarter. All data are in thousands.
The cash balance at the beginning of the second quarter (item e in thousands) is:- A$0
- B$7
- C$10
- D$14
37A cash budget by quarters for the Carney Company is given below (note that some data are missing). Missing data amounts have been keyed with either question marks or lower case letters (a, b, c,
etc.); these lower case letters will be referred to in the questions that follow. (It may be necessary to calculate a value for items where a question mark appears.) The company requires a minimum cash balance of at least $10,000 to start a quarter. All data are in thousands.
The total disbursements during the third quarter (item f in thousands) are:- A$59
- B$78
- C$82.
- D$84
38Which one of the following tasks should be done first, when developing a comprehensive budget for a
manufacturing company?- ADetermination of the advertising budget.
- BDevelopment of a sales budget.
- CDevelopment of the capital budget.
- DDetermination of equipment acquisitions.
39Which one of the following is the last schedule to be prepared in a normal budget preparation process?
- AThe cash budget.
- BThe cost of goods sold budget.
- CThe direct labour budget.
- DThe selling expense budget.
40Which of the following statements is true about zero-based budgeting?
- AThe process starts with last year's budget and changes anticipated are added or subtracted to get the current budget.
- BManagers are required to justify all budgeted expenditures.
- CBudgets have no financial components - are specified in product units only.
- DManagers are required to use the prior year's budget without changes for the current year.
41Which of the following is not a suggested benefit of using the "Beyond Budgeting" model?
- ARolling forecasts are likely to be more accurate.
- BIndividual managers may be more accurately compensated when they achieve their own fixed . targetswhichwerenegotiatedbeforethefiscalyearbegan.
- CManagers may be better able to respond quickly to changing circumstances.
- DThe use of relative performance targets incorporating comparisons to other businesses in the same
industry may be more useful.
42Which of the following statements is not true about the Direct Labour Budget?
- AIf properly used it would assist in reducing inefficiency on the part of employees.
- BIt is developed after the Production Budget.
- COutput from this budget is used in the Selling and Administrative Expense Budget.
- DOutput from this budget is used to determine the cost of goods manufactured.
43Which of the following is not one of the positive attributes of responsibility accounting?
- AManagers should understand the source of significant variances to budget and should be prepared to . explainthereasonsfordiscrepanciestoseniormanagement.
- BBy assigning responsibilities for each cost, better cost control should result.
- CSenior management can more easily identify employees to blame.
- DManagers should take the initiative to correct unfavourable discrepancies.
Information
- Description
- ACT Year 12 Certificate FINA Quiz on CH 7,11, created by Rebecca Bosson on 18/04/2016.
- Author
- Rebecca Bosson
- Language
- English
- Views
- 0
- Tags
- Rating
- No ratings yet Rate this quiz