
Karteikarten
QFD Formulas
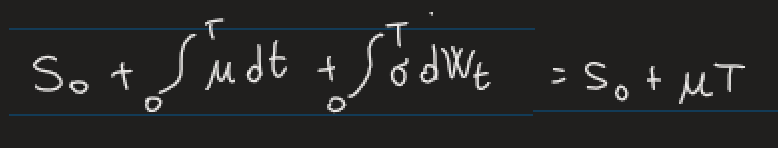
Karten in diesem Stapel (53)
- 1VAR[dWt]T-t
- 2E[dWt]0
- 3dSt Bachelier E[ST] = ?
- 4dSt Bachelier VAR [ST] = ?
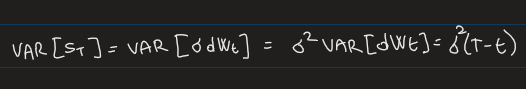
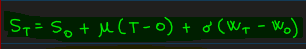
- 5dSt Bachelier ST = ?
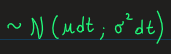
- 6How is dSt distributed under Bachelier?
- 7How is ST distributed under Bachelier? (suppose t = 0)
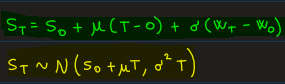
- 8Ito Formula under Bachelier

- 9Define d ln(St) under Black and Scholes. What is its expected value and variance?
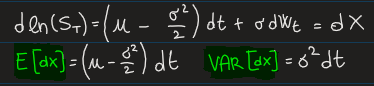
- 10How is ST defined in Black and Scholes?
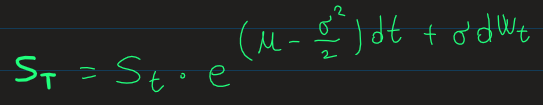
- 11dSt Black and Scholes E [ST] = ? VAR [ST] = ?
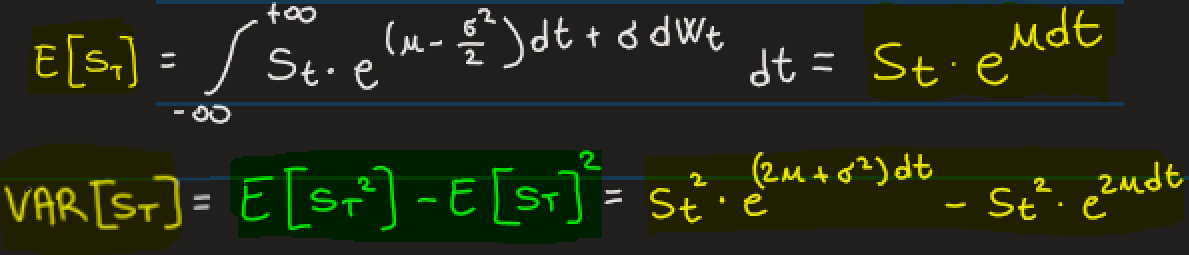
- 12dSt Black and Scholes Discounted stock price
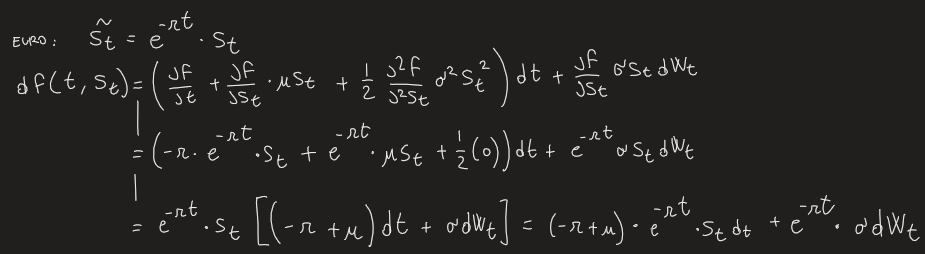
- 13Black and Scholes: Ito Formula
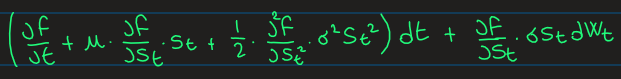
- 14Ito Formula Option with multiple assets

- 15Black and Scholes PDE
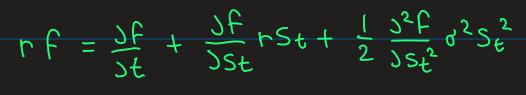
- 16How do you obtain the BS PDE?
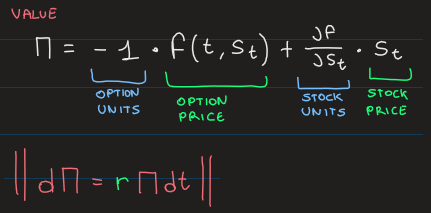
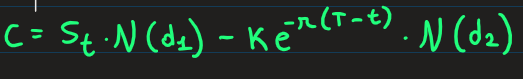
- 17EU Call
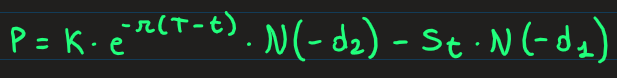
- 18EU Put
- 19Define d1 and d2 in the risk neutral valuation of european options
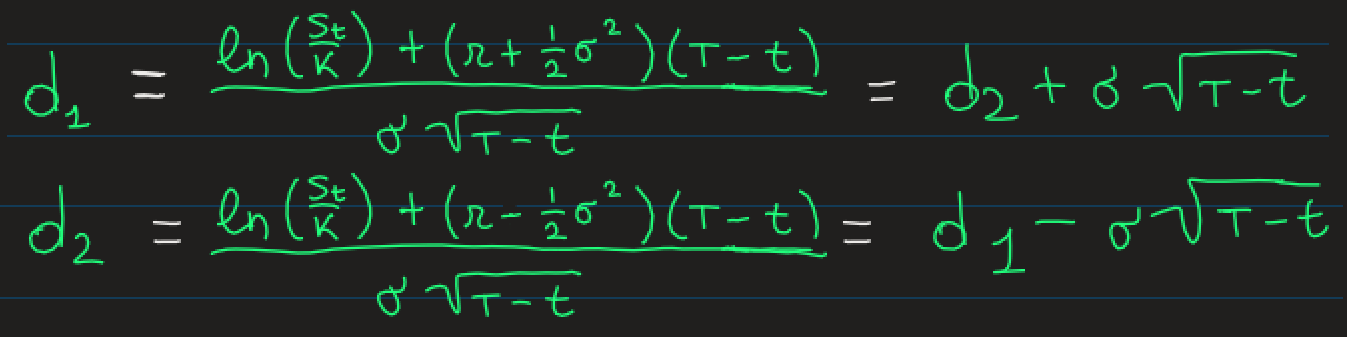
- 20Asset or Nothing CallSo * N(d1)
- 21Cash or Nothing CallK*e^(-rT) * N(d2)
- 22Cash or Nothing PutK*e^(-rT) * N(-d2)
- 23Asset or Nothing PutSo * N(-d1)
- 24Risk Neutral Probability in Cox Ross Rubinstein (q)
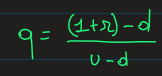
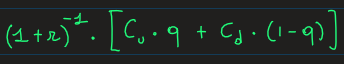
- 25EU Option under CRR
- 26US Option under CRRAt each node you take the highest between the EU price and the Intrinsic Value of the option (S-K for Calls, K-S for Puts)
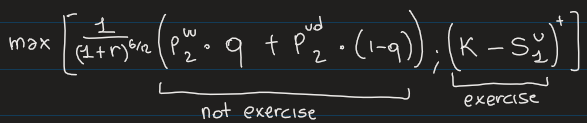
- 27Lookback Options under CRRConsider all possible paths to each final payoff. For each path, take the lowest St for a Call and the highest St for a Put.
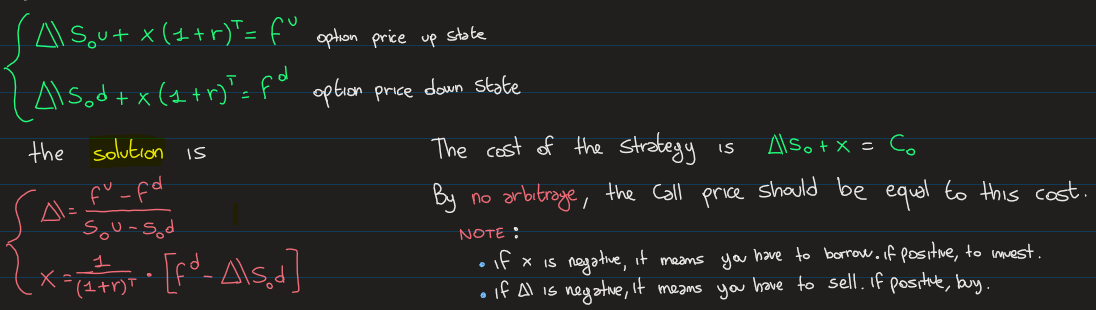
Then discount the product of the probabilities multiplied by the sum of the intrinsic values for each possible path. - 28Replicating strategy of an option in CRR
- 29Replicating strategy of a portfolio in CRR
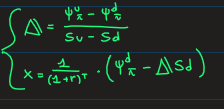
- 30Describe the different GreeksDelta: sens of option to underlying
Theta: sens of option to time.
Gamma: sens of delta to underlying (convexity)
Vega: sens of option to volatility.
Rho: sens of option to interest rate. - 31Delta Neutrality with Gamma in a range
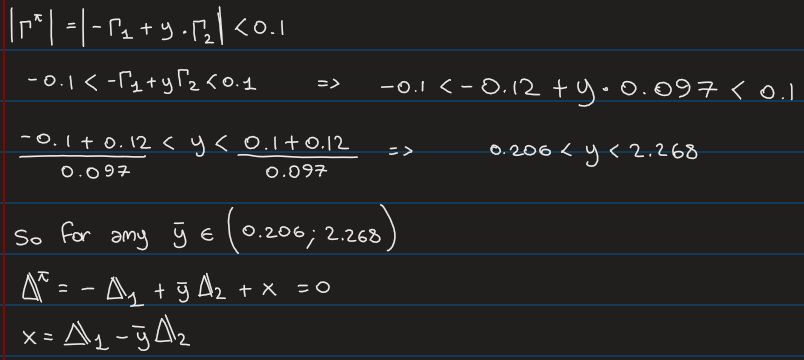
- 32Delta Gamma Vega Neutrality
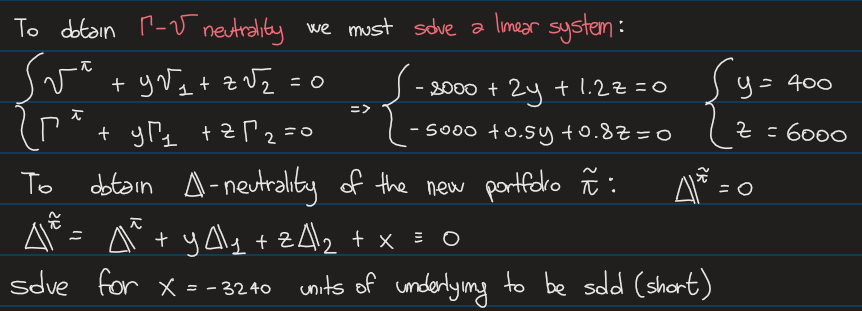
- 33Term Structure of Interest RatesBasically BS PD but with drift = u - lambda*sigma
i.e. the market price of risk
rt not multiplied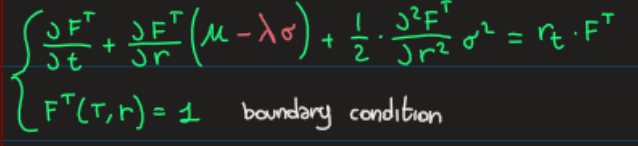
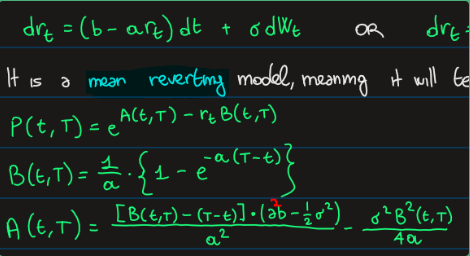
- 34When does rt admit an Affine Term Structure?
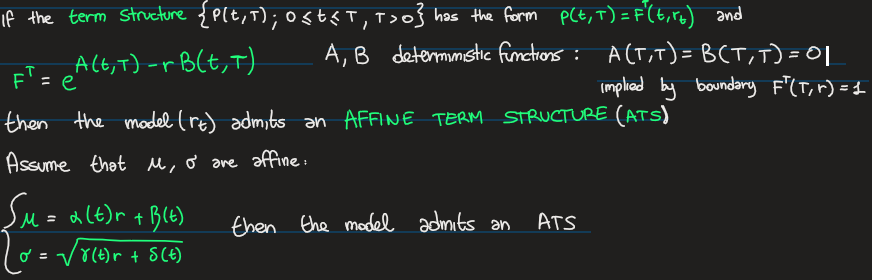
- 35Vasicek ATS
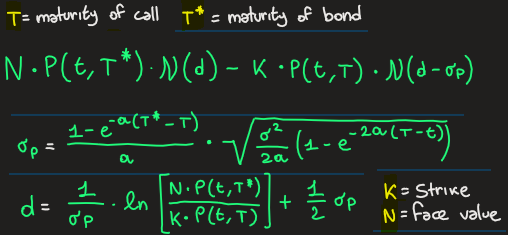
- 36Vasicek CALL Hull White Vasicek CALL
- 37Ho Lee ATS
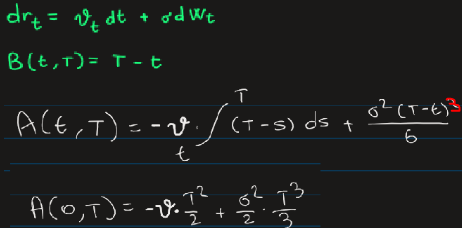
- 38Ho Lee CALL
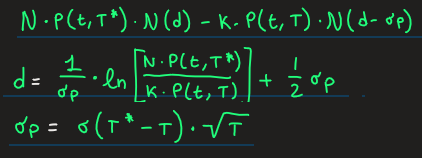
- 39CIR ATS
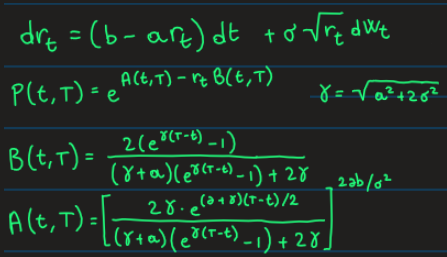
- 40Greeks of Cash or Nothing Put
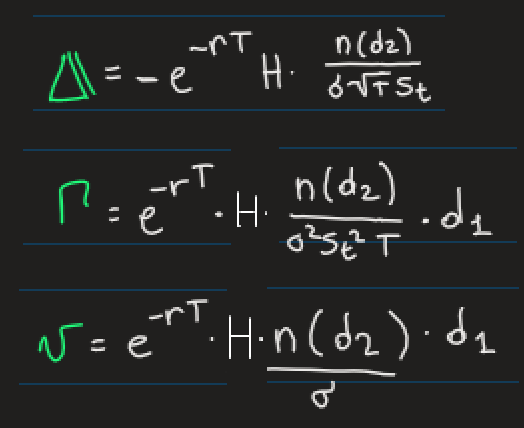
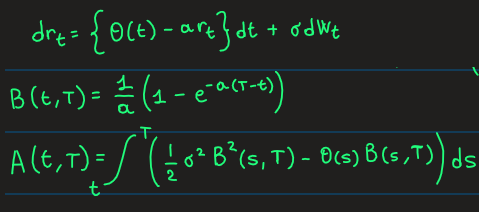
- 41Hull White ATS
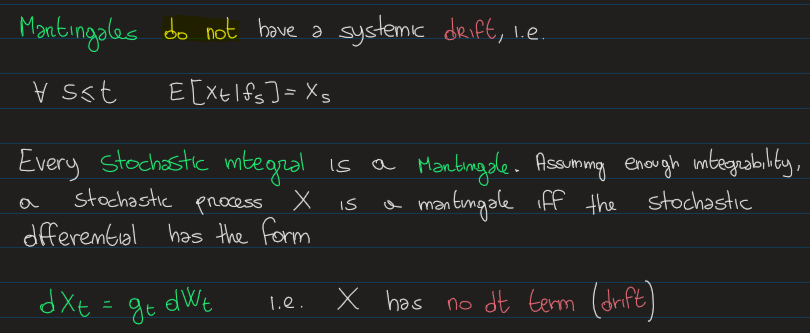
- 42Martingale
- 43Supposed you have a Bachelier model. How do you compute the probability of an event?Compute the probability, e.g Xt < 5, then
Isolate dWt and standardize. - 44Greeks of Cash or Nothing Call
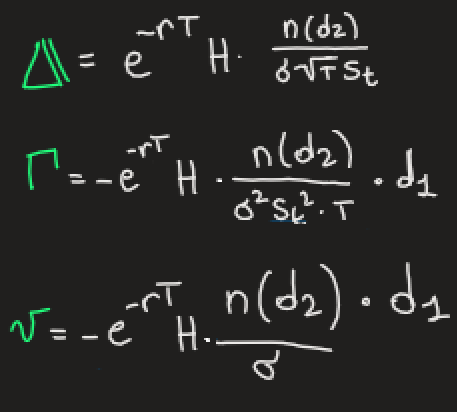
- 45what happens to the delta of a cash or nothing Call Option in the limit t-> oo : 1 - When St is close to K 2 - When St is far from K1 - Delta Very Large (Pin Risk)
2 - Delta Close to 0 - 46What is the interval of St for which the vega of a cash or nothing call option is negative?vega is positive when S < K (out the money)
Negative for S > K (in the money)
Study the sign of d2
denumerator always positive, so to be negative the numerator must be negative - 47Greeks of Asset or Nothing Call
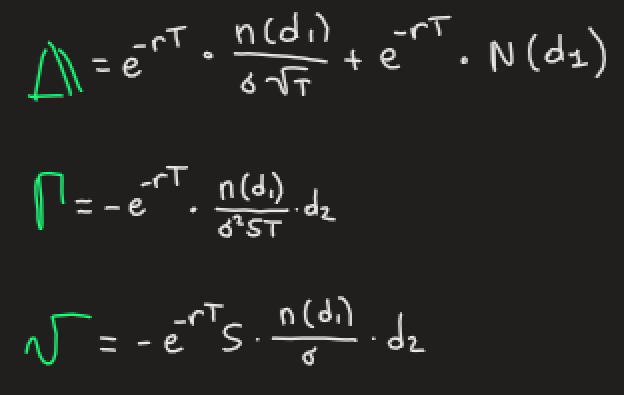
- 48Greeks of Asset or Nothing Put
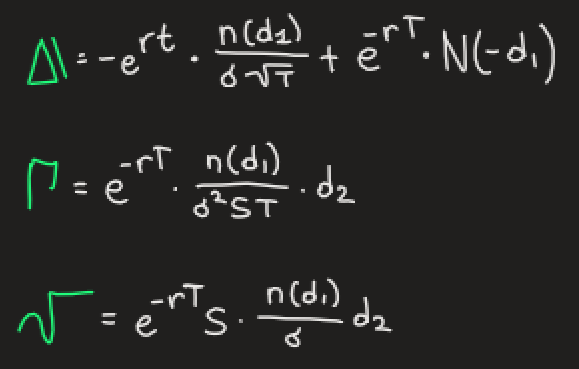
- 49Vasicek a(b-rt)dt + ... rt = ? E[rt] = ? VAR [rt] = ?
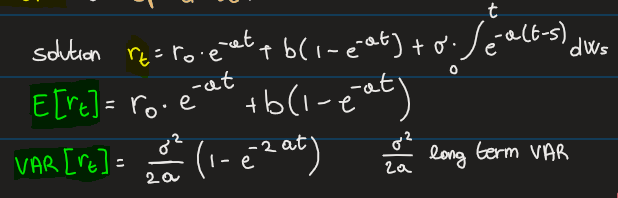
- 50delta gamma vega of eu options
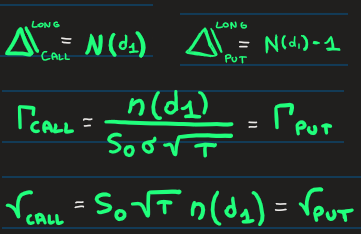
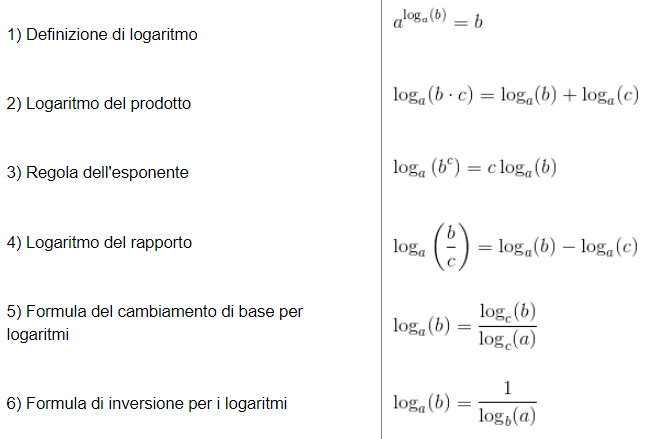
- 51Log properties
- 52Derivate: -esponenziale composta - prodotto - quoziente
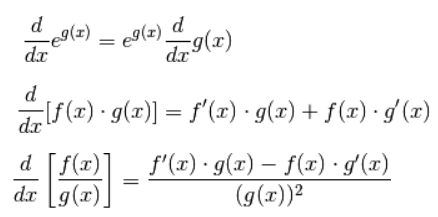
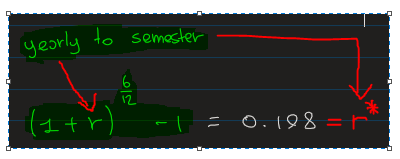
- 53Trasformare tasso di interesse annuale in quello di un altro periodo
Informationen
- Beschreibung
- Mathematics Karteikarten am QFD Formulas, erstellt von Manuel Gulino am 15/12/2022.
- Erstellt von
- Manuel Gulino
- Aufrufe
- 56
- Bewertung