Mapa mental
Foreign exchange rates
Contenido del mapa
Foreign exchange rates
Reporting FOREX transactions in functional currency
- Monetary items (MI)
- All current assets (excl. inventory) & liabilities; LT-borrowings; Debentures; Deferred tax; Some employee benefits; Div. payable; Convertible pref. shares (into debentures); Convertible debentures (into redeemable pref. shares)
- Non-monetary items (NMI)
- Inventories; PPE; Investment in ordinary shares; Ordinary shares; PMTS in Advance; Goodwill; Intangible assets; Reserves; Convertible pref. shares & debentures (convert to ordinary shares)
- Uncovered transactions: recorded in functional currency using spot rate at transaction date
- Transaction date: Date when risks & rewards of ownership are transferred to purchaser
- Monetary items (MI)
Covered transactions
- Firm commitment = binding agreement for the exchange of a specified quantity of resources at specific price & future date
- Forecast transaction = uncommitted but anticipated future transaction
- Hedging instrument = designated derivative (hedge of risk of change in forex rates only); OR = designated non-derivative fin. asset; OR = non-derivative fin. liability whose fair value / CFj are expected to offset changes in the FV / CFj of a desinated hedged item
Uncovered transactions
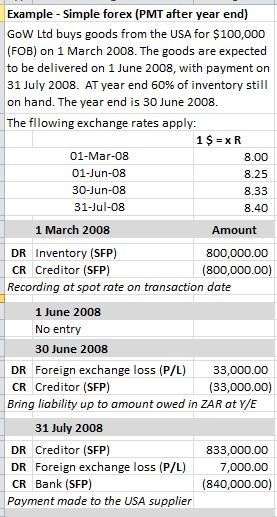
- At spot rate t.i.a: >MI recorded at closing spot rate at year end [ gives rise to FOREX G/L ]; >NMI recorded at spot rate always
Hedge accounting
- Criteria to hedge: (Only if ALL are met)
- > At inception of hedge item there is a formal designation & documentation of the hedging relationship; > Hedge is expected to be highly effective; > For CFj hedges, a forecast transaction MUST be highly probable & present an exposure to variations in cash flows that effect P/L; > Effectiveness of hedge reliably measured; > Hedge is assessed on an ongoing basis.
- Fair value hedge
- Underlying transaction present
- Steps to account
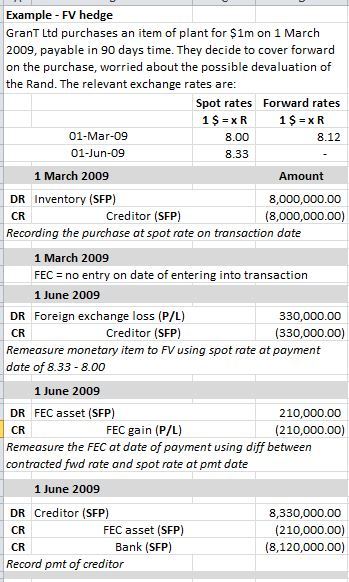
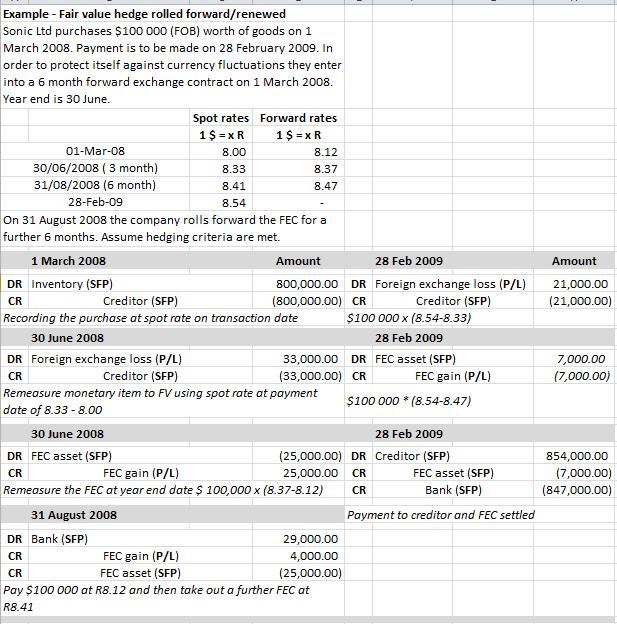
- 1. Entering into FEC = No transaction recorded; 2. IF YR/END AFTER SETTLEMENT = G/L on settlement of FEC the diff between MI recorded at spot rate on settlement date & amount paid/received ito FEC; 3. IF YR/END IS BEFORE SETTLEMENT = G/L on FEC is diff between contracted forward rate & contract forward rate of Similar FEC for remaining period until maturity; 4. IF FEC IS RENEWED OR ROLLED FORWARD = on maturity date recognise G/L on FEC as that between original forward rate & spot rate at that date.
- Cash flow hedge
- No underlying transaction
- Steps to account
- 1. Entering into FEC = No transaction recorded; 2. When UT is recorded OR YR/END reached, value of FEC = Foreign currency X [ Contracted forward rate less similar FEC on remaining period rate ] ; 3. Decide IF hedge effective, recognise G/L in SCE, IF ineffective, recognise G/L in P/L
- IF recognised in SCE :
- Fin. asset/liability recognised: >G/L recogn. directly in Equity is reclassified to I/S in period the A/L affects I/S ; > any unrecoverable amount is recogn. in I/S if entity expects all/portion of loss recogn. in E will not be recovered in future.
- Non-financial asset/liability or firm commitment: >G/L recogn. directly in Equity is reclassified to I/S in period the A/L affects I/S ; OR reclassify G/L to asset/ liability so covered.
- IF recognised in SCE :
- 1. Entering into FEC = No transaction recorded; 2. When UT is recorded OR YR/END reached, value of FEC = Foreign currency X [ Contracted forward rate less similar FEC on remaining period rate ] ; 3. Decide IF hedge effective, recognise G/L in SCE, IF ineffective, recognise G/L in P/L
- Criteria to hedge: (Only if ALL are met)