
Flashcards
CFA L2 Part 2
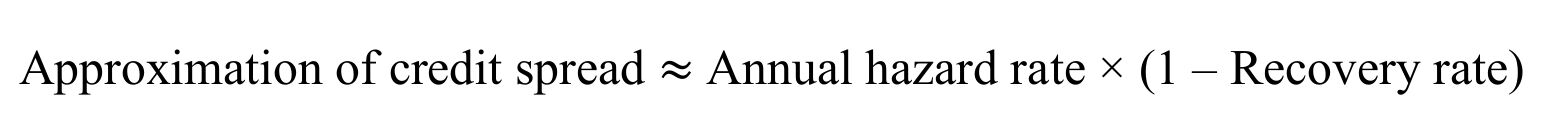
Cards in this deck (47)
- 1Approximation of Credit Spread
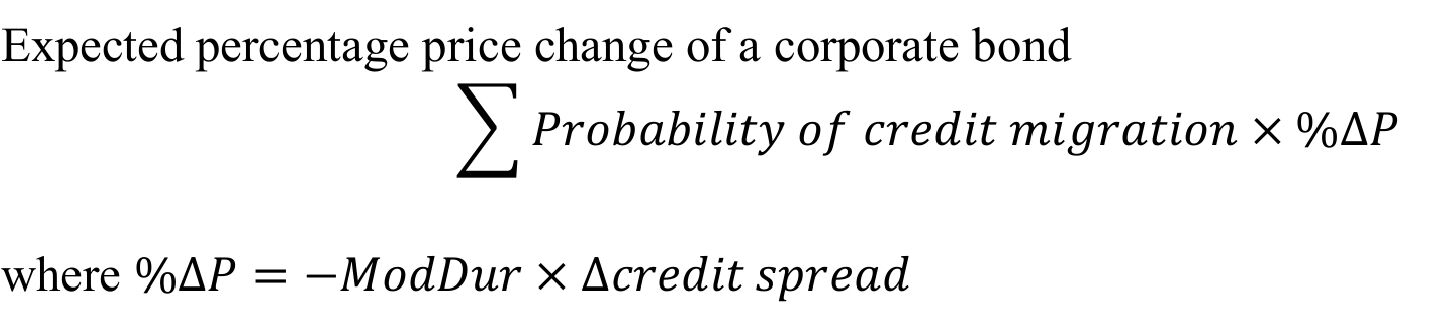
- 2Price change of bond given credit migration
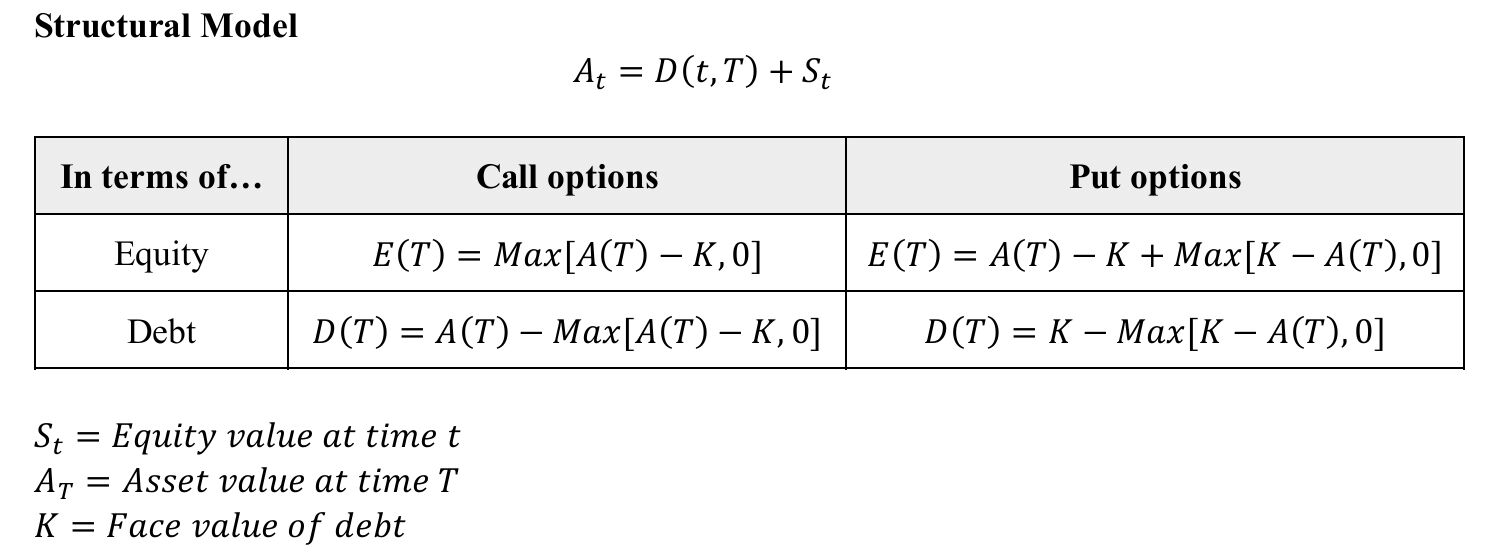
- 3Structural Model of company debt
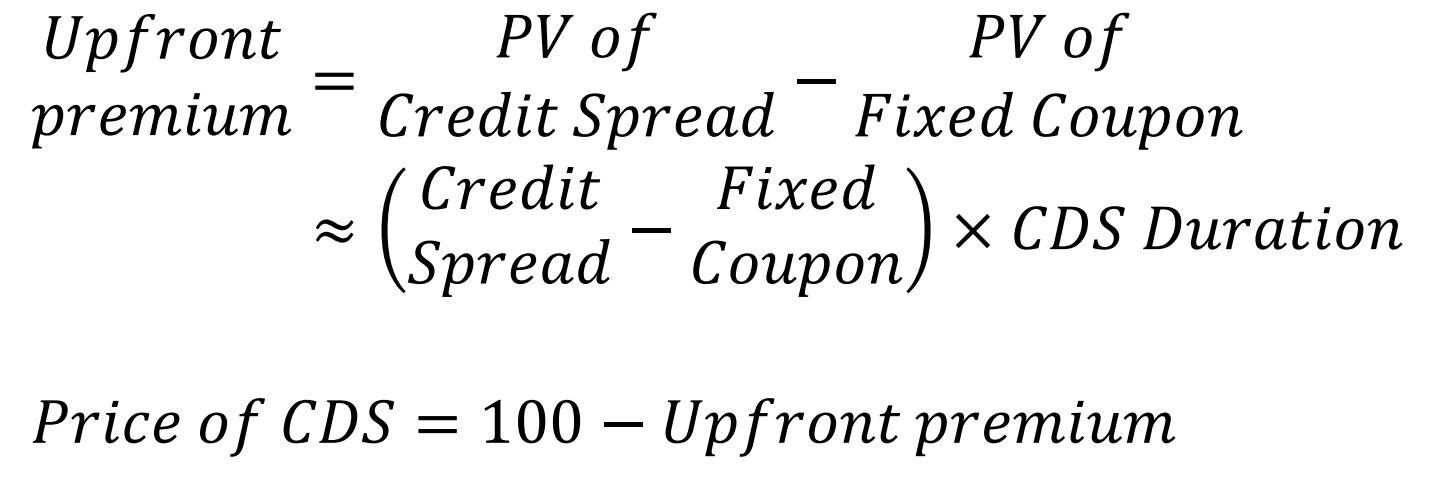
- 4CDS Payment Amount

- 5Price of CDS
- 6% Change in CDS Price
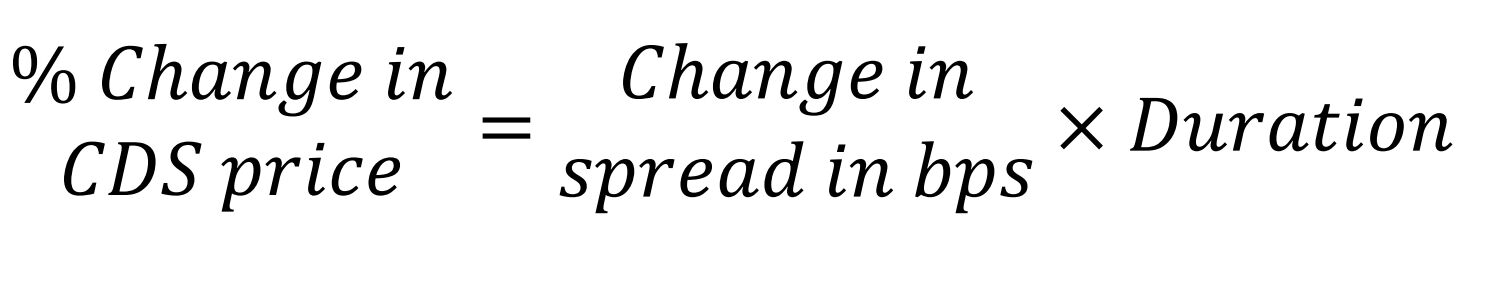
- 7Forward Pricing
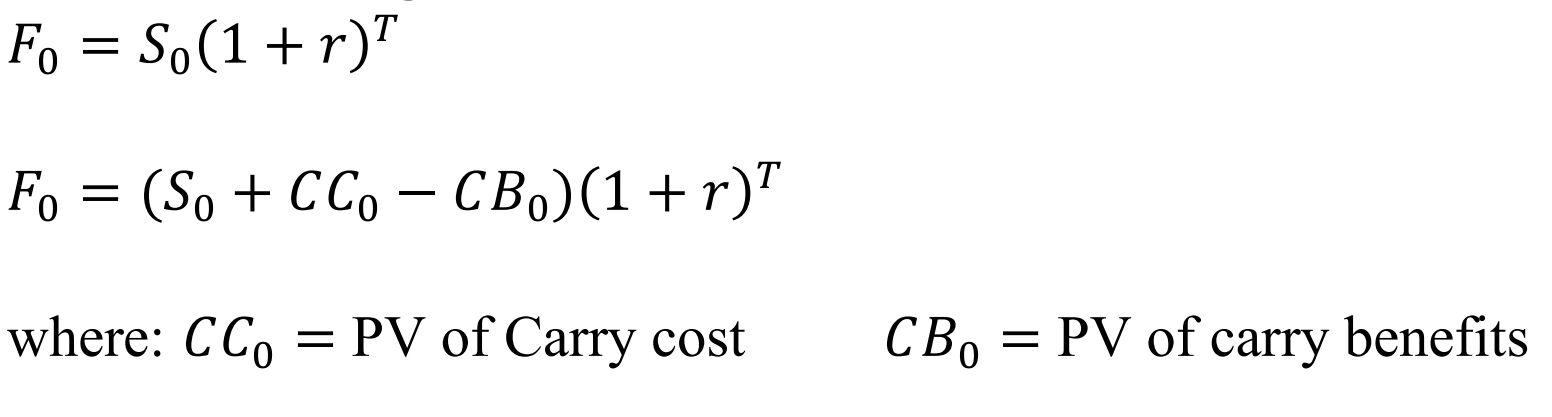
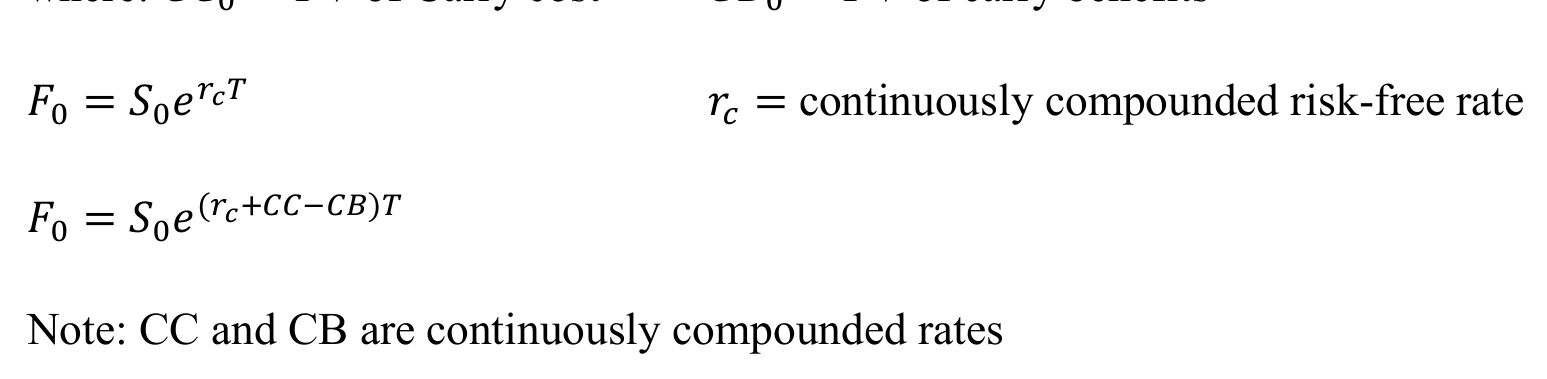
- 8Forward Pricing continuous compounding
- 9Forward Valuation Long Position
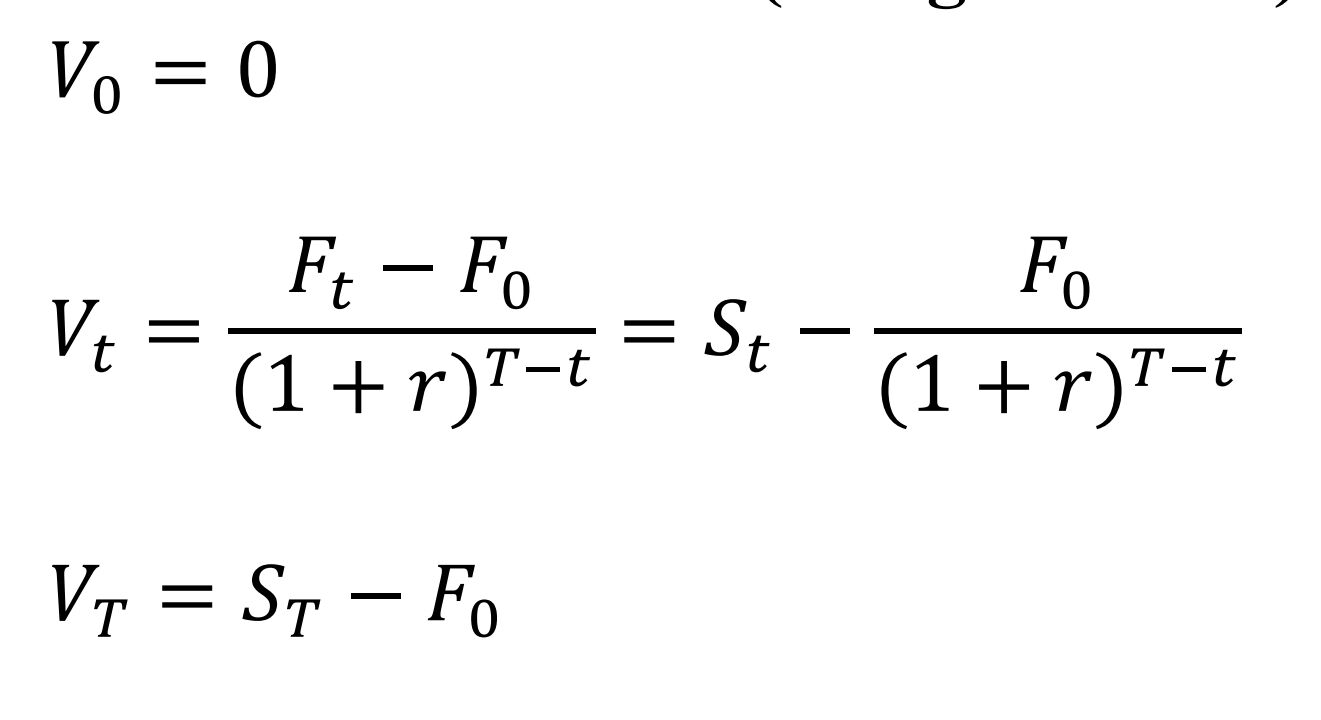
- 10Long FRA Payoff at expiration
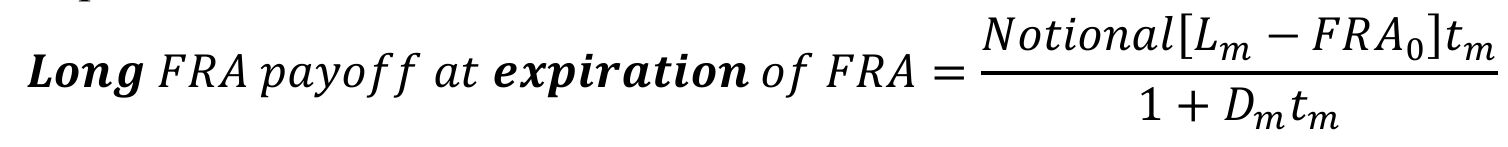
- 11FRA Price
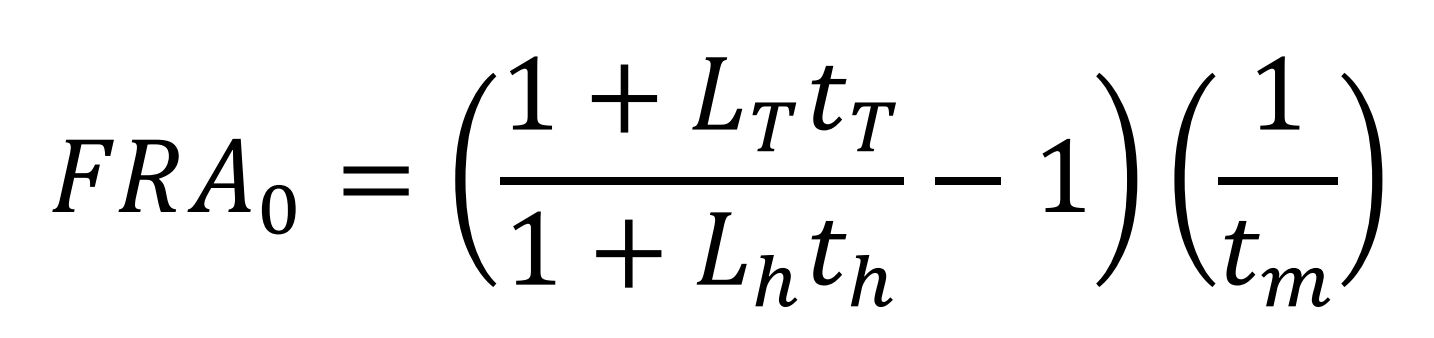
- 12Value of Long FRA prior to expiration
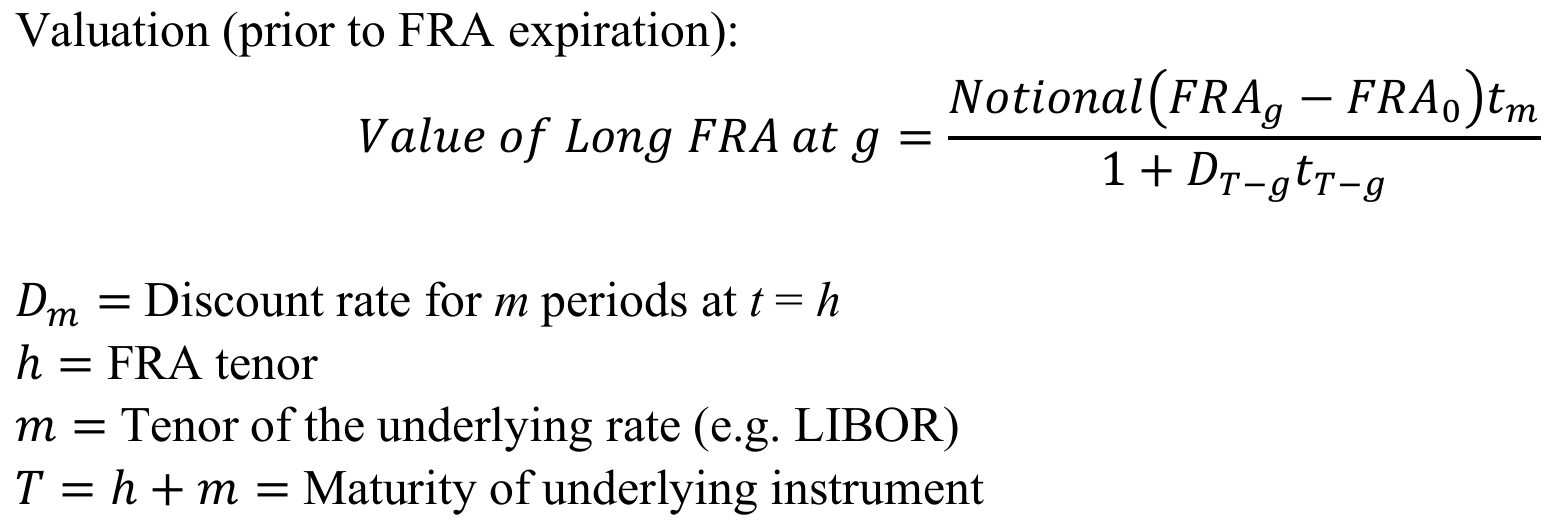
- 13Price of Bond Forwards
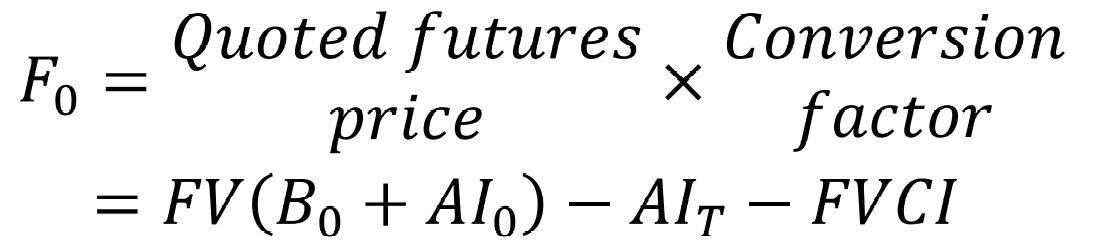
- 14Valuation for bond forward contracts
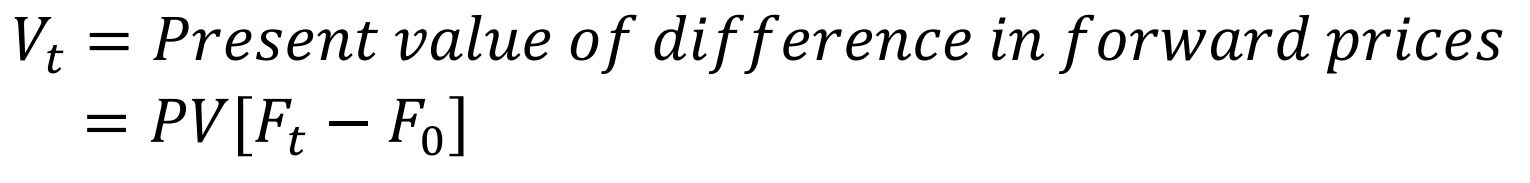
- 15Pricing of Interest Rate Swaps
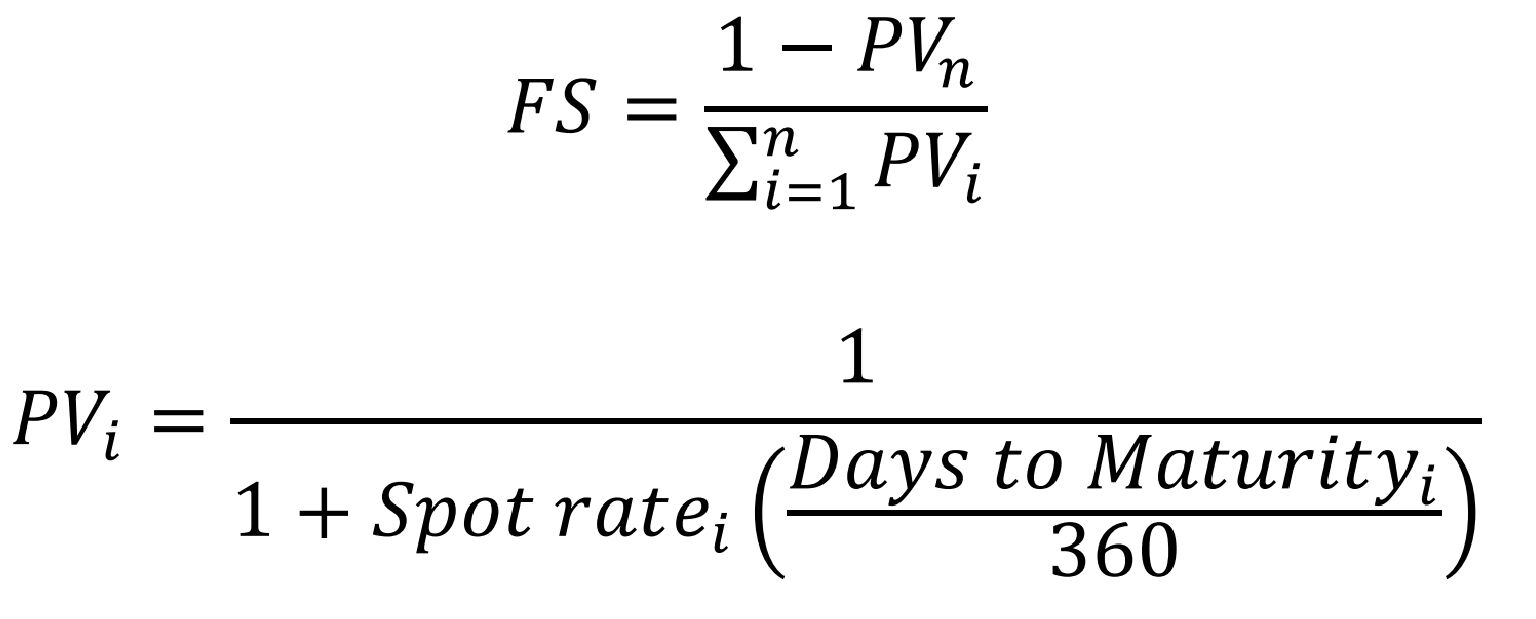
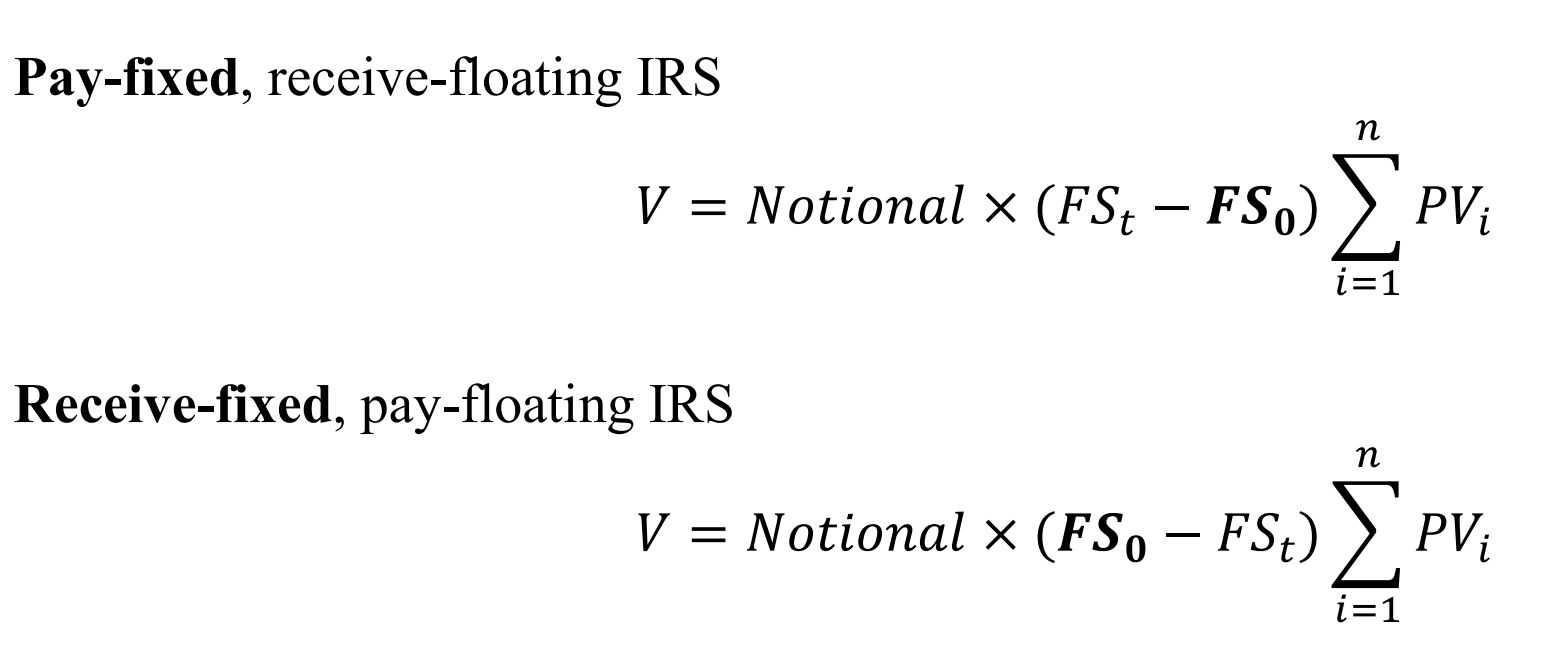
- 16Valuation of Interest Rate Swaps
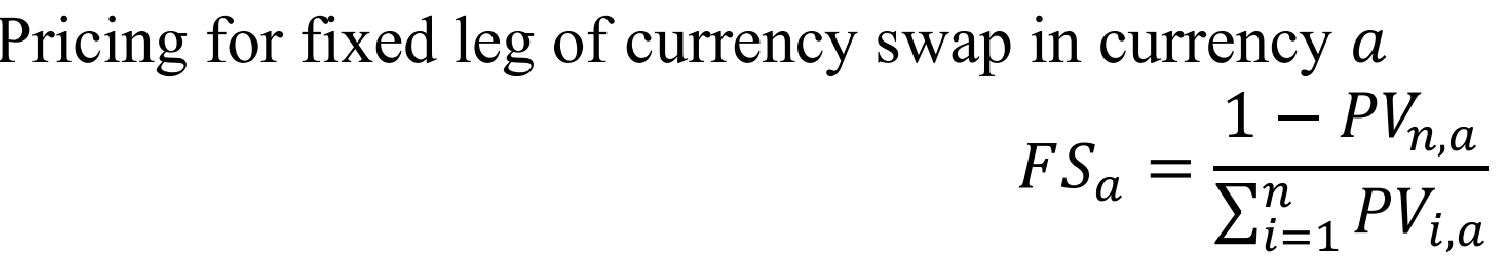
- 17Pricing Currency Swap
- 18Valuation of Currency Swap
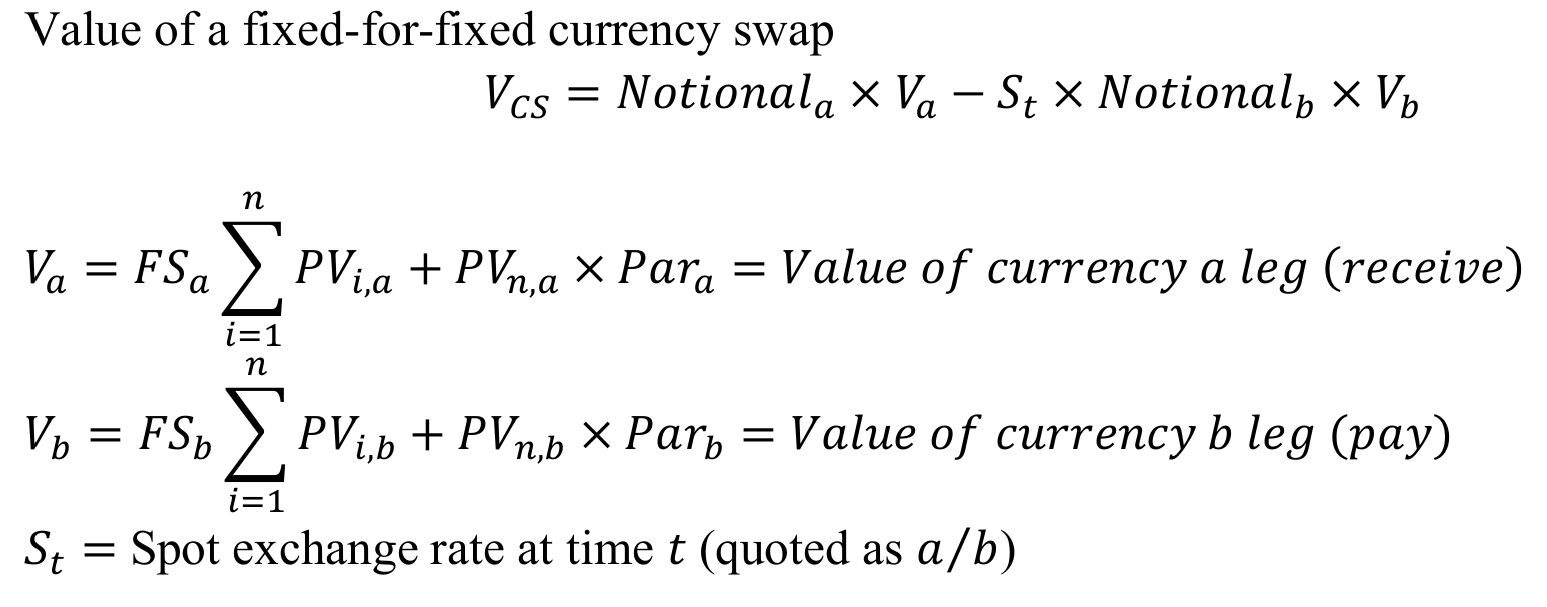
- 19Value of Equity Swap
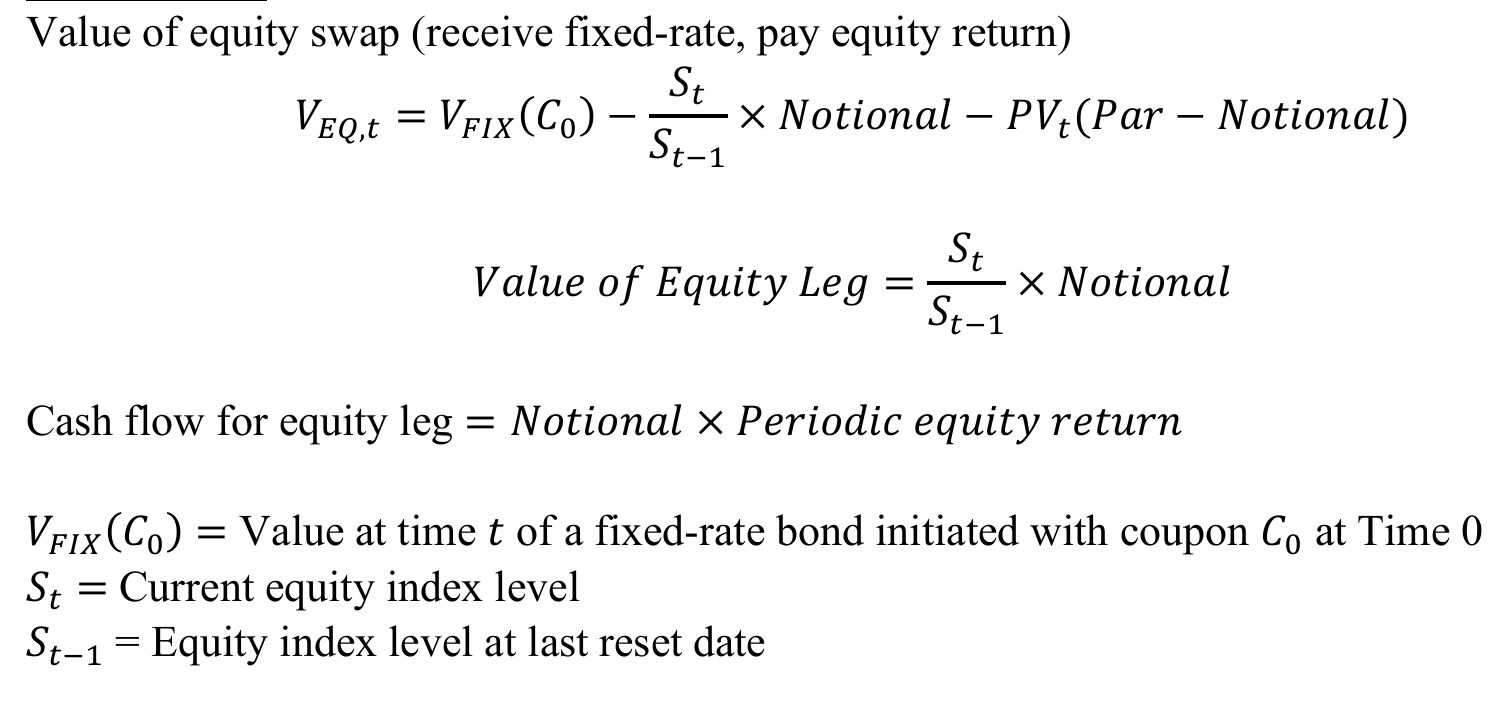
- 20Hedge Ratio
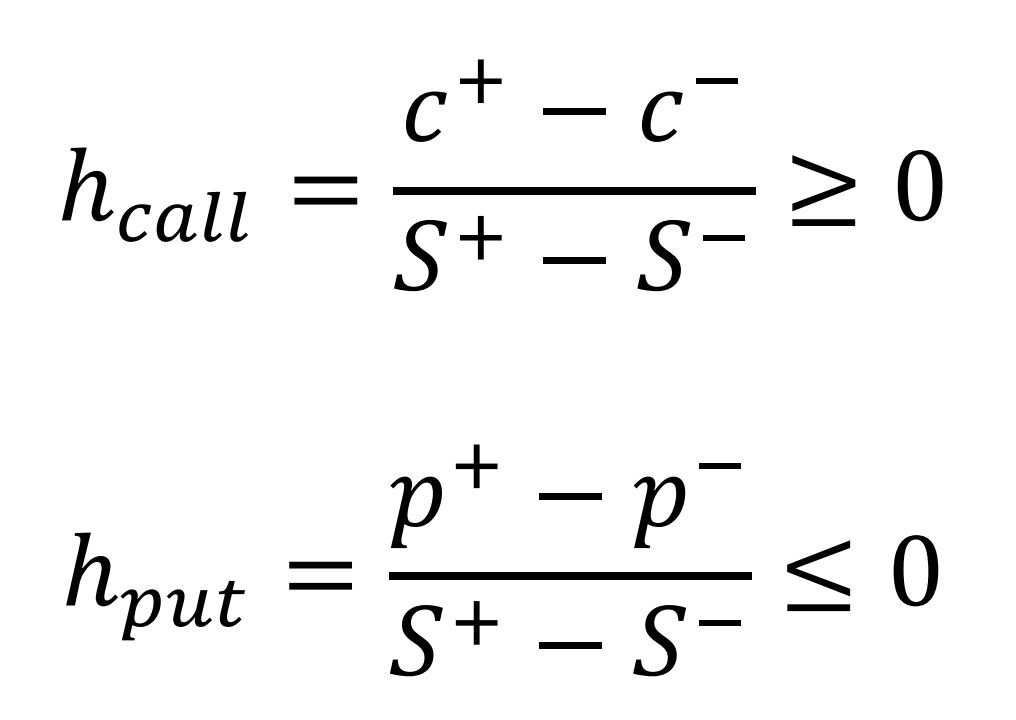
- 21No arbitrage approach valuing options
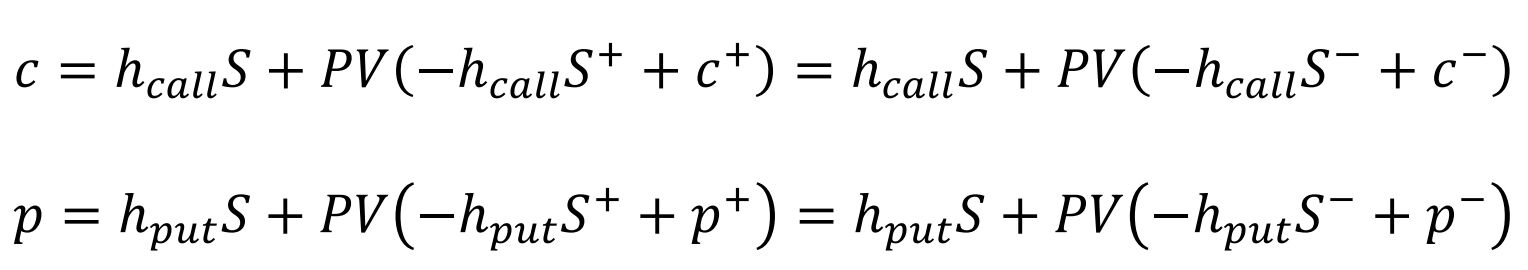
- 22Risk Free Probability of Default
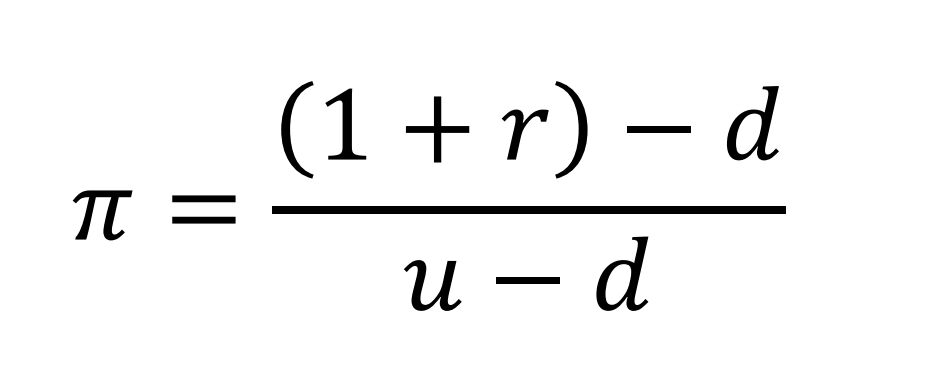
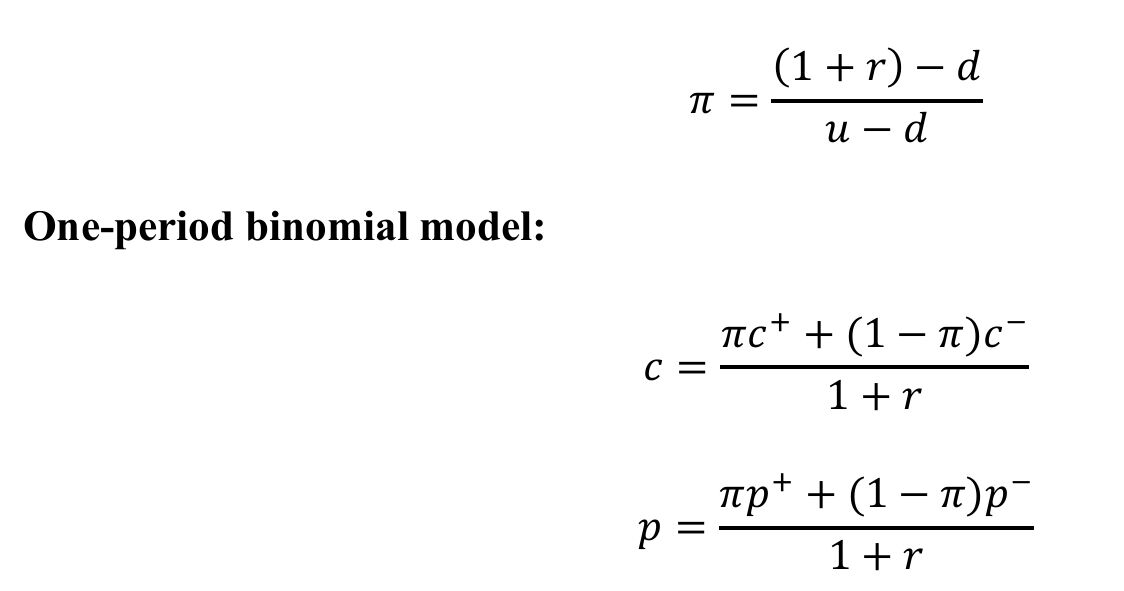
- 23One period binomial model option
- 24Two period binomial model options
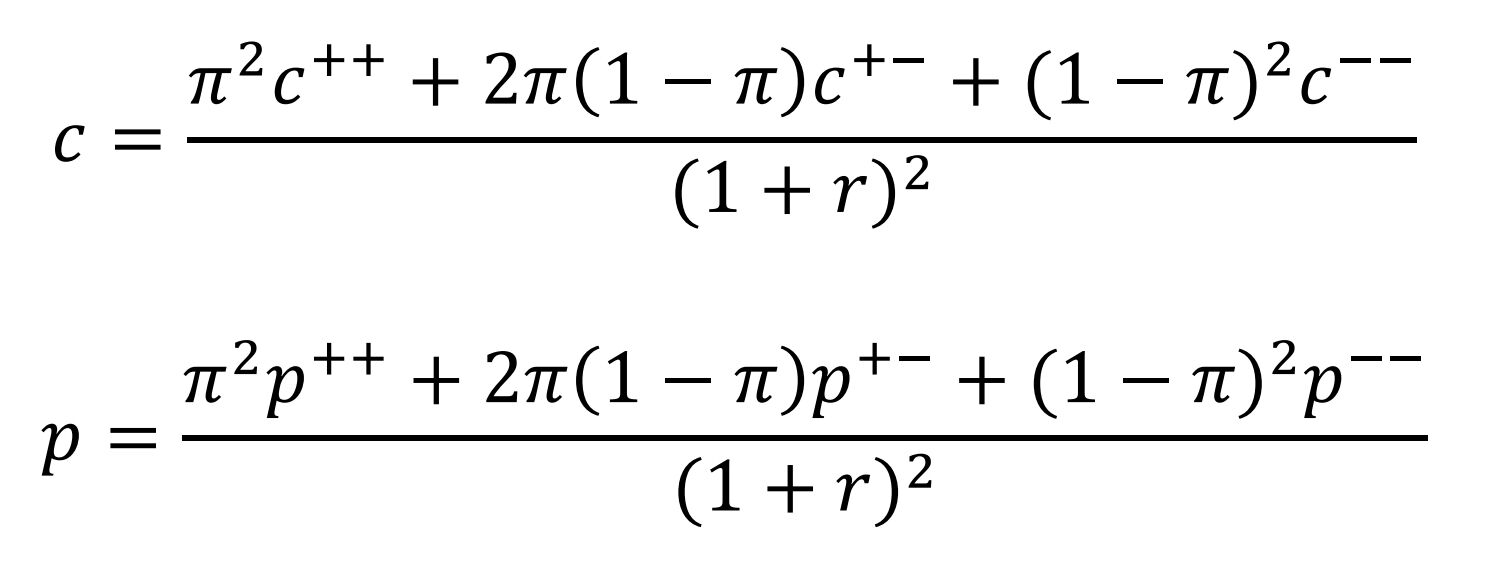
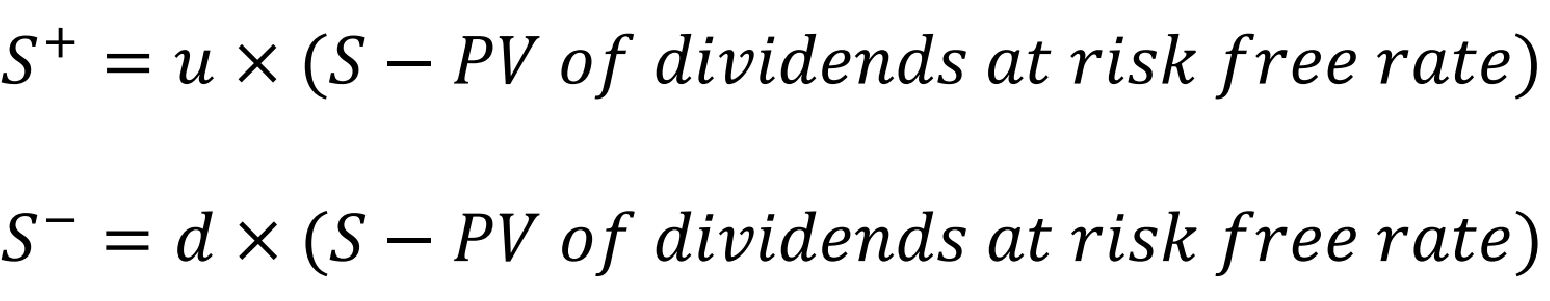
- 252 Period America Styled Call Option
- 26Black Schools Option Pricing Model
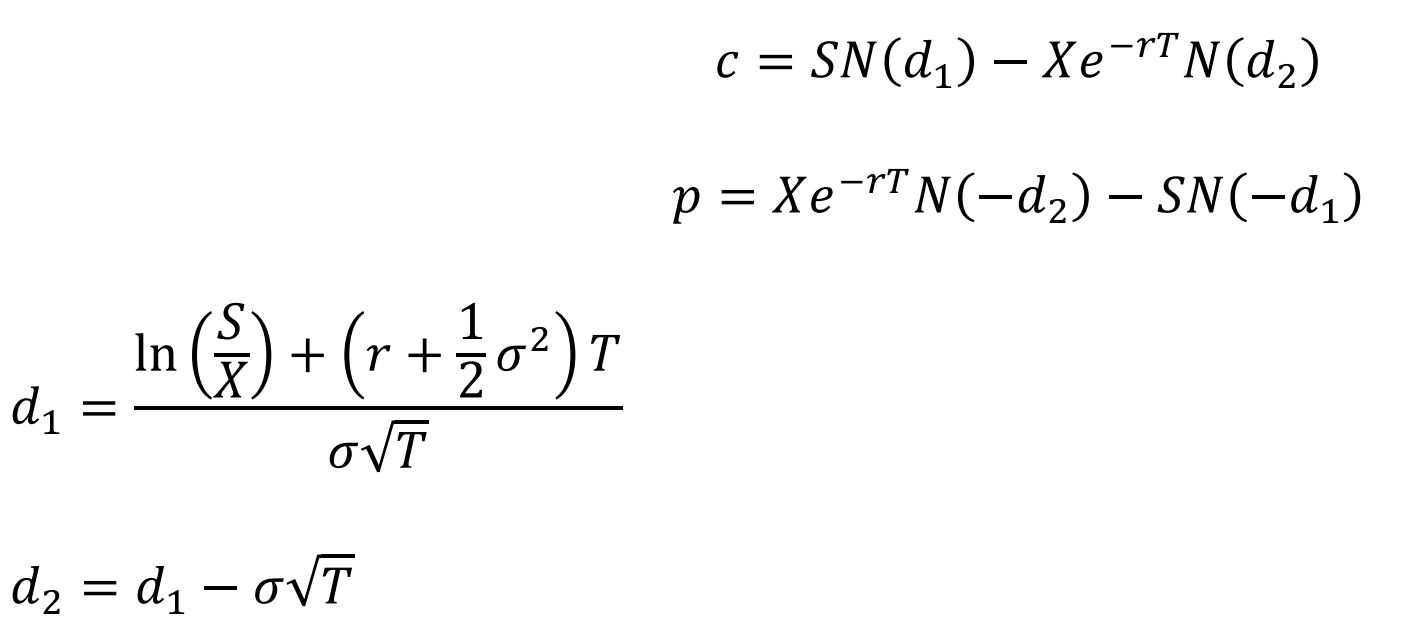
- 27Interpreting BSM
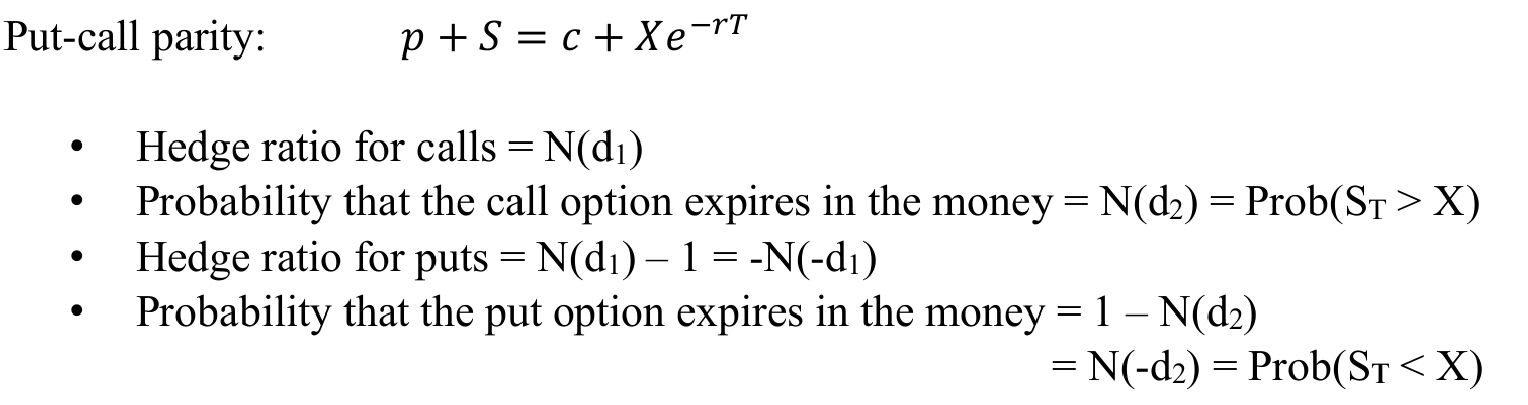
- 28BSM with carry benefits
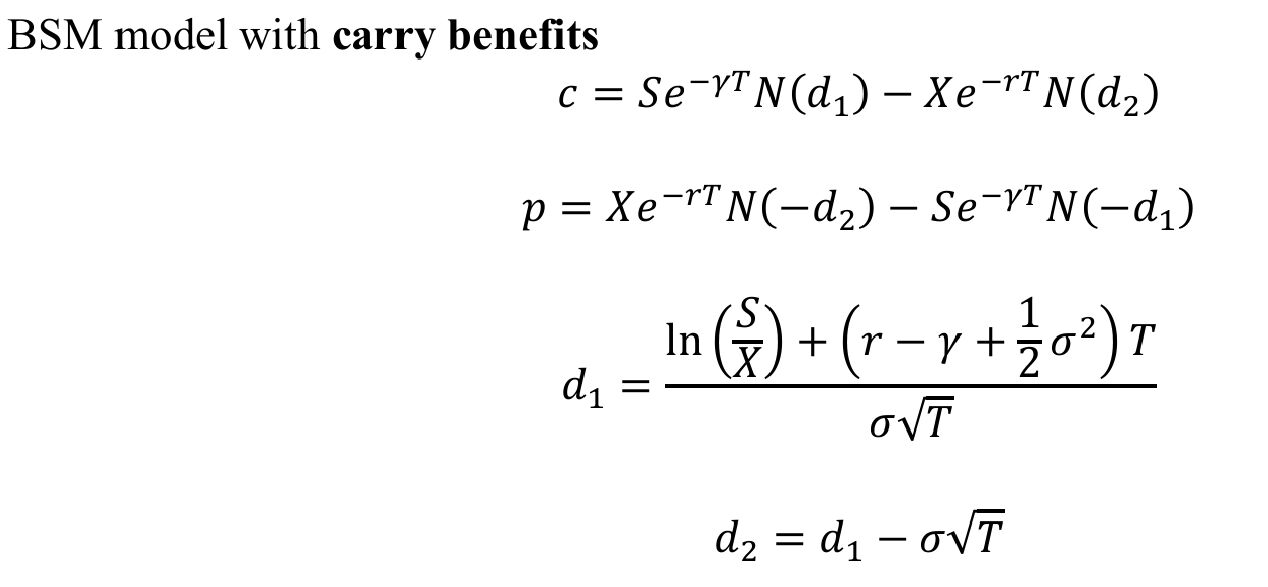
- 29Black Option Valuation Model: European Options on Futures
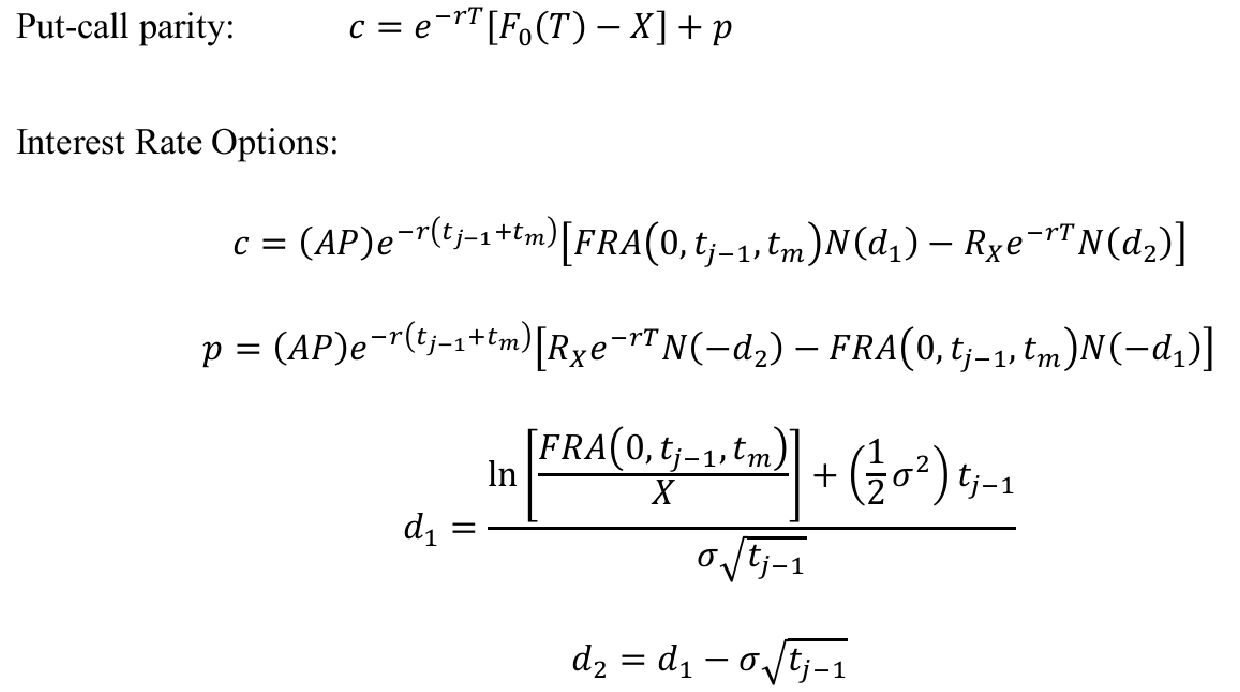
- 30BSM interest rate options
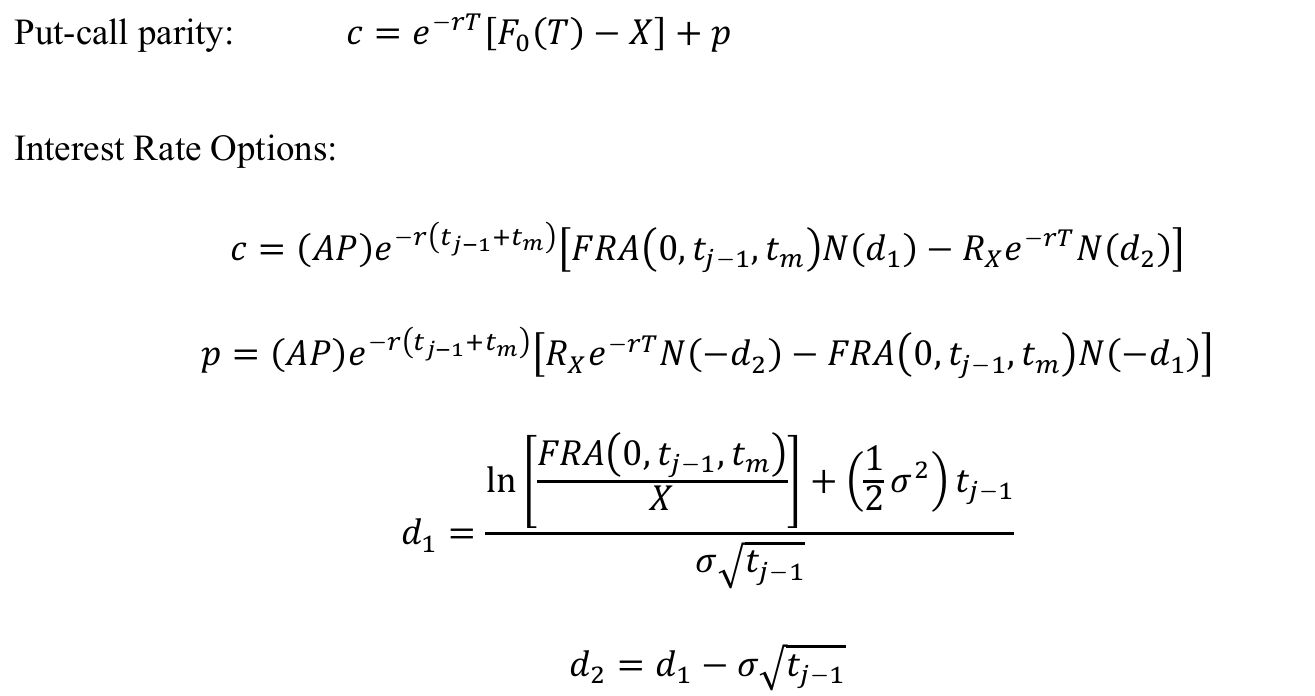
- 31Swaption
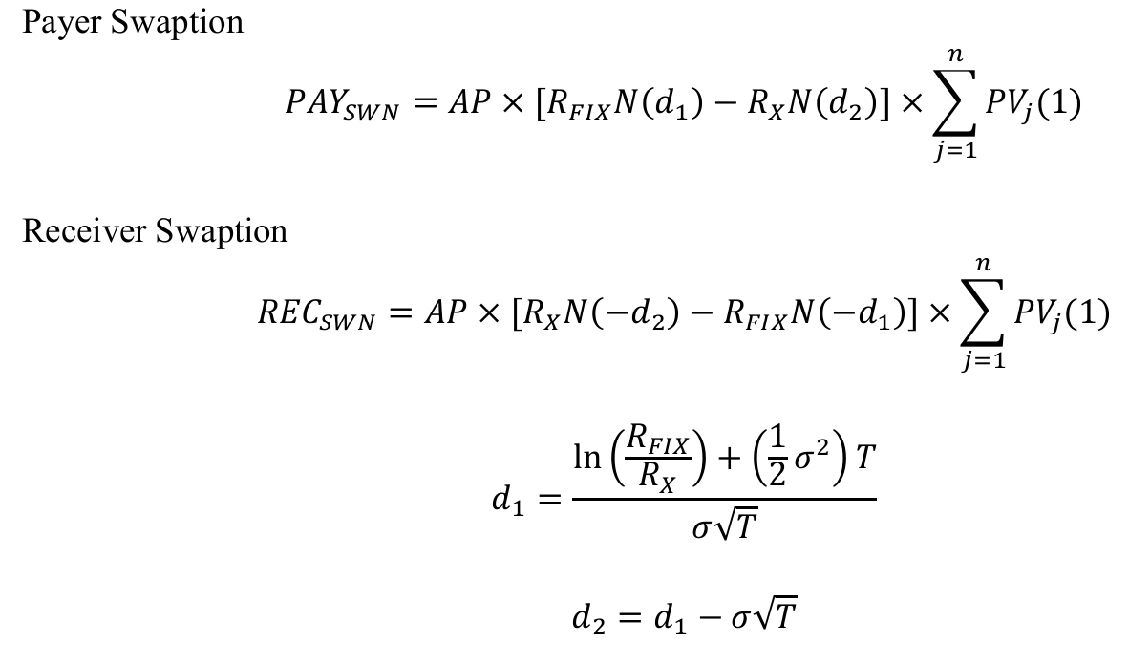
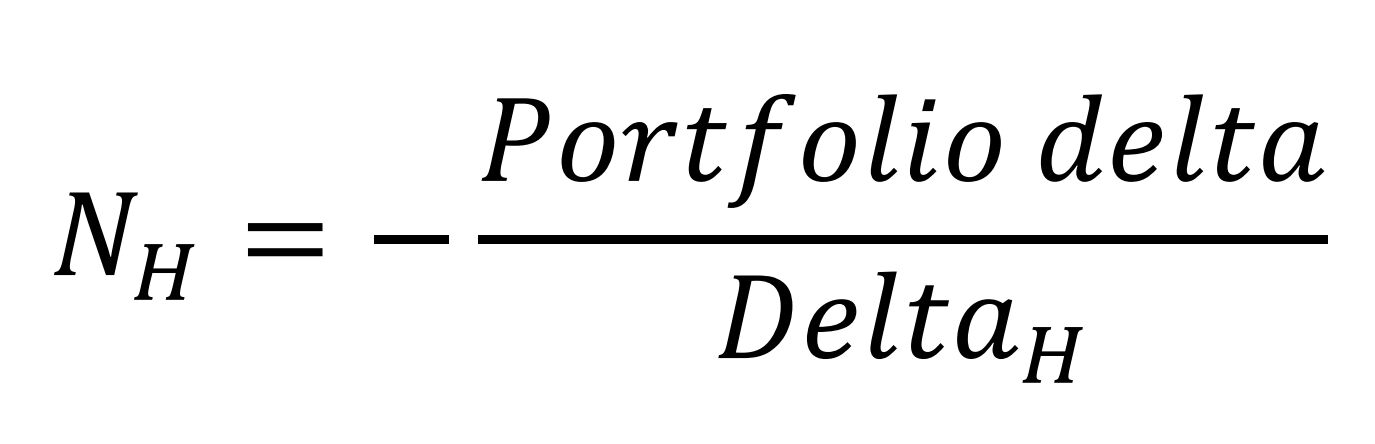
- 32Delta Hedging
- 33Valuation of Options with Greeks
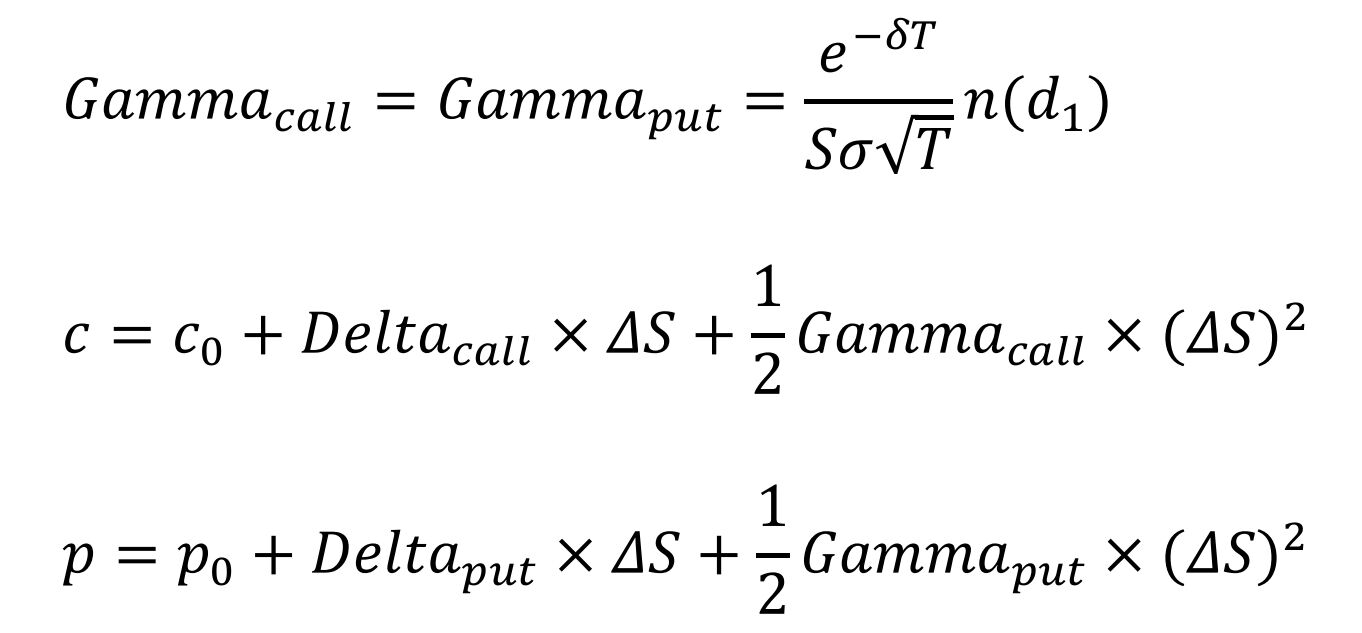
- 34Return on Real Estate Investment Index
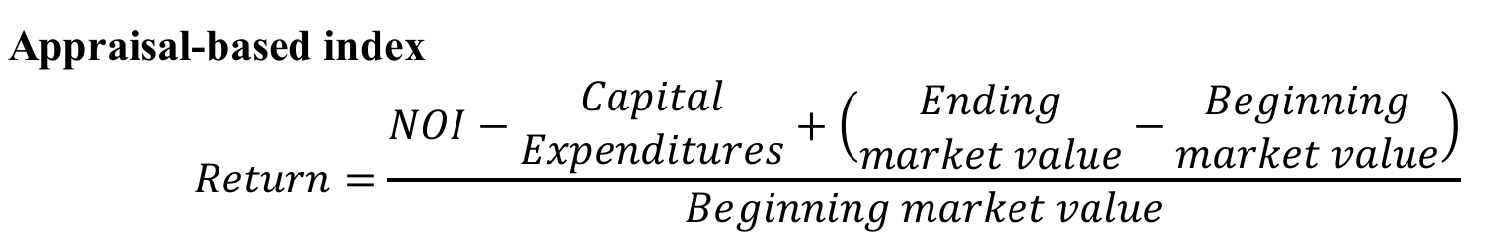
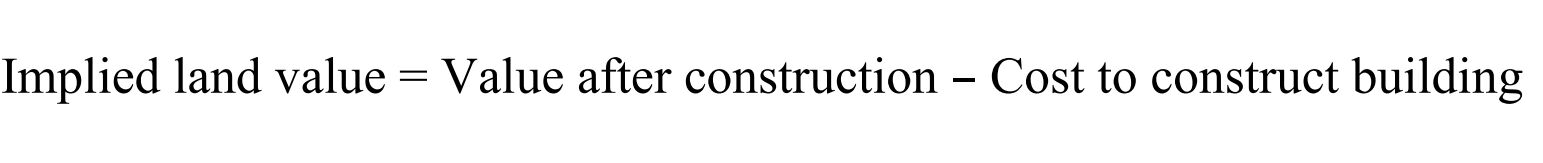
- 35Implied Land Value
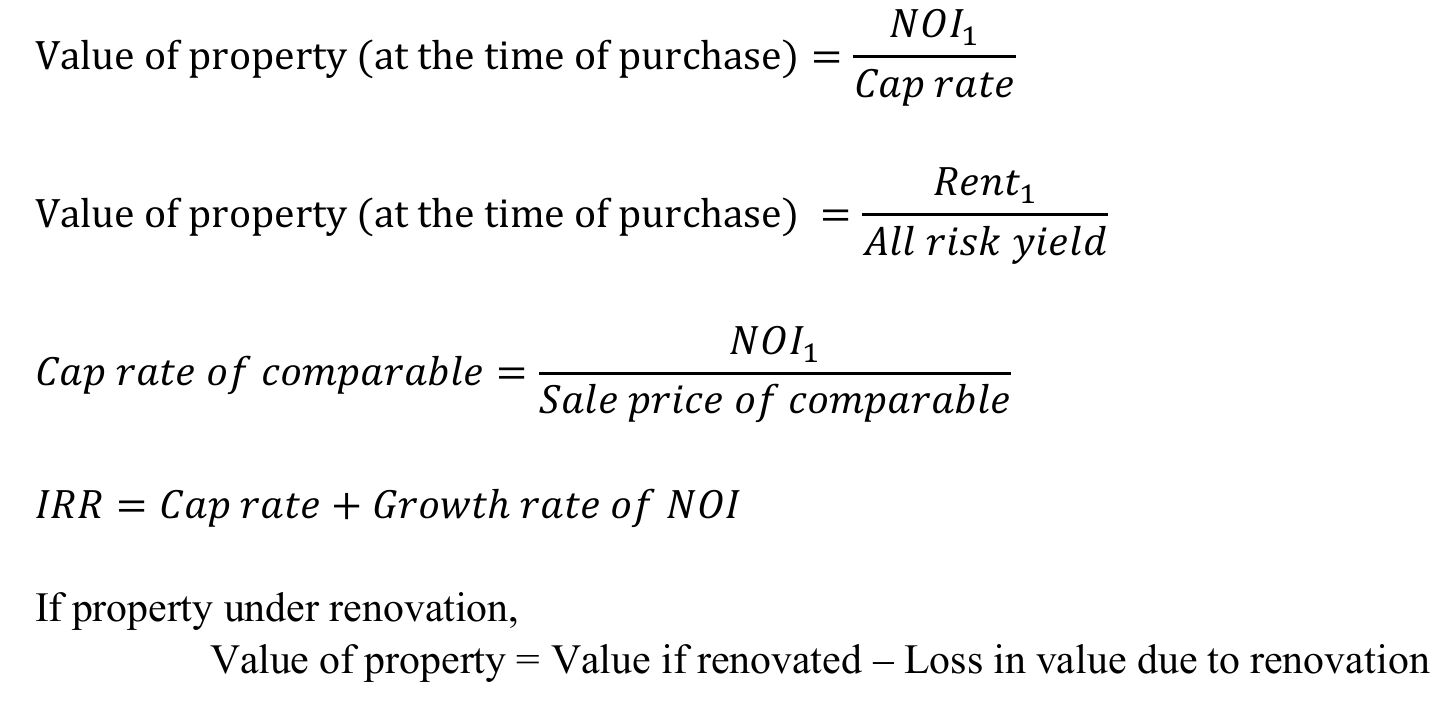
- 36Direct Capitalization Method
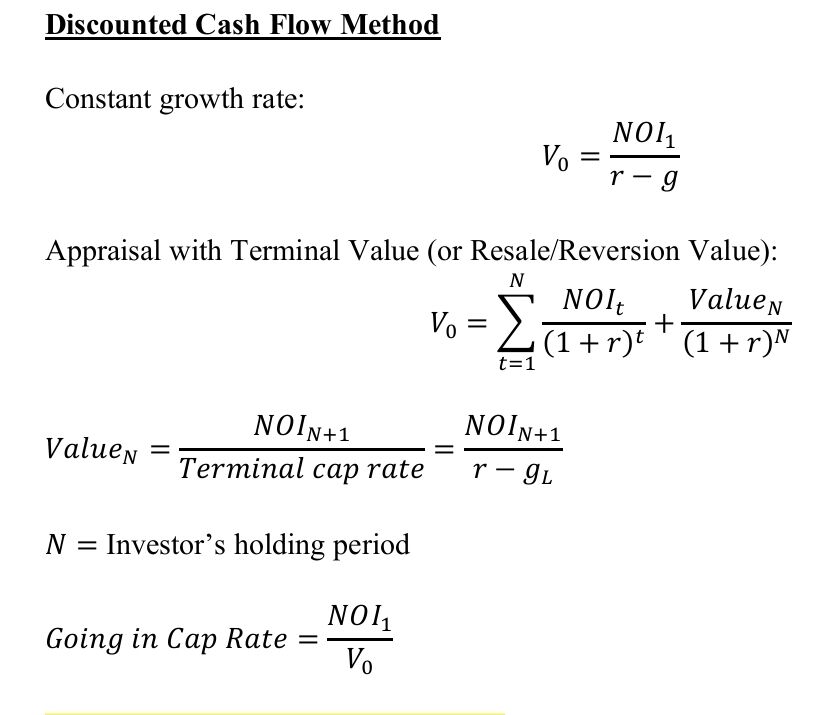
- 37Discounted Cash Flow Method Valuing real estate
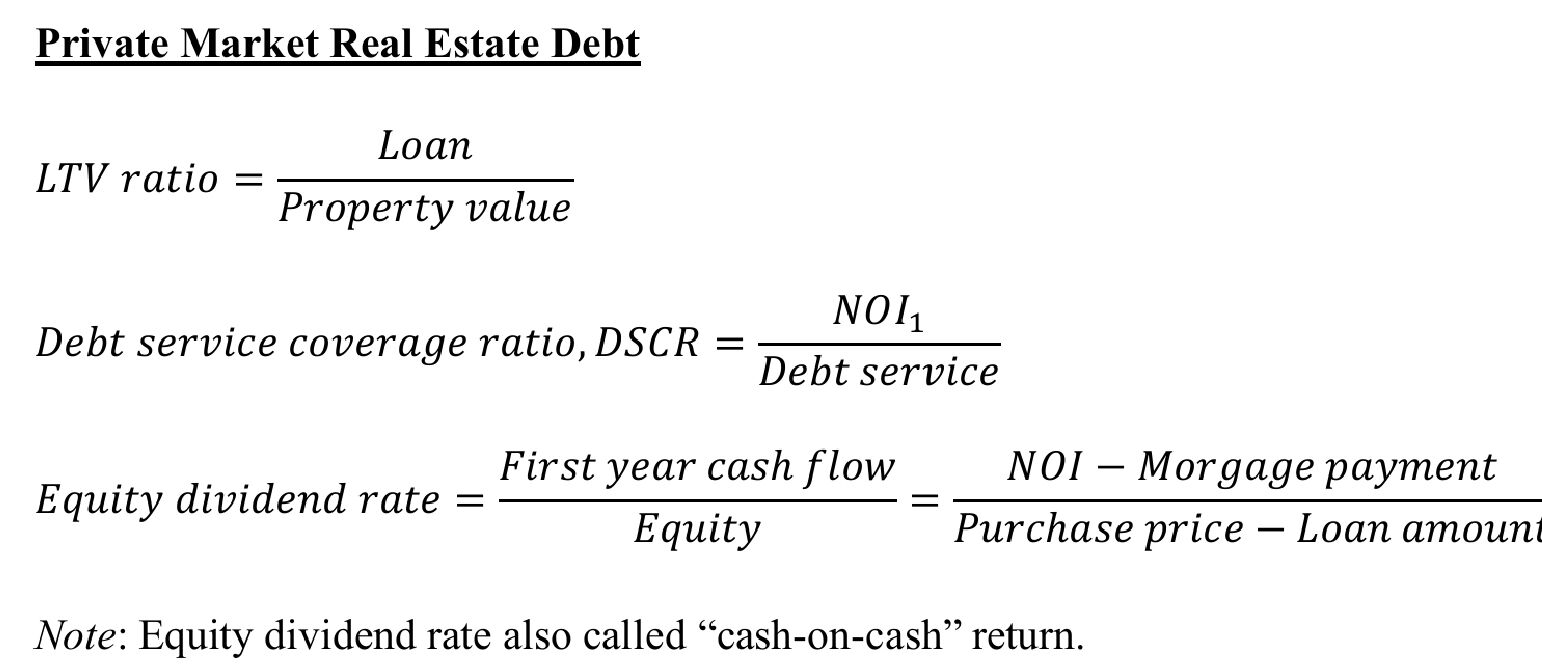
- 38Private Market Real Estate Debt
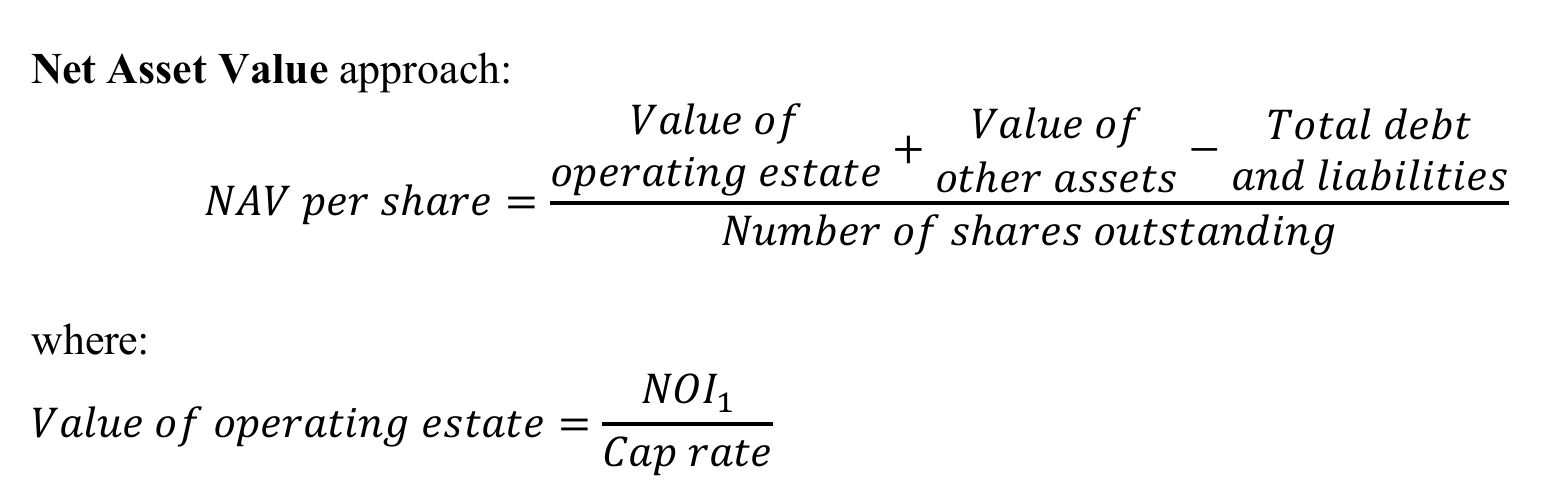
- 39NAV approach Real Estate
- 40Funds from operations (real estate)

- 41Adjusted Funds From Operations
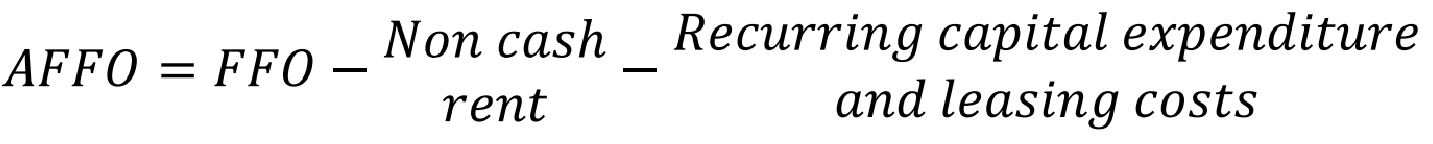
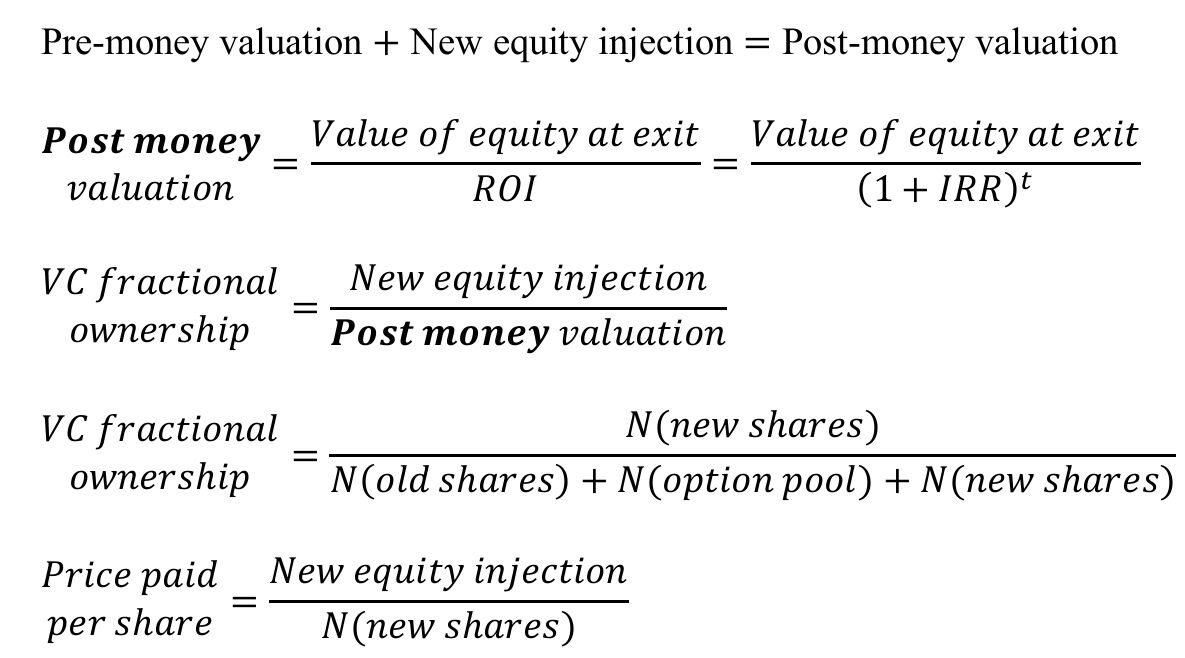
- 42Venture Capital Method
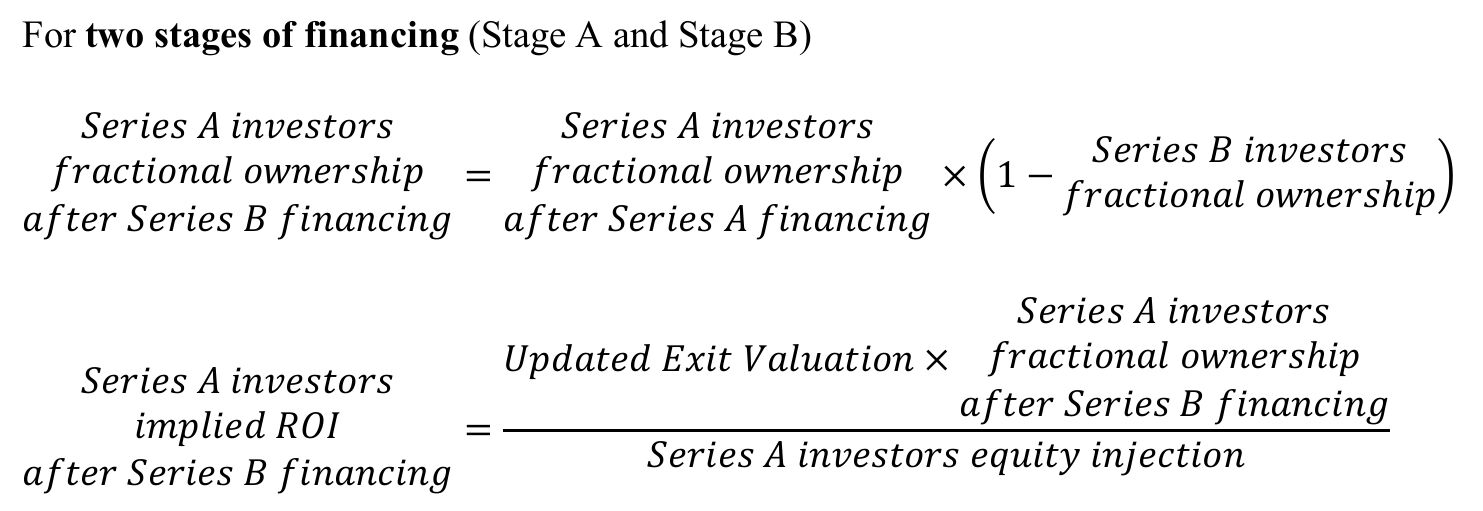
- 43Two Stages of Financing
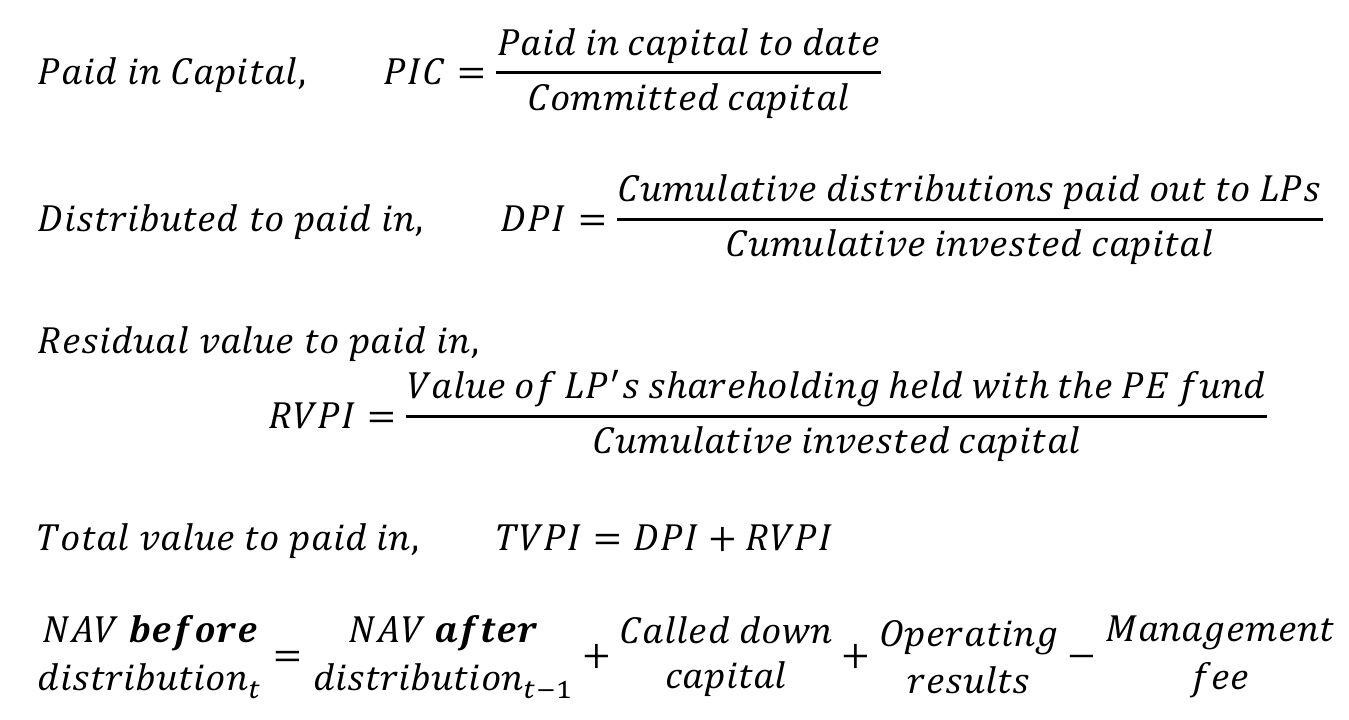
- 44Return Multiples for Private Equity Funds
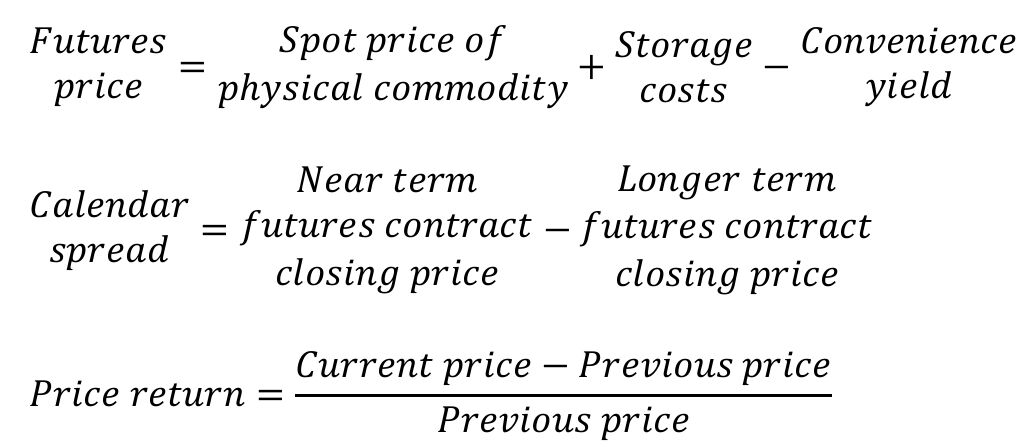
- 45Commodities Price Return
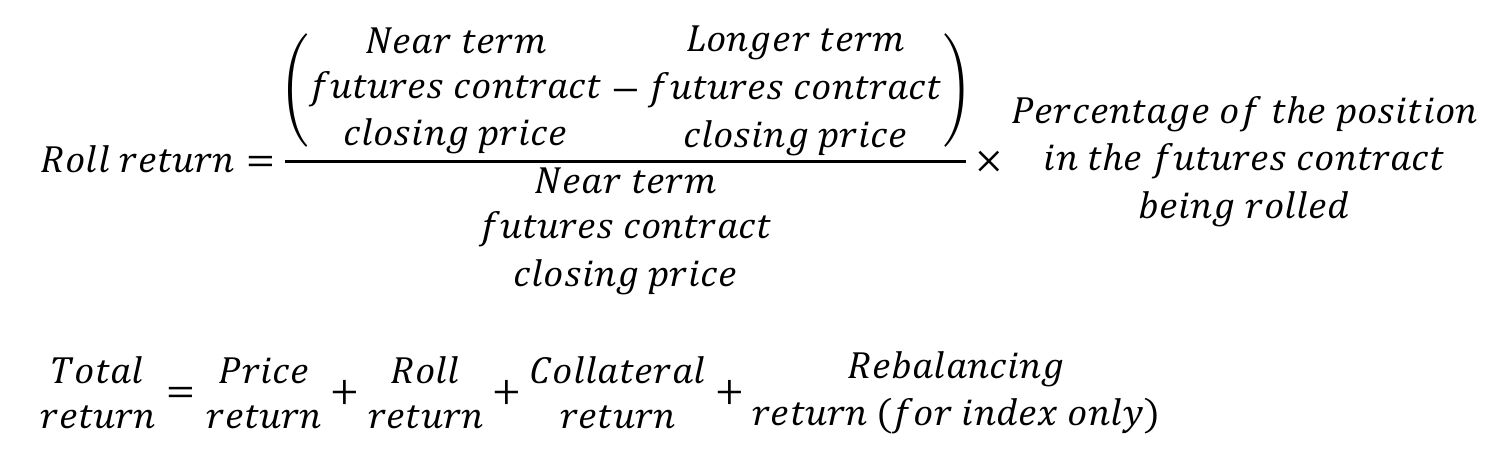
- 46Commodities Roll Return and Total Return
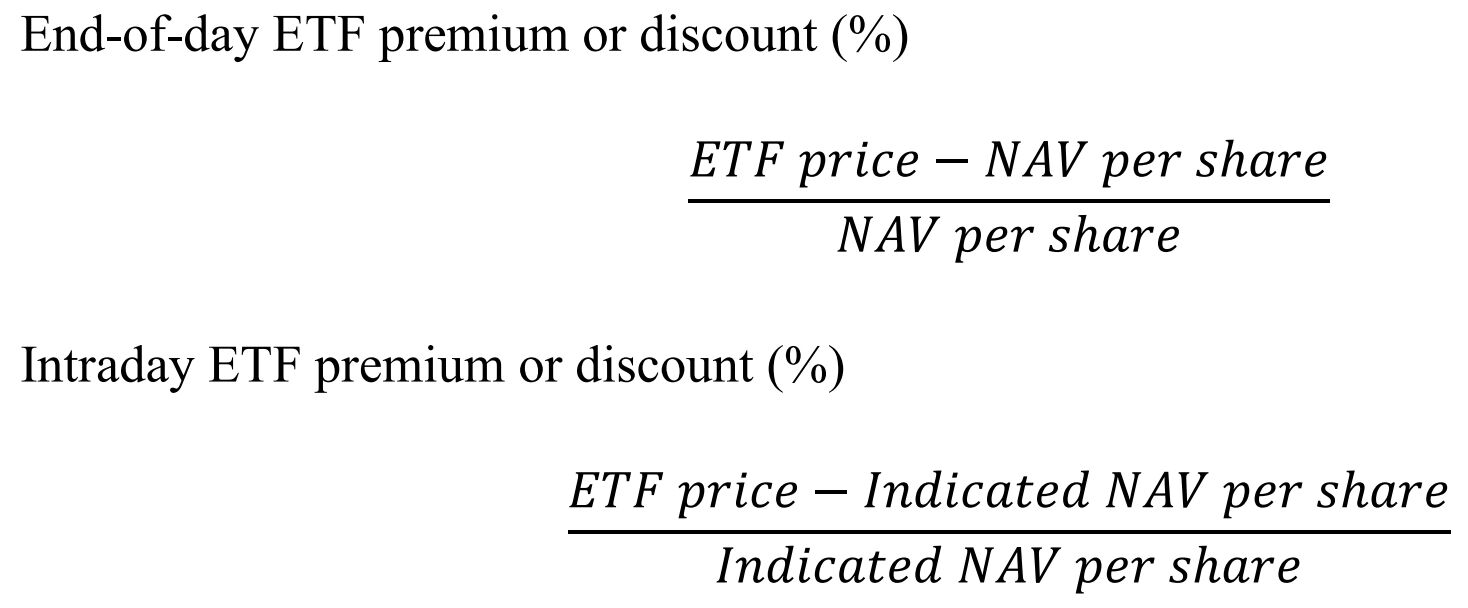
- 47ETF Premium or Discount
Information
- Description
- Second part to formulas
- Created by
- Dillon Onyemelukwe · Apr 2024
- Updated
- Apr 26, 2024
- Views
- 9
- Rating