
Flashcards
3.7 Analysing The Strategic Postion Of A Business - Yellow folder
Cards in this deck (56)
- 1Corporate AimsLong-term targets set to allow the business to develop and achieve it's mission.
- 2Internal influences on corporate objectives and decisions- Business ownership type
- Business culture, employees values and influence on decisions
- The company's current financial performance
- The management team's views, values, priorities and leadership style
- New leadership
- Firm's stages of it's life-cycle
- Stakeholder power
- Existing brand image and reputation - 3External influences on corporate objectives and decisionsSometimes outside the of the control of the business
- Government policy and intervention
- State of the economy
- Rivals Actions
- Market structure and changes
- Demographic and population changes
- Customer needs, wants, expectations, tastes and fashion. - 4Short-TermismFocusing on Short-Term decisions at the expense of Long-Term
- 5What might cause Short-Termisim?- Financial pressure/Cash shortage
- Pressure from shareholders to receive dividends
- Poor Publicity - 6Consquences of Short-Termisim- Conflict with shareholders
- Loss of profit
- May need extra finance
- No future investments - 7Stragetic Decision MakingDecision mad eat corporate, senior management or executive level. These decisions will impact the actions of each of the key departments.
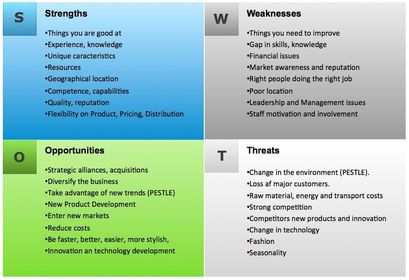
- 8What is a SWOT Analysis?A technique that's allows an organisation to assess its overall position. Its a method of analysing the current situation by examining the INTERAL strengths and weaknesses of the business and the EXTERNAL opportunities and threats.
- 9SWOT ANALYSIS
- 10Advantages of SWOT Analysis- Understand the business better
- Address weaknesses
- Deter threats
- Capitalise on opportunities
- Advantage of strengths
- Develop business goals and strategies - 11Disadvantages of SWOT Analysis- Doesn't prioritise issues
-Provide solutions or offer alternative options
- Generate too many ideas
- Produce a lot of information but not all of it is useful - 12Return On Capitial EmployedOperating Profit
------------------------------------- X 100
Capital Employed - 13Capital Structure ObjectivesHow a firm finances its overall operations and growth by using different sources of funds.
- 14What is Gearing?The percentage of capital invested into the business that has come from loans.
- 15Gearing %Non-Current Liabilities
--------------------------------------------------X100
Share Capital + Non-Current Liabilities - 16Rewards of High Gearing- Opportunities to expand
- Able to respond quickly in a market
- Low interest rates - 17Risks of High Gearing- Not being able to repay
- No extra money
-High interest rates
- Struggle for future loans - 18Non-Current Liabilites- Loans (long term)
- Mortgages
- Debentures - 19Share Capital+ Doesn't need to be repaid
- Dividends
- Ownership
- Dilution - 20Loans+ Instant
+ Control and Ownership
- Has to be repaid with interest - 21What is a Balance Sheet?A document describing the financial position of a company at a particular point in time. A financial snapshot
- 22Non-Current assetsWhat the business owns with a lifespan of more than a year. They are used repeatedly as part of the firm's operations and will not regularly be sold.
- 23Current AssetsAssets owned by the business that are likely to be turned into cash within one year. These assets constantly change form.
- 24Current liabilitiesShort-term debts of the business, will have to be repaid within one year
- 25Long-term liabilitiesDebts that needs to be repaid, but not within a year. Also known as creditors.
- 26Capital and reservesShows how the assets and businesses have been financed.
- 27Net current assetsAlso known as working capital, this figure is important as it gives an idea of the firms liquidity.
- 28LiquidityA firms ability to pay its short term loans
- 29Current ratioCurrent Assets : Current Liabilities
- 30Net assetsThe figure shows what the business is worth at the moment the balance sheet was produced.
(Non-current assets + current assets)
-
(Non-current liabilities + current liabilities)
it should always be the same as total equity. - 31What is an income statement?This statement describes the income and expenditure of a business over a period of time, usually a year.
- 32Income statement
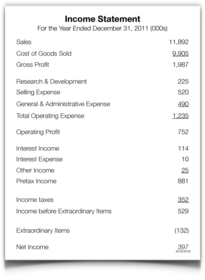
- 33RevenueTurnover or sales income generated from sales
- 34Cost of salesCosts linked directly to the production of the product or service. E.g. Raw materials and variable costs
- 35Gross profitRevenue minus cost of sales. Gross profit shows how efficiently a business is converting its raw material or stock into finished products.
- 36Expenses (overheads)Indirect costs that are not directly related to producing the product or service.
- 37Operating profitGross profit - expenses
The profit earned from normal trading activities minus the costs involved in carrying out these activities. - 38Exceptional itemsItems that have a one-off effect on profits. These are listed separately from other costs and sources of income as they aren't part of the business's normal activities and cannot be expected to happen again.
- 39Finance incomeAny interest paid to the company on money lent or saved.
- 40Finance expensesAny payments of interest on loans held.
- 41Profit before taxOperating profit - finance expenses
(plus any finance income) - 42Profit for the yearProfit before tax - taxation
- 43Earnings per shareProfit for the period/number of shares
- 44What is ratio analysis?A technique used to analyse a business's financial performance by comparing different pieces of data from company accounts.
- 45Uses of ratio analysis- Gives a more in-depth look at a company's financial performance.
- Allows stakeholders to assess an organisation's performance.
- Allows stakeholders to place key figures into context and provides good quality information to aid decision making.
- Helps stakeholders to better understand a firm's performance in a number of key assets. - 46Limitations of ratio analysis- Historical data, does not mean results will carry onto the future
- Operational changes
- Interpretation
- Point in time - 47ProfitablyMost firms' main aim is to make a profit for the owners.
- 48How might a firm measure its size?Market Share
- 49Gross profit margin %Gross Profit/Total revenue
X 100 - 50Operating profit margin %Operating profit/total revenue
X 100 - 51What does ROCE do?Lets owners or potential investors understand how efficient the business is at producing profit based on the capital invested in the business.
- 52Icosts of goods sold/average inventory held
measures how quickly inventory is converted into sales - 53Receivables daysReceivables/revenue X 365
- 54Payable daysPayables days/ cost of sales X 365
- 55What are the main ways a business can measure its performance and success?- Labour productivity
- Capacity utilization
- Unit Cost
- Profit
- ROCE
- Current ratio analysis
- Market capital
- Working capital - 56—
Information
- Description
- A-Level A-Level Business Studies Flashcards on 3.7 Analysing The Strategic Postion Of A Business - Yellow folder, created by Hollie Ferris on 27/09/2016.
- Created by
- Hollie Ferris
- Views
- 19
- Rating