
Mind map
Marketing Regulatory Provisions
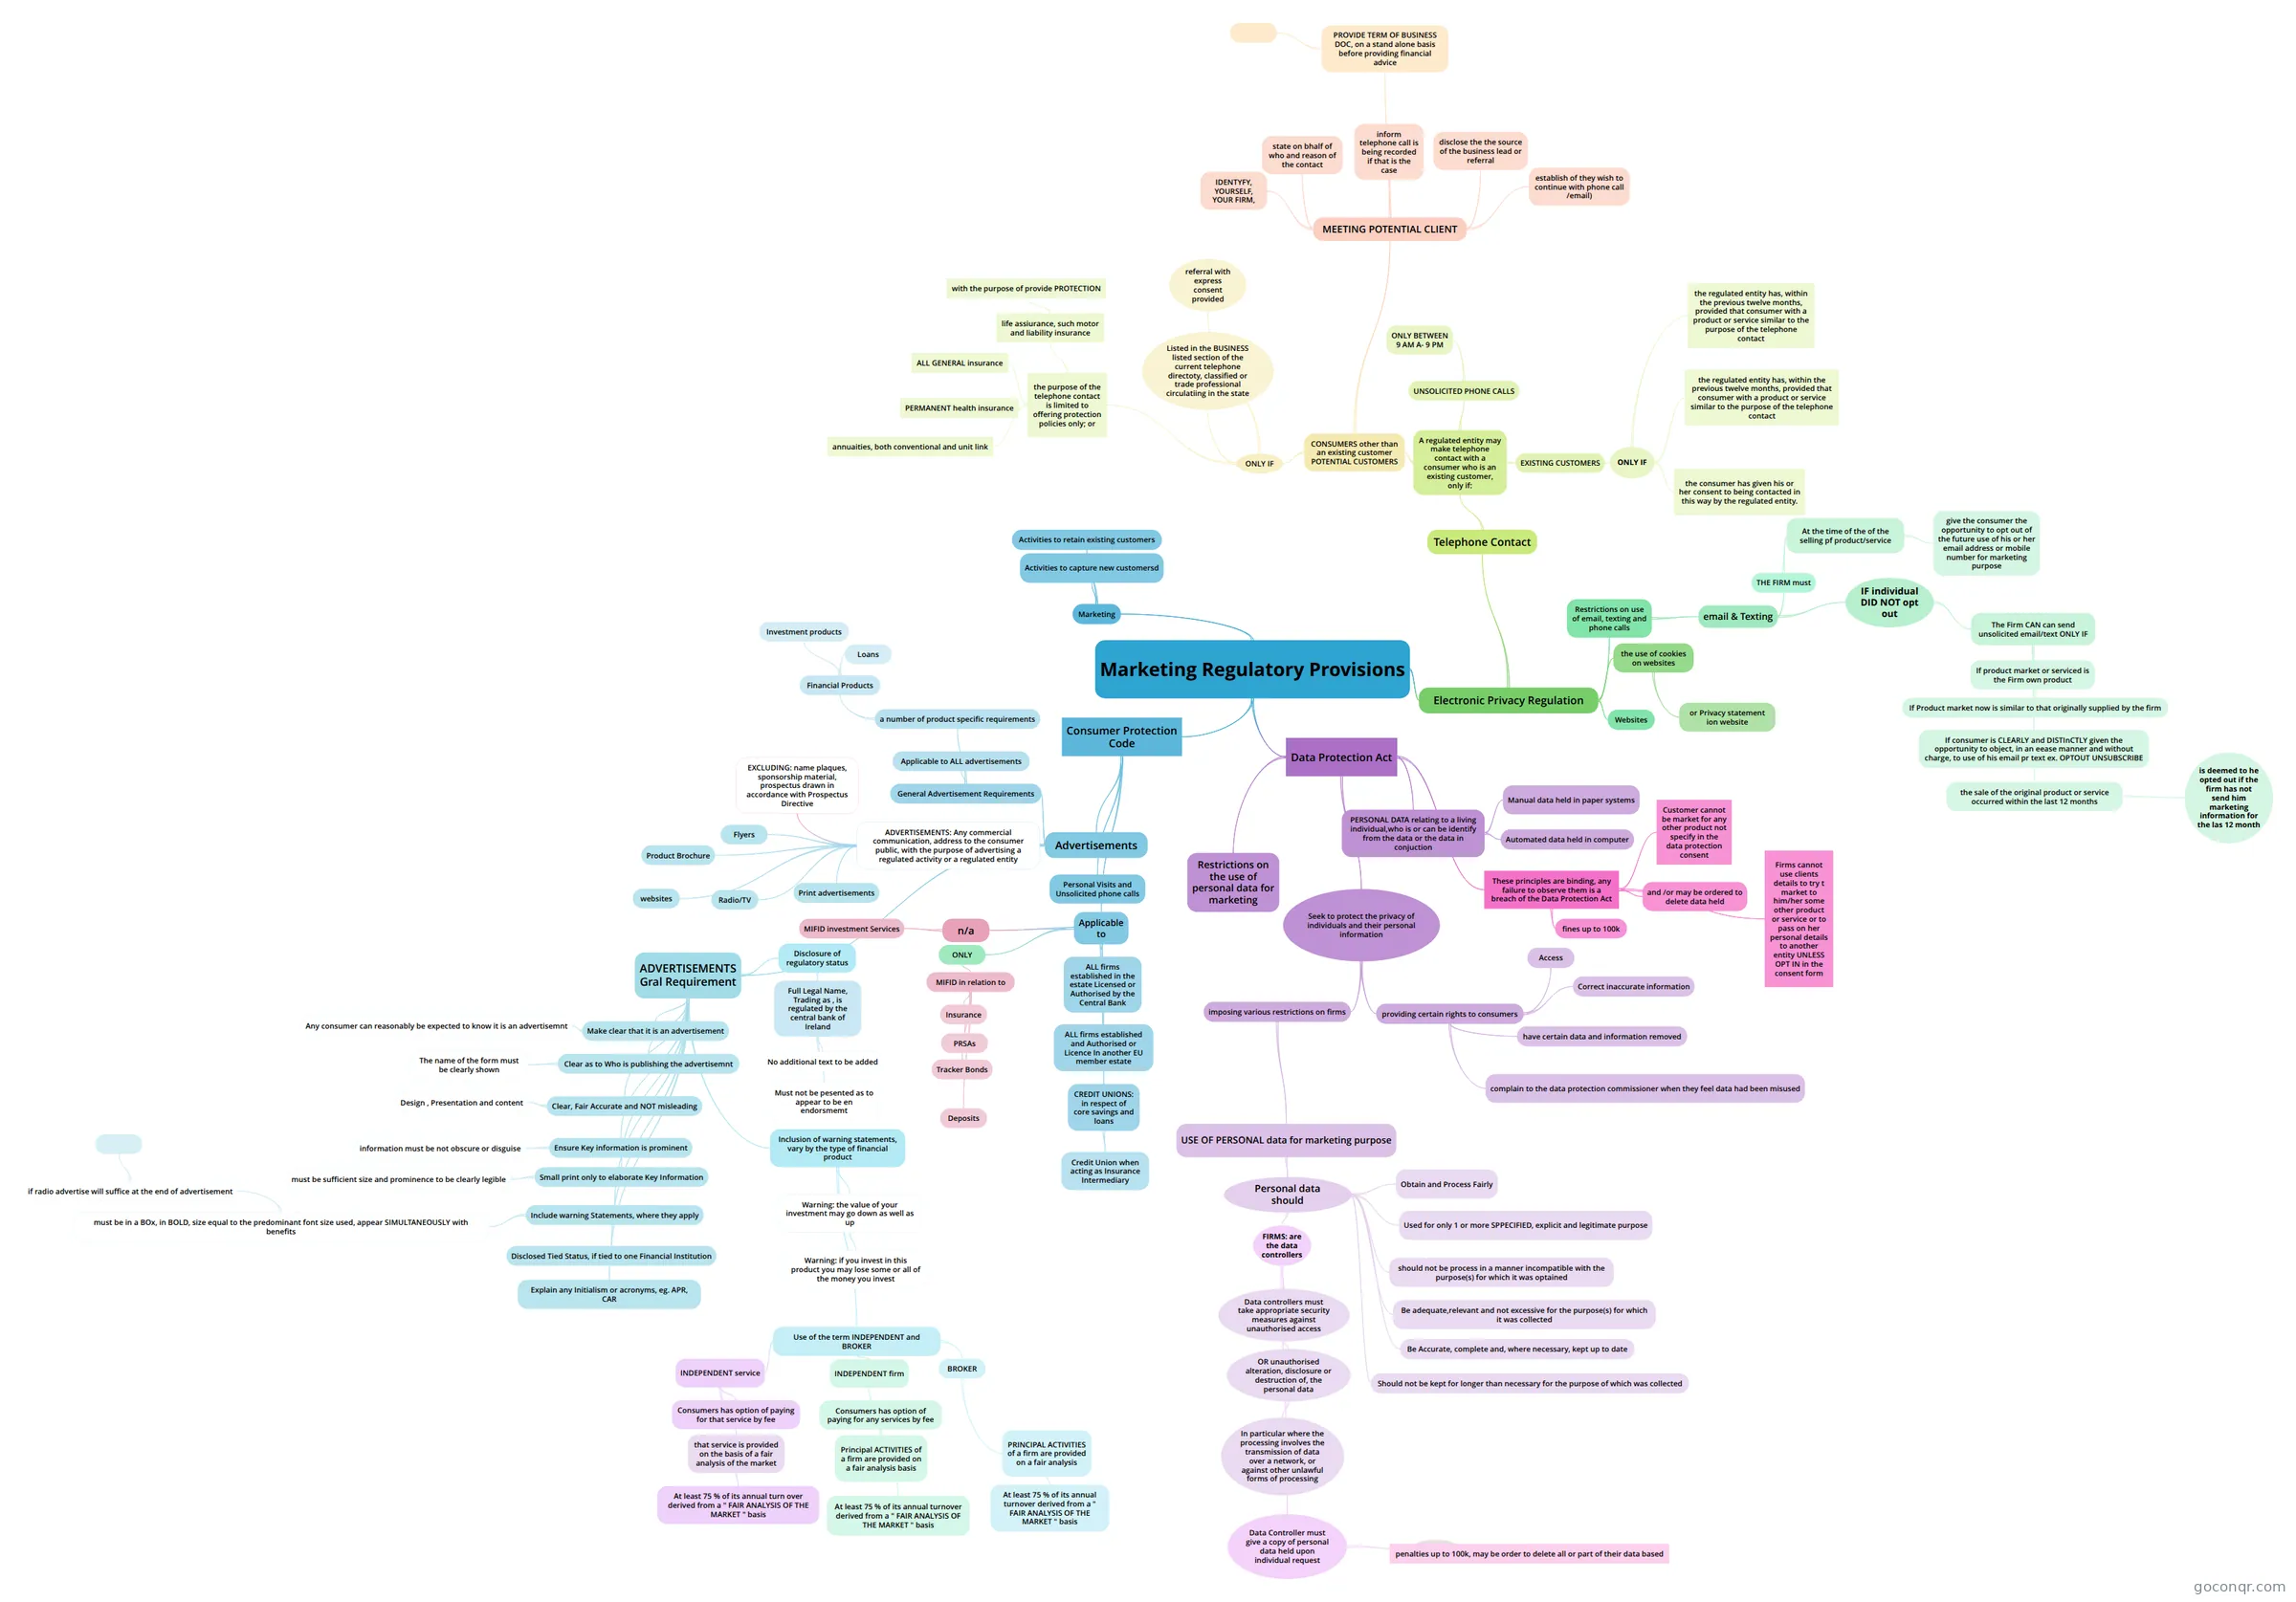
Mind map: Marketing regulatory provisions
Map content
Marketing Regulatory Provisions
Marketing
- Activities to capture new customersd
- Activities to retain existing customers
Consumer Protection Code
- Advertisements
- General Advertisement Requirements
- Applicable to ALL advertisements
- a number of product specific requirements
- Financial Products
- Loans
- Investment products
- Financial Products
- ADVERTISEMENTS: Any commercial communication, address to the consumer public, with the purpose of advertising a regulated activity or a regulated entity
- EXCLUDING: name plaques, sponsorship material, prospectus drawn in accordance with Prospectus Directive
- Print advertisements
- Radio/TV
- Flyers
- Product Brochure
- websites
- ADVERTISEMENTS Gral Requirement
- Make clear that it is an advertisement
- Any consumer can reasonably be expected to know it is an advertisemnt
- Clear as to Who is publishing the advertisemnt
- The name of the form must be clearly shown
- Clear, Fair Accurate and NOT misleading
- Design , Presentation and content
- Ensure Key information is prominent
- information must be not obscure or disguise
- Small print only to elaborate Key Information
- must be sufficient size and prominence to be clearly legible
- Include warning Statements, where they apply
- must be in a BOx, in BOLD, size equal to the predominant font size used, appear SIMULTANEOUSLY with benefits
- if radio advertise will suffice at the end of advertisement
- if radio advertise will suffice at the end of advertisement
- must be in a BOx, in BOLD, size equal to the predominant font size used, appear SIMULTANEOUSLY with benefits
- Disclosed Tied Status, if tied to one Financial Institution
- Explain any Initialism or acronyms, eg. APR, CAR
- Disclosure of regulatory status
- Full Legal Name, Trading as , is regulated by the central bank of Ireland
- No additional text to be added
- Must not be pesented as to appear to be en endorsmemt
- Full Legal Name, Trading as , is regulated by the central bank of Ireland
- Inclusion of warning statements, vary by the type of financial product
- Warning: the value of your investment may go down as well as up
- Warning: if you invest in this product you may lose some or all of the money you invest
- Use of the term INDEPENDENT and BROKER
- INDEPENDENT service
- that service is provided on the basis of a fair analysis of the market
- At least 75 % of its annual turn over derived from a " FAIR ANALYSIS OF THE MARKET " basis
- Consumers has option of paying for that service by fee
- that service is provided on the basis of a fair analysis of the market
- INDEPENDENT firm
- Principal ACTIVITIES of a firm are provided on a fair analysis basis
- Consumers has option of paying for any services by fee
- At least 75 % of its annual turnover derived from a " FAIR ANALYSIS OF THE MARKET " basis
- Consumers has option of paying for any services by fee
- Principal ACTIVITIES of a firm are provided on a fair analysis basis
- BROKER
- PRINCIPAL ACTIVITIES of a firm are provided on a fair analysis
- At least 75 % of its annual turnover derived from a " FAIR ANALYSIS OF THE MARKET " basis
- PRINCIPAL ACTIVITIES of a firm are provided on a fair analysis
- INDEPENDENT service
- Warning: the value of your investment may go down as well as up
- Make clear that it is an advertisement
- General Advertisement Requirements
- Personal Visits and Unsolicited phone calls
- Applicable to
- n/a
- MIFID investment Services
- ONLY
- MIFID in relation to
- Insurance
- PRSAs
- Tracker Bonds
- Deposits
- MIFID in relation to
- ALL firms established in the estate Licensed or Authorised by the Central Bank
- ALL firms established and Authorised or Licence In another EU member estate
- CREDIT UNIONS: in respect of core savings and loans
- Credit Union when acting as Insurance Intermediary
- n/a
- Advertisements
Data Protection Act
- Restrictions on the use of personal data for marketing
- Seek to protect the privacy of individuals and their personal information
- imposing various restrictions on firms
- USE OF PERSONAL data for marketing purpose
- Personal data should
- Obtain and Process Fairly
- Used for only 1 or more SPPECIFIED, explicit and legitimate purpose
- should not be process in a manner incompatible with the purpose(s) for which it was optained
- Be adequate,relevant and not excessive for the purpose(s) for which it was collected
- Be Accurate, complete and, where necessary, kept up to date
- Should not be kept for longer than necessary for the purpose of which was collected
- FIRMS: are the data controllers
- Data controllers must take appropriate security measures against unauthorised access
- OR unauthorised alteration, disclosure or destruction of, the personal data
- In particular where the processing involves the transmission of data over a network, or against other unlawful forms of processing
- OR unauthorised alteration, disclosure or destruction of, the personal data
- Data Controller must give a copy of personal data held upon individual request
- breaches
- penalties up to 100k, may be order to delete all or part of their data based
- breaches
- Data controllers must take appropriate security measures against unauthorised access
- Personal data should
- USE OF PERSONAL data for marketing purpose
- providing certain rights to consumers
- Access
- Correct inaccurate information
- have certain data and information removed
- complain to the data protection commissioner when they feel data had been misused
- imposing various restrictions on firms
- PERSONAL DATA relating to a living individual,who is or can be identify from the data or the data in conjuction
- Automated data held in computer
- Manual data held in paper systems
- These principles are binding, any failure to observe them is a breach of the Data Protection Act
- fines up to 100k
- and /or may be ordered to delete data held
- Customer cannot be market for any other product not specify in the data protection consent
- Firms cannot use clients details to try t market to him/her some other product or service or to pass on her personal details to another entity UNLESS OPT IN in the consent form
Electronic Privacy Regulation
- Restrictions on use of email, texting and phone calls
- email & Texting
- THE FIRM must
- At the time of the of the selling pf product/service
- give the consumer the opportunity to opt out of the future use of his or her email address or mobile number for marketing purpose
- At the time of the of the selling pf product/service
- IF individual DID NOT opt out
- The Firm CAN can send unsolicited email/text ONLY IF
- If product market or serviced is the Firm own product
- If Product market now is similar to that originally supplied by the firm
- If consumer is CLEARLY and DISTInCTLY given the opportunity to object, in an eease manner and without charge, to use of his email pr text ex. OPTOUT UNSUBSCRIBE
- the sale of the original product or service occurred within the last 12 months
- is deemed to he opted out if the firm has not send him marketing information for the las 12 month
- The Firm CAN can send unsolicited email/text ONLY IF
- THE FIRM must
- email & Texting
- Websites
- the use of cookies on websites
- or Privacy statement ion website
- Telephone Contact
- A regulated entity may make telephone contact with a consumer who is an existing customer, only if:
- EXISTING CUSTOMERS
- ONLY IF
- the regulated entity has, within the previous twelve months, provided that consumer with a product or service similar to the purpose of the telephone contact
- the regulated entity has, within the previous twelve months, provided that consumer with a product or service similar to the purpose of the telephone contact
- the consumer has given his or her consent to being contacted in this way by the regulated entity.
- ONLY IF
- CONSUMERS other than an existing customer POTENTIAL CUSTOMERS
- ONLY IF
- the purpose of the telephone contact is limited to offering protection policies only; or
- ALL GENERAL insurance
- life assiurance, such motor and liability insurance
- with the purpose of provide PROTECTION
- PERMANENT health insurance
- annuaities, both conventional and unit link
- referral with express consent provided
- Listed in the BUSINESS listed section of the current telephone directoty, classified or trade professional circulatiing in the state
- the purpose of the telephone contact is limited to offering protection policies only; or
- MEETING POTENTIAL CLIENT
- IDENTYFY, YOURSELF, YOUR FIRM,
- state on bhalf of who and reason of the contact
- inform telephone call is being recorded if that is the case
- disclose the the source of the business lead or referral
- establish of they wish to continue with phone call /email)
- PROVIDE TERM OF BUSINESS DOC, on a stand alone basis before providing financial advice
- ONLY IF
- UNSOLICITED PHONE CALLS
- ONLY BETWEEN 9 AM A- 9 PM
- EXISTING CUSTOMERS
- A regulated entity may make telephone contact with a consumer who is an existing customer, only if:
- Restrictions on use of email, texting and phone calls
Information
- Description
- Chapter 3 Regulatory provisions which set the rules for the Financial service providers
- Created by
- MARTHA MADRIZ
- Views
- 40
- Tags
- Rating