
Mind map
6) Planning & Risk Assessment
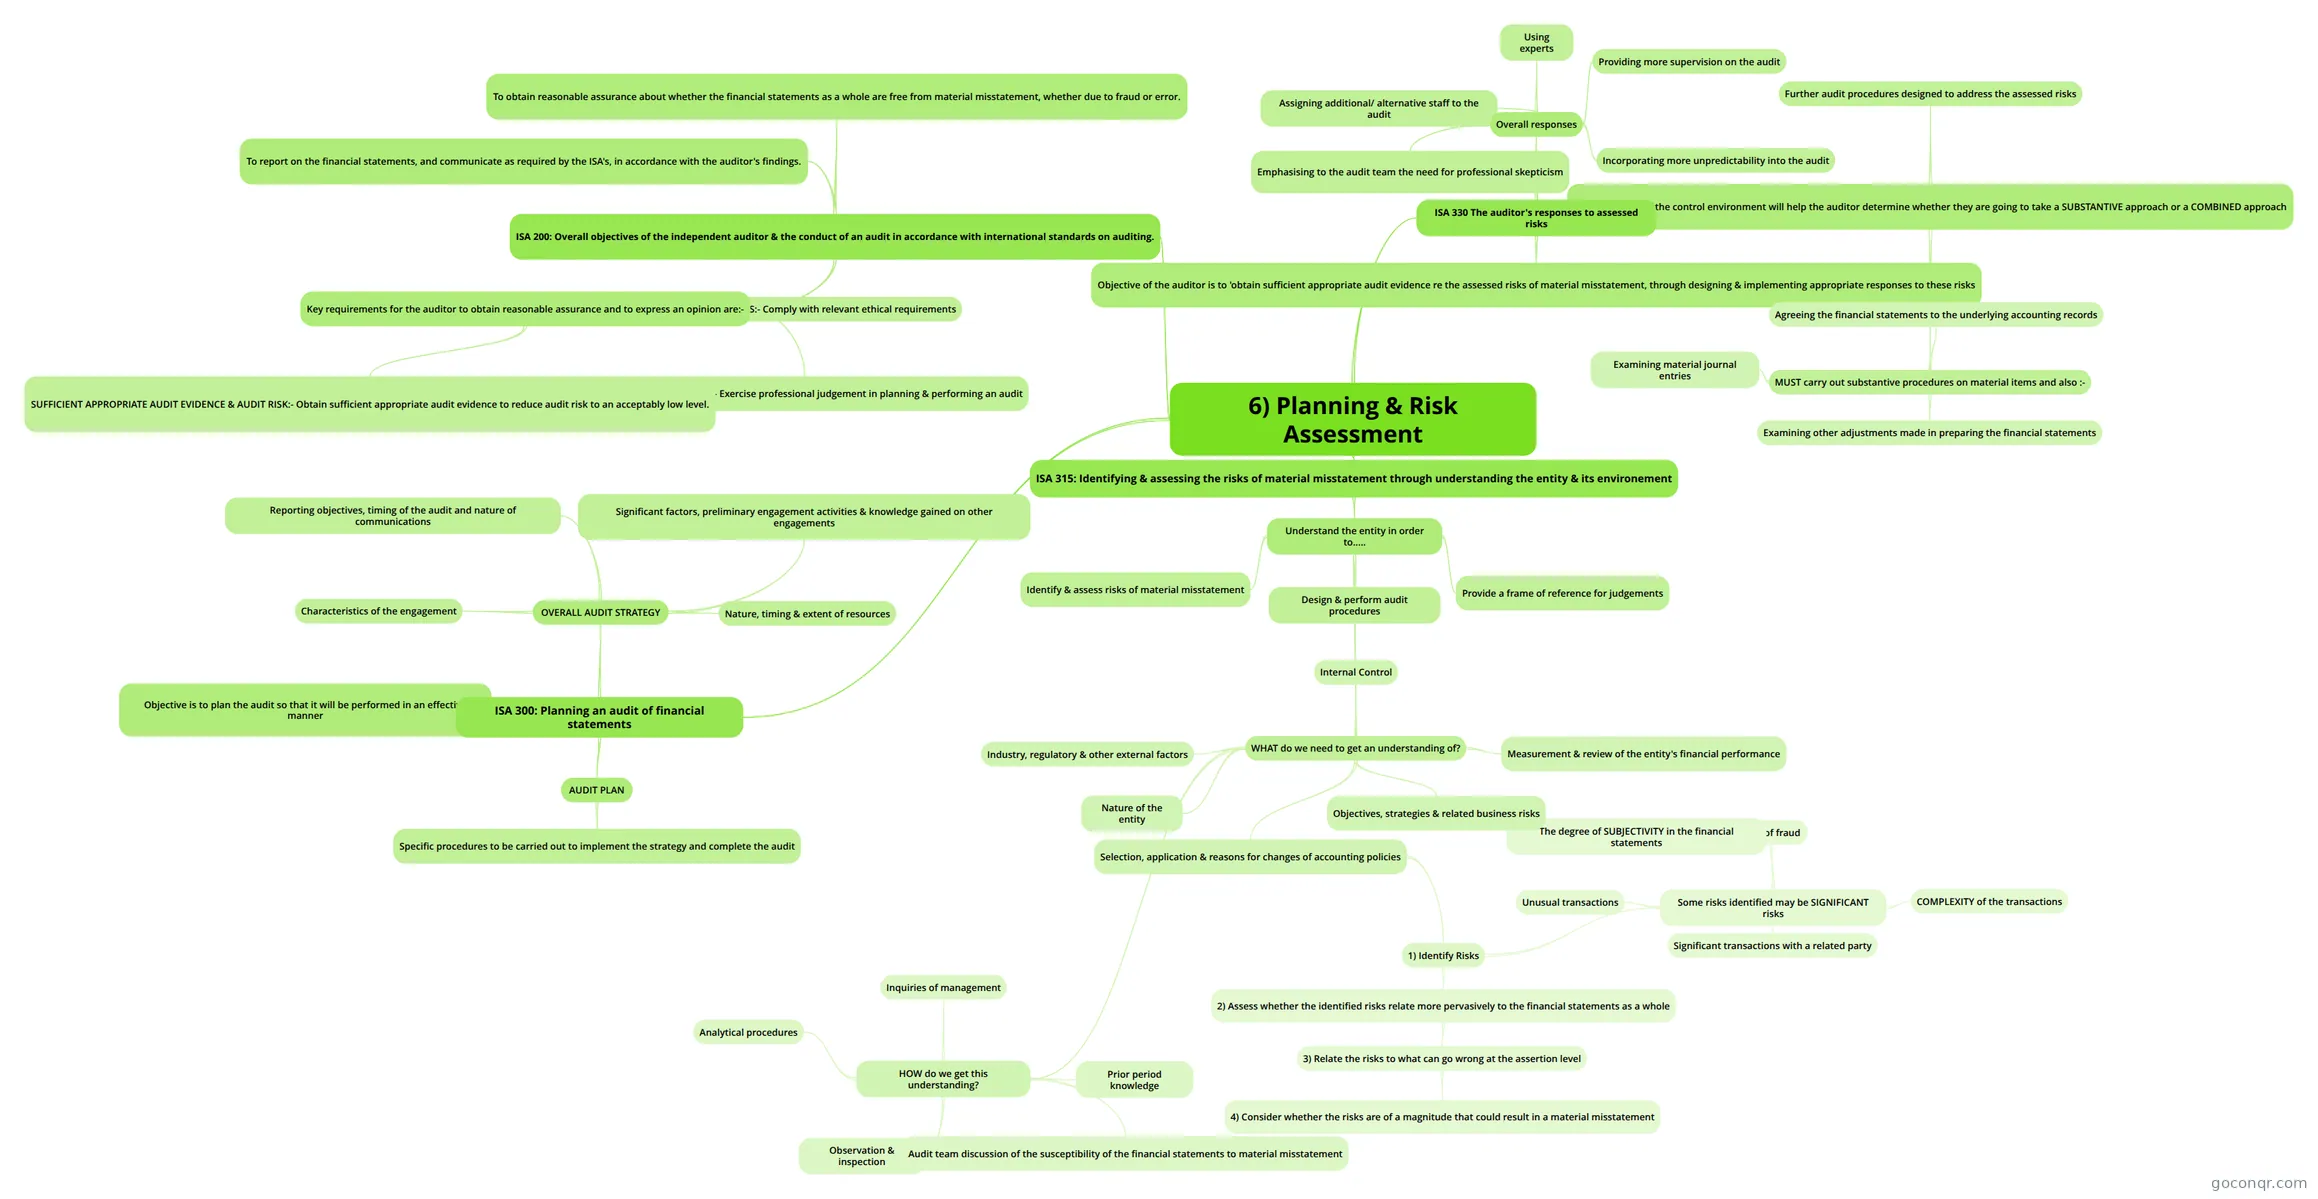
Mind map: planning & risk assessment
Map content
6) Planning & Risk Assessment
ISA 200: Overall objectives of the independent auditor & the conduct of an audit in accordance with international standards on auditing.
- To obtain reasonable assurance about whether the financial statements as a whole are free from material misstatement, whether due to fraud or error.
- To report on the financial statements, and communicate as required by the ISA's, in accordance with the auditor's findings.
- Key requirements for the auditor to obtain reasonable assurance and to express an opinion are:-
- ETHICS:- Comply with relevant ethical requirements
- PROFESSIONAL SKEPTICISM:- Exercise professional judgement in planning & performing an audit
- SUFFICIENT APPROPRIATE AUDIT EVIDENCE & AUDIT RISK:- Obtain sufficient appropriate audit evidence to reduce audit risk to an acceptably low level.
ISA 300: Planning an audit of financial statements
- Objective is to plan the audit so that it will be performed in an effective manner
- OVERALL AUDIT STRATEGY
- Characteristics of the engagement
- Reporting objectives, timing of the audit and nature of communications
- Significant factors, preliminary engagement activities & knowledge gained on other engagements
- Nature, timing & extent of resources
- AUDIT PLAN
- Specific procedures to be carried out to implement the strategy and complete the audit
ISA 315: Identifying & assessing the risks of material misstatement through understanding the entity & its environement
- Understand the entity in order to.....
- Identify & assess risks of material misstatement
- Design & perform audit procedures
- Provide a frame of reference for judgements
- WHAT do we need to get an understanding of?
- Industry, regulatory & other external factors
- Nature of the entity
- Selection, application & reasons for changes of accounting policies
- 1) Identify Risks
- 2) Assess whether the identified risks relate more pervasively to the financial statements as a whole
- 3) Relate the risks to what can go wrong at the assertion level
- 4) Consider whether the risks are of a magnitude that could result in a material misstatement
- 3) Relate the risks to what can go wrong at the assertion level
- Some risks identified may be SIGNIFICANT risks
- Risk of fraud
- The degree of SUBJECTIVITY in the financial statements
- Unusual transactions
- Significant transactions with a related party
- COMPLEXITY of the transactions
- 2) Assess whether the identified risks relate more pervasively to the financial statements as a whole
- 1) Identify Risks
- Objectives, strategies & related business risks
- Measurement & review of the entity's financial performance
- Internal Control
- HOW do we get this understanding?
- Inquiries of management
- Analytical procedures
- Observation & inspection
- Audit team discussion of the susceptibility of the financial statements to material misstatement
- Prior period knowledge
- Understand the entity in order to.....
ISA 330 The auditor's responses to assessed risks
- Objective of the auditor is to 'obtain sufficient appropriate audit evidence re the assessed risks of material misstatement, through designing & implementing appropriate responses to these risks
- Overall responses
- Emphasising to the audit team the need for professional skepticism
- Assigning additional/ alternative staff to the audit
- Using experts
- Providing more supervision on the audit
- Incorporating more unpredictability into the audit
- The evaluation of the control environment will help the auditor determine whether they are going to take a SUBSTANTIVE approach or a COMBINED approach
- Further audit procedures designed to address the assessed risks
- MUST carry out substantive procedures on material items and also :-
- Agreeing the financial statements to the underlying accounting records
- Examining material journal entries
- Examining other adjustments made in preparing the financial statements
Information
- Description
- Mind Map on 6) Planning & Risk Assessment, created by spoltorakov on 20/11/2014.
- Created by
- spoltorakov
- Views
- 10
- History
-
- Created by littlepaz_2001 · Nov 20, 2014
- Copied by spoltorakov · Nov 20, 2014
- Rating
More on Audit Planning and Materiality