
Mind map
Standards: 1000 series
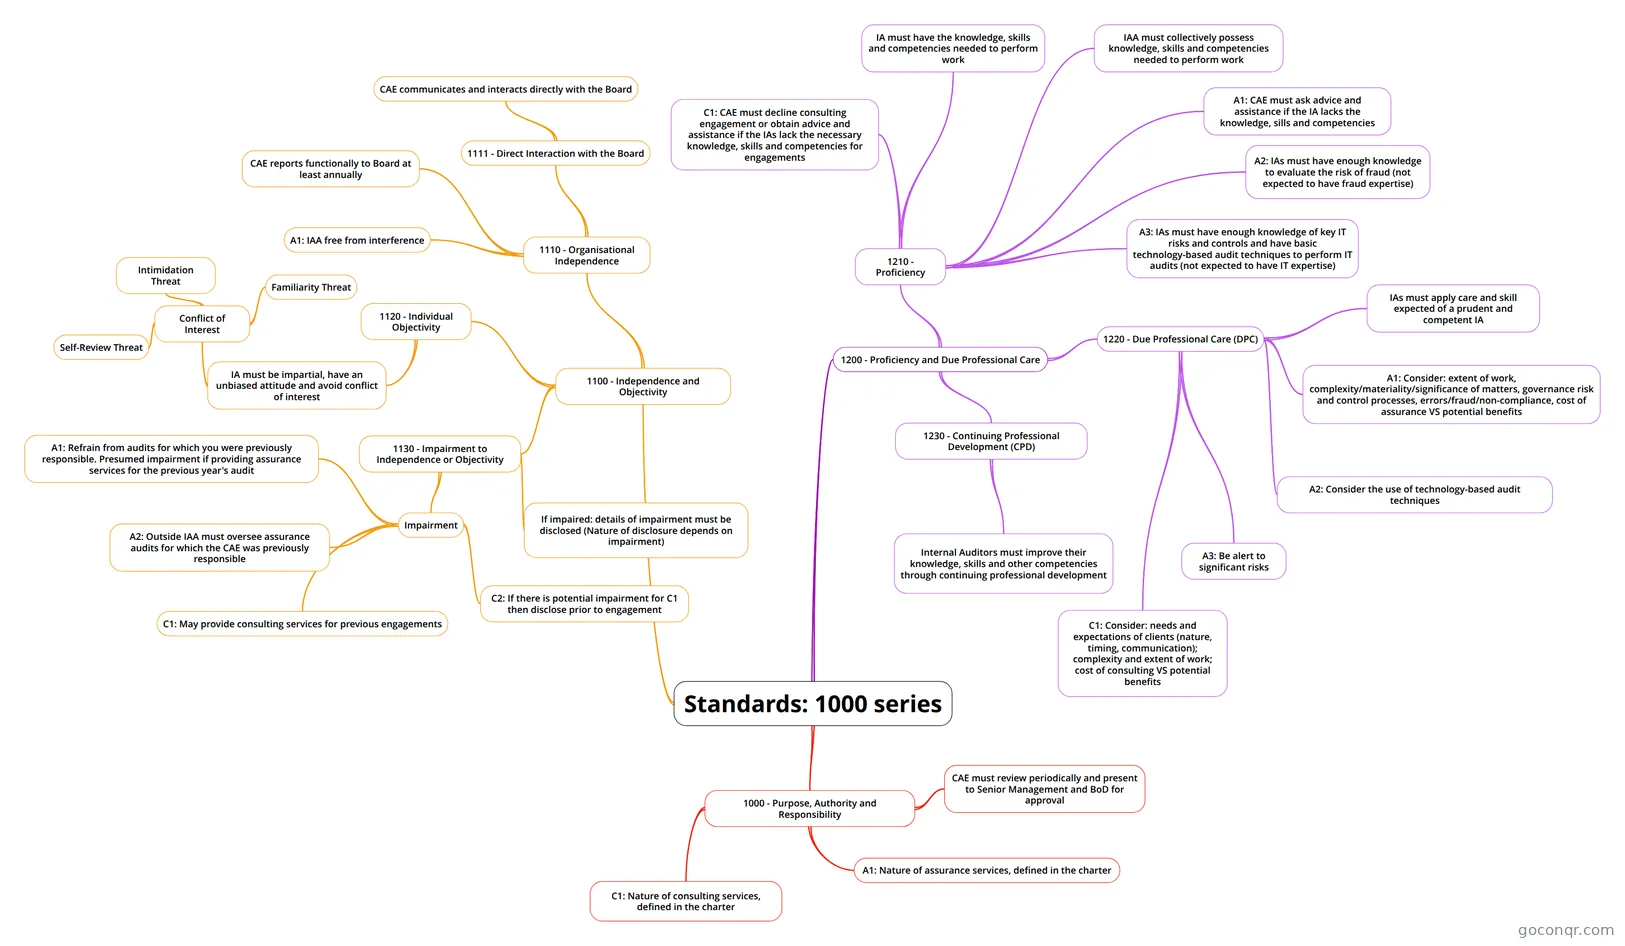
Mind map: Standards: 1000 series
Map content
Standards: 1000 series
1100 - Independence and Objectivity
- 1110 - Organisational Independence
- CAE reports functionally to Board at least annually
- 1111 - Direct Interaction with the Board
- CAE communicates and interacts directly with the Board
- A1: IAA free from interference
- 1120 - Individual Objectivity
- IA must be impartial, have an unbiased attitude and avoid conflict of interest
- Conflict of Interest
- Familiarity Threat
- Self-Review Threat
- Intimidation Threat
- Conflict of Interest
- IA must be impartial, have an unbiased attitude and avoid conflict of interest
- 1130 - Impairment to Independence or Objectivity
- If impaired: details of impairment must be disclosed (Nature of disclosure depends on impairment)
- Impairment
- A1: Refrain from audits for which you were previously responsible. Presumed impairment if providing assurance services for the previous year's audit
- A2: Outside IAA must oversee assurance audits for which the CAE was previously responsible
- C1: May provide consulting services for previous engagements
- C2: If there is potential impairment for C1 then disclose prior to engagement
- 1110 - Organisational Independence
1200 - Proficiency and Due Professional Care
- 1210 - Proficiency
- IA must have the knowledge, skills and competencies needed to perform work
- IAA must collectively possess knowledge, skills and competencies needed to perform work
- A1: CAE must ask advice and assistance if the IA lacks the knowledge, sills and competencies
- A2: IAs must have enough knowledge to evaluate the risk of fraud (not expected to have fraud expertise)
- A3: IAs must have enough knowledge of key IT risks and controls and have basic technology-based audit techniques to perform IT audits (not expected to have IT expertise)
- C1: CAE must decline consulting engagement or obtain advice and assistance if the IAs lack the necessary knowledge, skills and competencies for engagements
- 1220 - Due Professional Care (DPC)
- IAs must apply care and skill expected of a prudent and competent IA
- A1: Consider: extent of work, complexity/materiality/significance of matters, governance risk and control processes, errors/fraud/non-compliance, cost of assurance VS potential benefits
- A2: Consider the use of technology-based audit techniques
- A3: Be alert to significant risks
- C1: Consider: needs and expectations of clients (nature, timing, communication); complexity and extent of work; cost of consulting VS potential benefits
- 1230 - Continuing Professional Development (CPD)
- Internal Auditors must improve their knowledge, skills and other competencies through continuing professional development
- 1210 - Proficiency
1000 - Purpose, Authority and Responsibility
- CAE must review periodically and present to Senior Management and BoD for approval
- A1: Nature of assurance services, defined in the charter
- C1: Nature of consulting services, defined in the charter
Information
- Description
- University Internal Auditing Mind Map on Standards: 1000 series, created by Cait O'D on 09/03/2015.
- Created by
- Cait O'D
- Views
- 3
- Rating
More on Internal Audit Standards and Ethics