
Mind map
Production and its costs
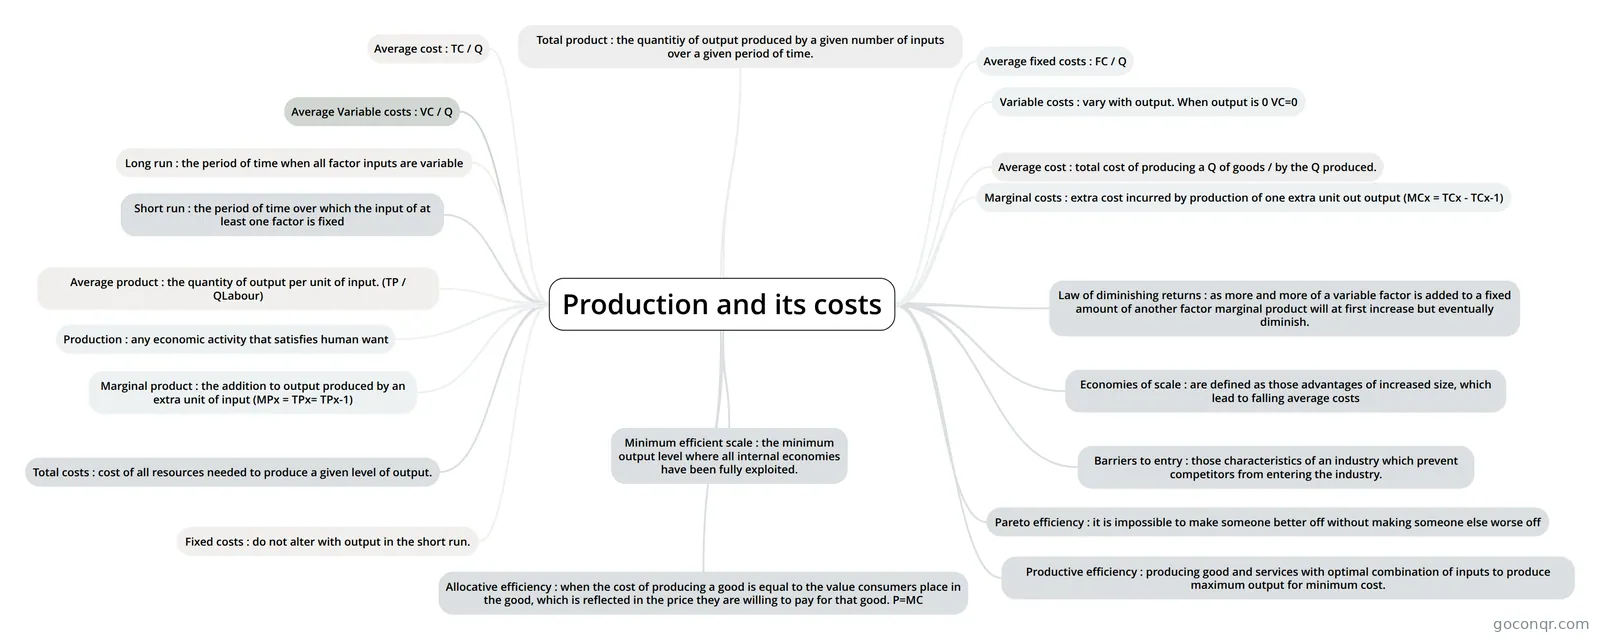
Mind map: Production and its costs
Map content
Production and its costs
Production : any economic activity that satisfies human want
Short run : the period of time over which the input of at least one factor is fixed
Long run : the period of time when all factor inputs are variable
Total product : the quantitiy of output produced by a given number of inputs over a given period of time.
Average product : the quantity of output per unit of input. (TP / QLabour)
Marginal product : the addition to output produced by an extra unit of input (MPx = TPx= TPx-1)
Total costs : cost of all resources needed to produce a given level of output.
Fixed costs : do not alter with output in the short run.
Variable costs : vary with output. When output is 0 VC=0
Average cost : TC / Q
Average fixed costs : FC / Q
Average Variable costs : VC / Q
Marginal costs : extra cost incurred by production of one extra unit out output (MCx = TCx - TCx-1)
Average cost : total cost of producing a Q of goods / by the Q produced.
Law of diminishing returns : as more and more of a variable factor is added to a fixed amount of another factor marginal product will at first increase but eventually diminish.
Economies of scale : are defined as those advantages of increased size, which lead to falling average costs
Minimum efficient scale : the minimum output level where all internal economies have been fully exploited.
Barriers to entry : those characteristics of an industry which prevent competitors from entering the industry.
Pareto efficiency : it is impossible to make someone better off without making someone else worse off
Allocative efficiency : when the cost of producing a good is equal to the value consumers place in the good, which is reflected in the price they are willing to pay for that good. P=MC
Productive efficiency : producing good and services with optimal combination of inputs to produce maximum output for minimum cost.
Information
- Description
- Economics - short run and long run costs and revenue
- Created by
- courtneybrown976
- Views
- 6
- Rating