
Mind map
AAT - level 3
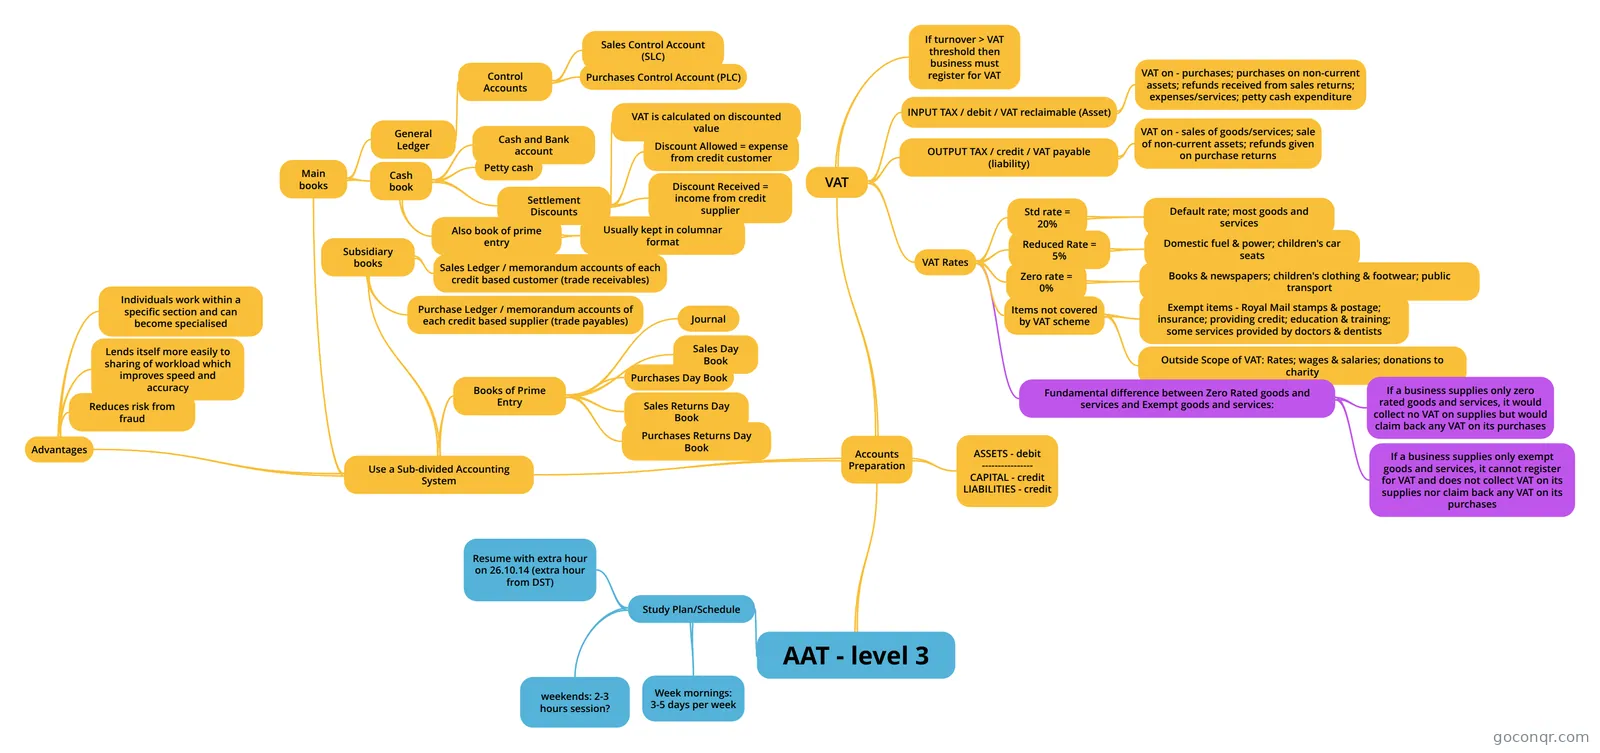
Mind map: AAT level 3 accounting study plan
Map content
AAT - level 3
Study Plan/Schedule
- comment
- Week mornings: 3-5 days per week
- Resume with extra hour on 26.10.14 (extra hour from DST)
- weekends: 2-3 hours session?
Accounts Preparation
- ASSETS - debit ---------------- CAPITAL - credit LIABILITIES - credit
- VAT
- VAT Rates
- Std rate = 20%
- Default rate; most goods and services
- Reduced Rate = 5%
- Domestic fuel & power; children's car seats
- Zero rate = 0%
- Books & newspapers; children's clothing & footwear; public transport
- Items not covered by VAT scheme
- Exempt items - Royal Mail stamps & postage; insurance; providing credit; education & training; some services provided by doctors & dentists
- Outside Scope of VAT: Rates; wages & salaries; donations to charity
- Fundamental difference between Zero Rated goods and services and Exempt goods and services:
- If a business supplies only zero rated goods and services, it would collect no VAT on supplies but would claim back any VAT on its purchases
- If a business supplies only exempt goods and services, it cannot register for VAT and does not collect VAT on its supplies nor claim back any VAT on its purchases
- Std rate = 20%
- If turnover > VAT threshold then business must register for VAT
- INPUT TAX / debit / VAT reclaimable (Asset)
- VAT on - purchases; purchases on non-current assets; refunds received from sales returns; expenses/services; petty cash expenditure
- OUTPUT TAX / credit / VAT payable (liability)
- VAT on - sales of goods/services; sale of non-current assets; refunds given on purchase returns
- VAT Rates
- Use a Sub-divided Accounting System
- Main books
- General Ledger
- Control Accounts
- Sales Control Account (SLC)
- Purchases Control Account (PLC)
- Control Accounts
- Cash book
- Also book of prime entry
- Usually kept in columnar format
- Petty cash
- Cash and Bank account
- Settlement Discounts
- Discount Received = income from credit supplier
- Discount Allowed = expense from credit customer
- VAT is calculated on discounted value
- Also book of prime entry
- General Ledger
- Subsidiary books
- Sales Ledger / memorandum accounts of each credit based customer (trade receivables)
- Purchase Ledger / memorandum accounts of each credit based supplier (trade payables)
- Books of Prime Entry
- Journal
- Sales Day Book
- Purchases Day Book
- Sales Returns Day Book
- Purchases Returns Day Book
- Advantages
- Individuals work within a specific section and can become specialised
- Lends itself more easily to sharing of workload which improves speed and accuracy
- Reduces risk from fraud
- Main books
Information
- Description
- Mind Map on AAT - level 3, created by patrick.grindley on 25/10/2014.
- Created by
- patrick.grindley
- Views
- 166
- Rating