
Notes
Group Accounts
Content of the notes (1)
Page 1
Acquiring Sole trader means
we own its assets liabilities profits and losses. Same is with
partnership. This all is recorded
in parents statements.
Acquiring company means we
acquire shares instead of individual assets. Investments is recorded at
cost in parent's statements.
IFRS 3 is followed.
Total assets should be equal
to equities and liabilities to balance the statement.
0- 20% share capital: No
effective influence. Accounting
treatment: can only account for dividends rcvd. Do not consolidate.
20%-50% share capital:
significant effective influence. Accounting treatment: Equity and it is
associated company. It's just investment. No consolidation is required.
More than 50%: control Accounting: acquisition and here consolidated
financial statement or group financial statements.
Only if company is a
subsidiary then consolidation is done it is not for associated.
In consolidation investment
in subsidiary is not reported or mentioned or shown.
Share capital is only shown
of parent in consolidated statement not of subsidiary.
Working no 1 is to show how
much parent owns subsidiary's share capital.
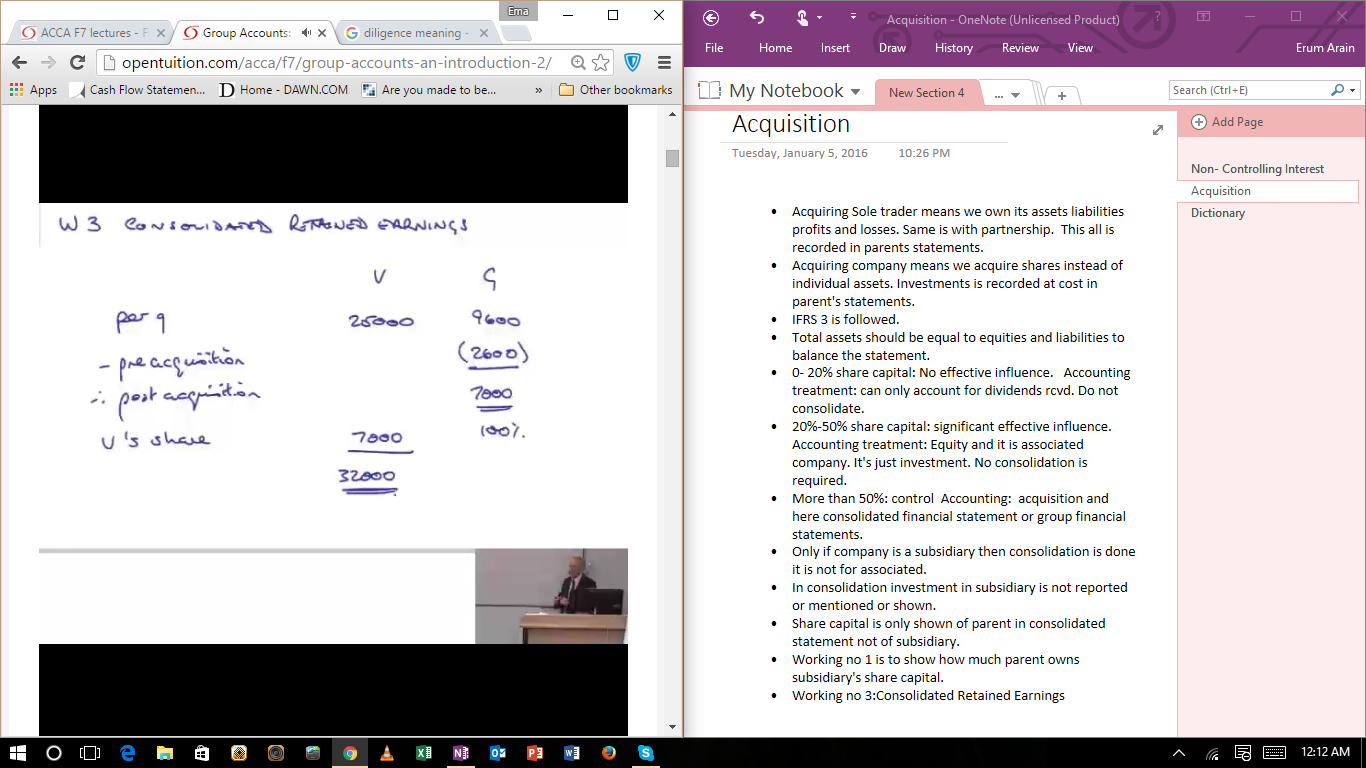
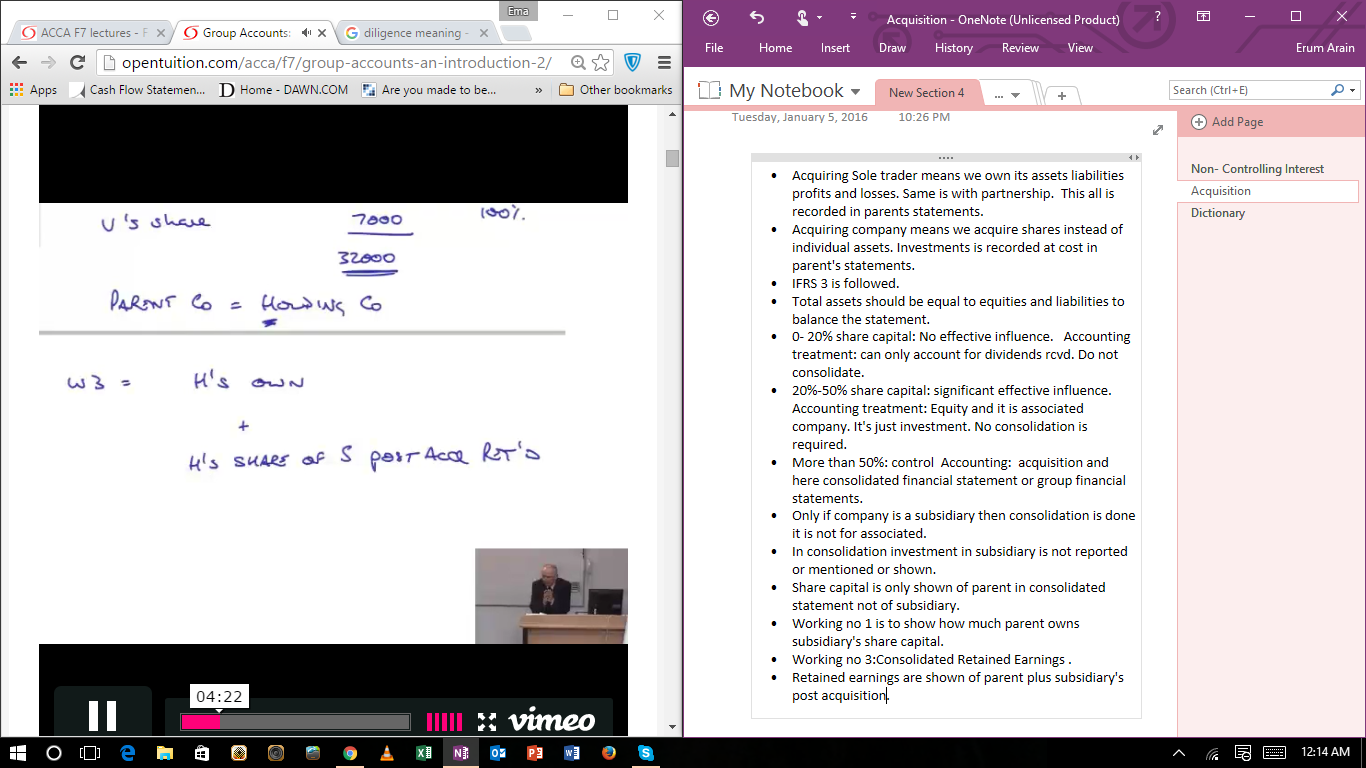
Working no 3:Consolidated
Retained Earnings .
Retained earnings are shown
of parent plus subsidiary's post acquisition since we acquired subsidiary.
W3 is done to achieve
Consolidated retained earnings which have been achieved under the control
of parent company.
Sometimes it is not necessary
that you have more than 50% of share capital and you do have the power to
influence.
Sometimes one may own less
than 50% but can have an influencing right. E.g. If one lends u money and
asks that on behalf of it you have to appoint my 2 directors, even I don't
have the company's capital more than 50% but I can appoint in that case if
the company agrees to it.
Own more than half but don't
have control
Lender with power to appoint a majority
of the board
Company is in liquidation so
power is transferred to liquidator even if one owns 100% of the company.
Q: Where may a
parent wish to exclude subsidiary form consolidation?
A: Because of poor
subsidiary performance. But IFRS3 says if one has subsidiary must show the
subsidiary.
Or because the
expense of consolidation is greater than benefit. If Immaterial subsidiaries
are there than 1 can exclude or do not show. To this auditors and directors
must agree.
Or because of
Expense or delay I.e. year ends do not match
Then the months
coming in that accounting period of company are consolidated.
Any subsidiary
activity should be included until u get up to 75% u have to do segmented
reporting. It was done before but not now.
Information
- Description
- Notes to Introduction of group accounts ch#6 according to OT
- Created by
- Erum Shabbir Arain
- Views
- 18
- Rating