
Flashcards
Costs Functions & Theory of the Firm
Cards in this deck (22)
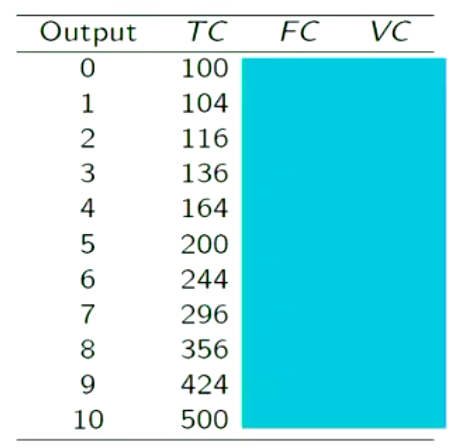
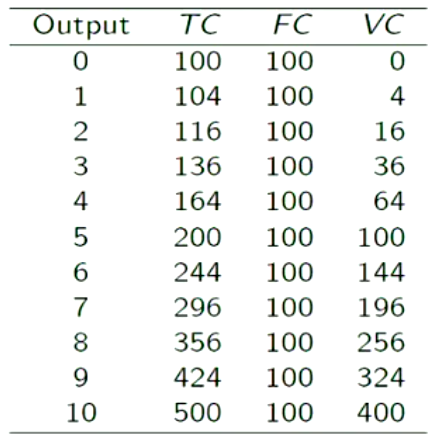
- 1What is a 'Fixed Cost'?A cost that does not vary with the quantity of output produced.
- 2What is a 'Variable Cost'?Cost that varies with the quantity of output produced.
- 3Total Cost (TC) =Fixed Cost (TFC) + Variable Cost (TVC)
- 4How much is FC?100
- 5What does the 'Marginal Cost' (MC) do?Measures the increase in total cost that arises from an extra unit of production.
How much does it cost to produce one additional unit of output? - 6What is the formula for marginal cost?
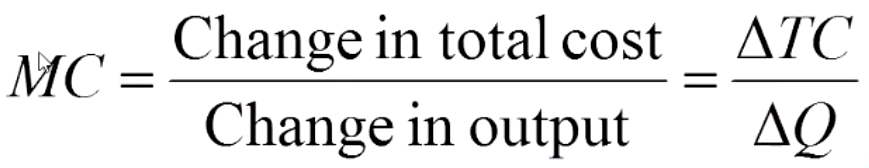
- 7What will happen to the 'Average Fixed Cost' (AFC) in the long run?It will always decline.
For e.g. if FC = 100, then 100/1 = 100, 100/2 = 50 and so on... - 8What will happen the the 'Average Variable Cost' (AVC) in the long run?It will always decline.
For e.g. 4/1 = 4, 16/2 = 8, 36/3 = 12 and so on... - 9How is the 'Average Cost' (AC) calculated?TC/Number of Output
For e.g. 100/1, 104/2 and so on... - 10What makes up 'Average Total Cost' (ATC)?Average Fixed Cost (AFC) + Average Variable Cost (AVC)
- 11Where MUST the Marginal Cost Curve intersect the Average Total Cost Curve?At it's lowest point.
- 12When does the 'Law of Diminishing Marginal Returns' start to happen on the MC curve?From the lowest point onwards.
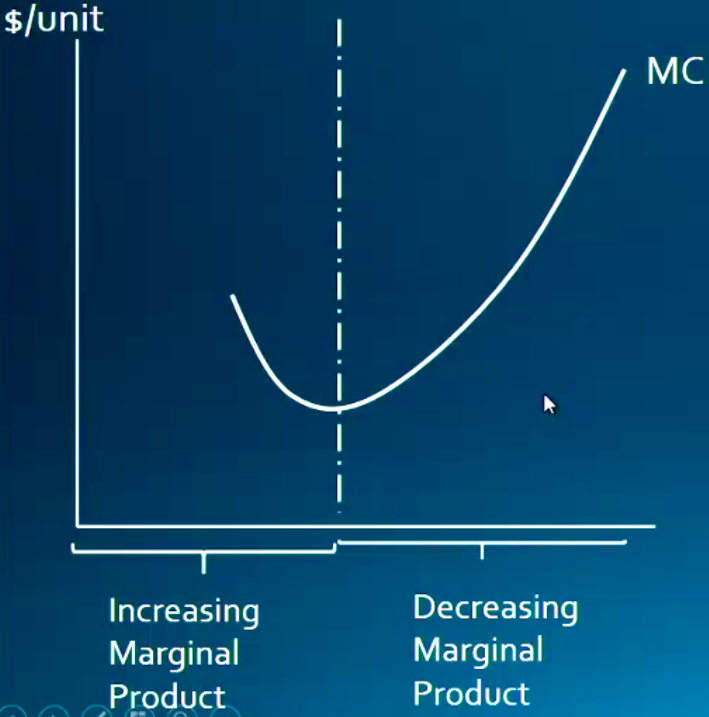
- 13The marginal cost curve eventually rises with the...quantity of output.
- 14The Average Total Cost (ATC) Curve is...U-shaped.
- 15Marginal Cost (MC) crosses both ATC and AVC at their...minimum's.
- 16What is happening to the average cost in each scenario?@ 3 Q = Economies of Scale
@ 2 Q = Constant Returns to Scale
@ 1(1/2) Q = Diseconomies of Scale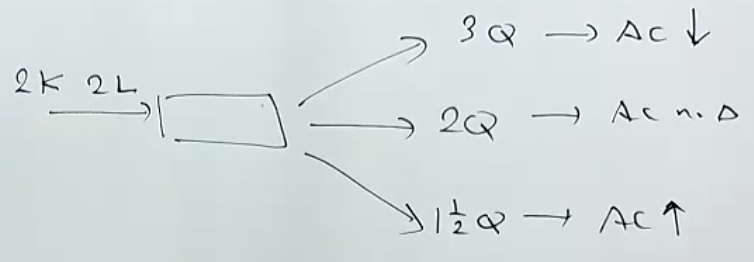
- 17What happens in 'Economies of Scale'?The long-run average total cost (ATC) falls as the quantity of output increases.
- 18What happens in 'Constant Returns to Scale'?Long-run average total cost (ATC) stays the same as the quantity of output changes.
- 19What happens in 'Diseconomies of Scale'?Long-run average total cost (ATC) rises as the quantity of output increases.
- 20What are the features of a competitive market?1. There are many buyers and sellers
2. The goods are largely the same
3. There is perfect competition
4. Both sellers and buyers are 'price takers' (They have no influence over price)
4. Low barriers to entry - 21For competitive firms, average revenue and marginal revenue should equal...?Price.
AR = MR = P - 22In both a monopoly and competitive markets, to maximise profit...MC must be = to or less than MR