
Mind map
HOEPA/part of TILA
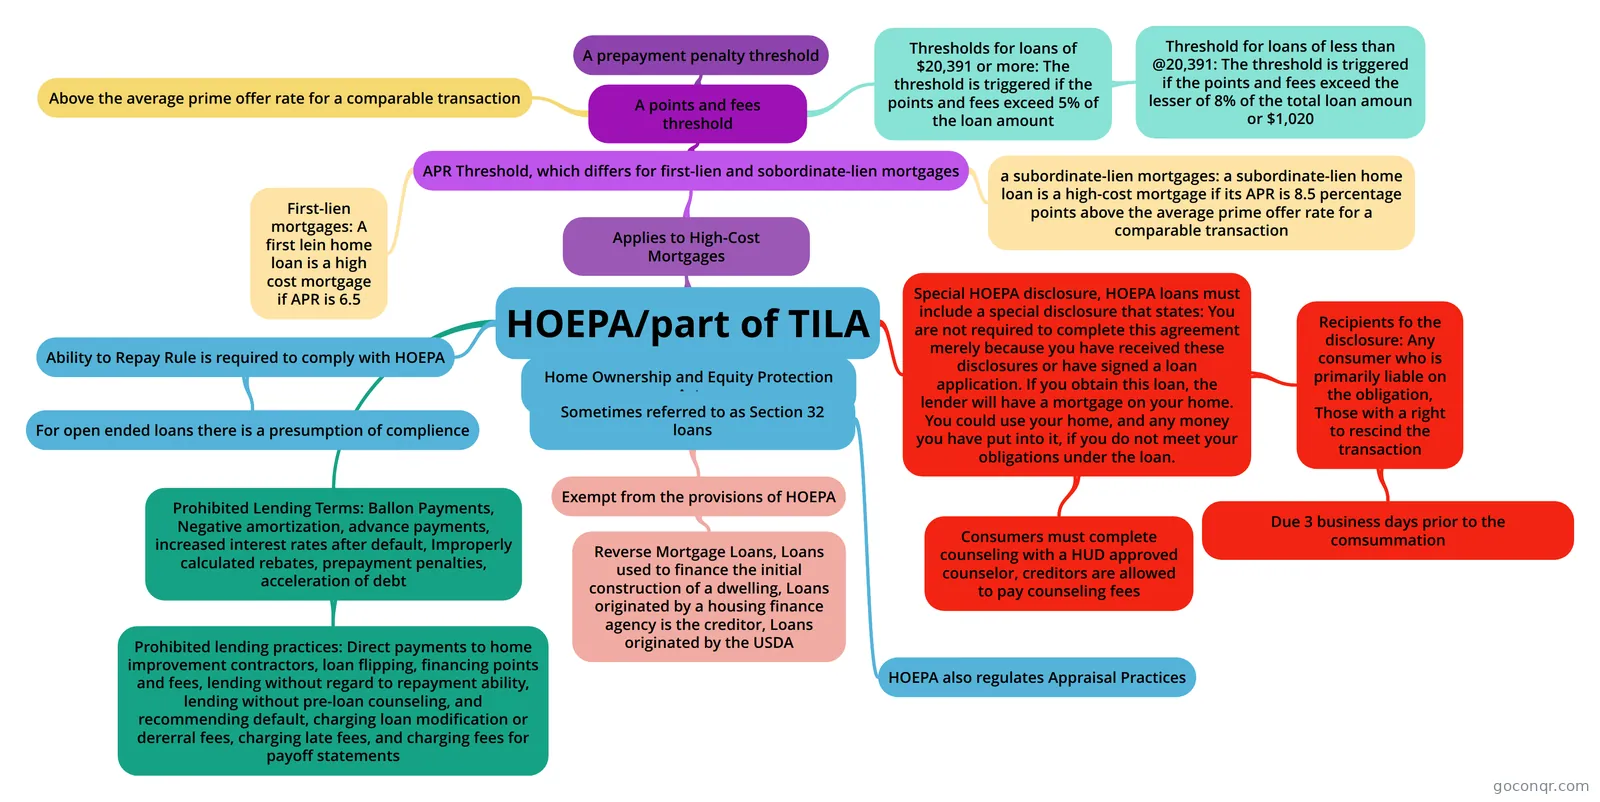
Mind map: HOEPA part of TILA
Map content
HOEPA/part of TILA
Home Ownership and Equity Protection Act
- Sometimes referred to as Section 32 loans
- Exempt from the provisions of HOEPA
- Reverse Mortgage Loans, Loans used to finance the initial construction of a dwelling, Loans originated by a housing finance agency is the creditor, Loans originated by the USDA
- HOEPA also regulates Appraisal Practices
- Exempt from the provisions of HOEPA
- Sometimes referred to as Section 32 loans
Applies to High-Cost Mortgages
- APR Threshold, which differs for first-lien and sobordinate-lien mortgages
- A points and fees threshold
- A prepayment penalty threshold
- Above the average prime offer rate for a comparable transaction
- Thresholds for loans of $20,391 or more: The threshold is triggered if the points and fees exceed 5% of the loan amount
- Threshold for loans of less than @20,391: The threshold is triggered if the points and fees exceed the lesser of 8% of the total loan amoun or $1,020
- First-lien mortgages: A first lein home loan is a high cost mortgage if APR is 6.5
- a subordinate-lien mortgages: a subordinate-lien home loan is a high-cost mortgage if its APR is 8.5 percentage points above the average prime offer rate for a comparable transaction
- A points and fees threshold
- APR Threshold, which differs for first-lien and sobordinate-lien mortgages
Special HOEPA disclosure, HOEPA loans must include a special disclosure that states: You are not required to complete this agreement merely because you have received these disclosures or have signed a loan application. If you obtain this loan, the lender will have a mortgage on your home. You could use your home, and any money you have put into it, if you do not meet your obligations under the loan.
- Recipients fo the disclosure: Any consumer who is primarily liable on the obligation, Those with a right to rescind the transaction
- Due 3 business days prior to the comsummation
- Consumers must complete counseling with a HUD approved counselor, creditors are allowed to pay counseling fees
- Recipients fo the disclosure: Any consumer who is primarily liable on the obligation, Those with a right to rescind the transaction
Ability to Repay Rule is required to comply with HOEPA
- For open ended loans there is a presumption of complience
Prohibited Lending Terms: Ballon Payments, Negative amortization, advance payments, increased interest rates after default, Improperly calculated rebates, prepayment penalties, acceleration of debt
- Prohibited lending practices: Direct payments to home improvement contractors, loan flipping, financing points and fees, lending without regard to repayment ability, lending without pre-loan counseling, and recommending default, charging loan modification or dererral fees, charging late fees, and charging fees for payoff statements