
Notes
Monopoly - created from Mind Map
Content of the notes (1)
Page 1
Barriers to Entry
Legal Restrictions
Economies of Scale
Control of Essential Resources: Which
Patents and Invention Incentives
Liscenses and Other Entry Restrictions
One Firm can satisfy market demand at a lower average cost per unit than could two or more firms each operating at smaller rates of outputs.
Singe Seller, No Substitutes, Firm = Industry, Price Maker, and Blocked Entry
Price = AR = D
Profit Maximization
Total Revenue Minus Total Cost
Marginal Revenue Equals Margional Cost
Long Run: P.M.
Monopolist supplies the quanitiy at which total revenue exceeds total cost by the greatest amount.
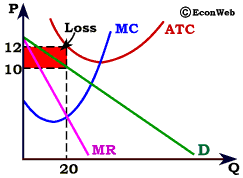
The profit-Maximizing outputs occurs where marginal revenue equals marginal cost. ^The Golden Rule of Profit Maximization
All the costs need to be covereded or the business will not suceed. If a monopoly is insulated from competition by high barriersthat block new entry, economic profit can persist into the long run.
Efficiency
Productive Efficency: P=Min ATC
Allocative Efficency: P=MC
Monopoly
Information
- Description
- Note on Monopoly - created from Mind Map, created by cjkowatsch on 09/04/2014.
- Created by
- cjkowatsch · Apr 2014
- Updated
- Feb 19, 2016
- Views
- 63
- History
-
- Created by cjkowatsch · Apr 9, 2014
- Copied to Note by cjkowatsch · Apr 9, 2014
- Rating