
Mind map
Revenue from contracts with customers
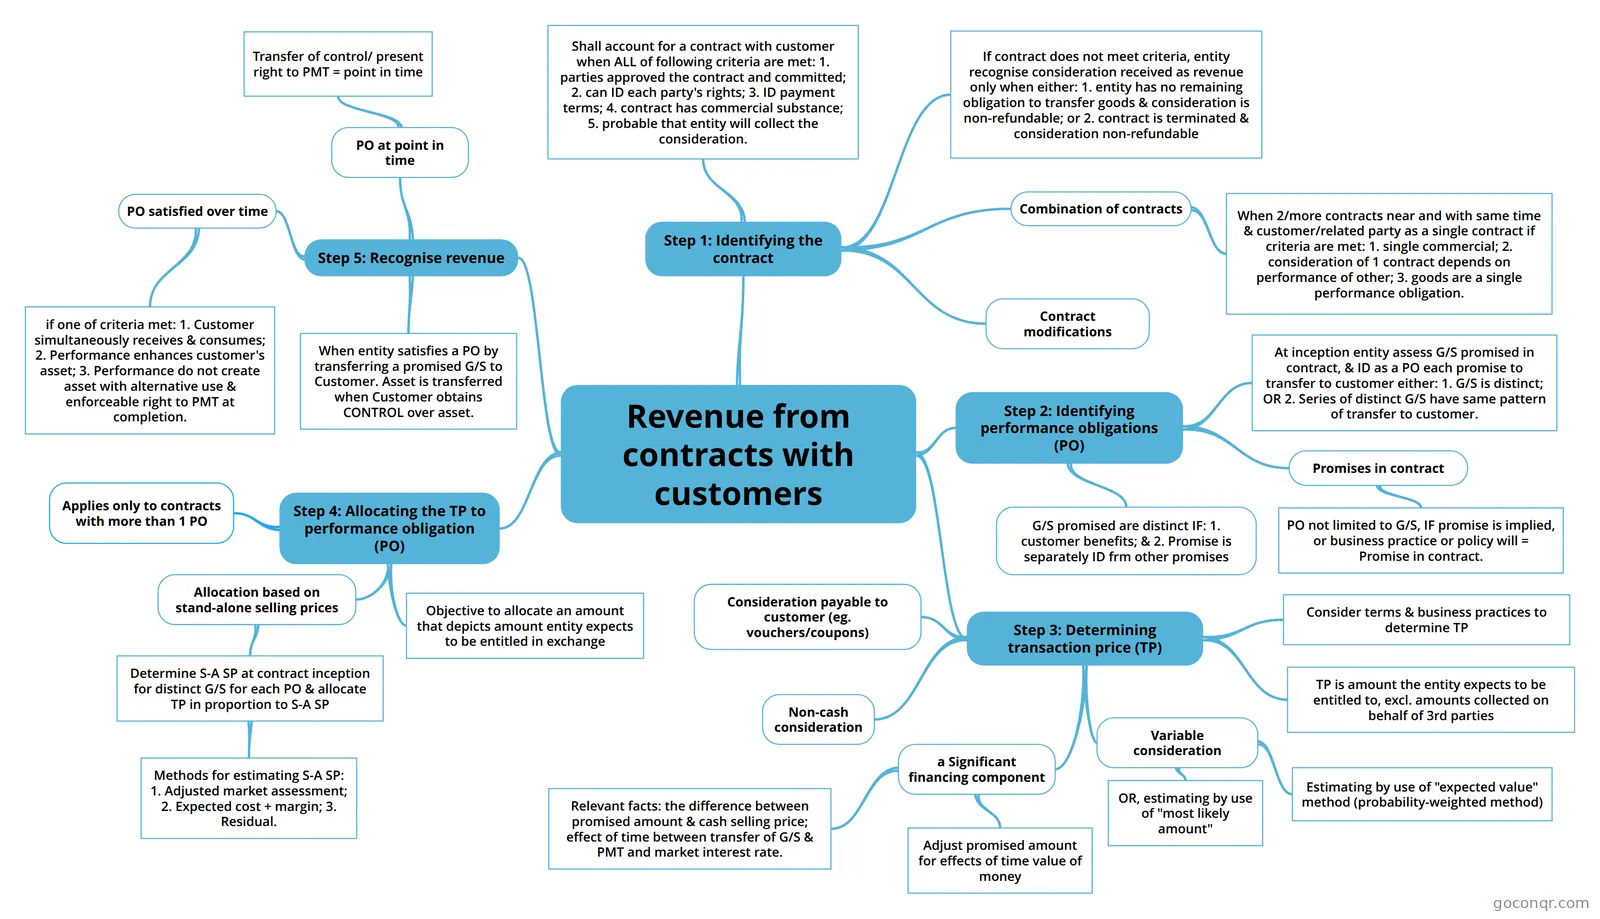
Mind map: Revenue from contracts with customers
Map content
Revenue from contracts with customers
Step 1: Identifying the contract
- Shall account for a contract with customer when ALL of following criteria are met: 1. parties approved the contract and committed; 2. can ID each party's rights; 3. ID payment terms; 4. contract has commercial substance; 5. probable that entity will collect the consideration.
- If contract does not meet criteria, entity recognise consideration received as revenue only when either: 1. entity has no remaining obligation to transfer goods & consideration is non-refundable; or 2. contract is terminated & consideration non-refundable
- Combination of contracts
- When 2/more contracts near and with same time & customer/related party as a single contract if criteria are met: 1. single commercial; 2. consideration of 1 contract depends on performance of other; 3. goods are a single performance obligation.
- Contract modifications
Step 2: Identifying performance obligations (PO)
- At inception entity assess G/S promised in contract, & ID as a PO each promise to transfer to customer either: 1. G/S is distinct; OR 2. Series of distinct G/S have same pattern of transfer to customer.
- Promises in contract
- PO not limited to G/S, IF promise is implied, or business practice or policy will = Promise in contract.
- G/S promised are distinct IF: 1. customer benefits; & 2. Promise is separately ID frm other promises
Step 3: Determining transaction price (TP)
- Consider terms & business practices to determine TP
- TP is amount the entity expects to be entitled to, excl. amounts collected on behalf of 3rd parties
- Variable consideration
- Estimating by use of "expected value" method (probability-weighted method)
- OR, estimating by use of "most likely amount"
- a Significant financing component
- Adjust promised amount for effects of time value of money
- Relevant facts: the difference between promised amount & cash selling price; effect of time between transfer of G/S & PMT and market interest rate.
- Non-cash consideration
- Consideration payable to customer (eg. vouchers/coupons)
Step 4: Allocating the TP to performance obligation (PO)
- Objective to allocate an amount that depicts amount entity expects to be entitled in exchange
- Allocation based on stand-alone selling prices
- Determine S-A SP at contract inception for distinct G/S for each PO & allocate TP in proportion to S-A SP
- Methods for estimating S-A SP: 1. Adjusted market assessment; 2. Expected cost + margin; 3. Residual.
- Determine S-A SP at contract inception for distinct G/S for each PO & allocate TP in proportion to S-A SP
- Applies only to contracts with more than 1 PO
Step 5: Recognise revenue
- When entity satisfies a PO by transferring a promised G/S to Customer. Asset is transferred when Customer obtains CONTROL over asset.
- PO satisfied over time
- if one of criteria met: 1. Customer simultaneously receives & consumes; 2. Performance enhances customer's asset; 3. Performance do not create asset with alternative use & enforceable right to PMT at completion.
- PO at point in time
- Transfer of control/ present right to PMT = point in time