
Flashcards
4 ~ Supply
Cards in this deck (41)
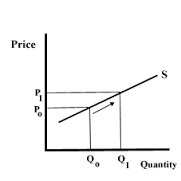
- 1What is supply?the quantity of a product that a producer is willing and able to supply onto the market at a given price
- 2What happens to S when ↑P?↑P = ↑S
businesses expand production - 3What is a movement along the S curve caused by?P only
- 4What are the laws of S? (3)profit motive
production costs
new entrants in the market - 5Explain profit motive↑D = ↑P = ↑S because it is more profitable to increase output
- 6Explain production costs↑S = ↑production costs = ↑P (to cover the costs)
- 7Explain new entrants into the market↑P = incentive for new entrants and therefore competition
- 8What main factors cause a shift in S? (4)change in production costs
change in technology
gov T, subsidies and regulations
competition - 9How does a change in production cost cause a shift in S?lower production costs = businesses can ↑S
cost savings can be passed through the S chain to wholesalers and retailers and may ↓P for consumers
↓ER = ↑P of M = ↓S - 10How do changes in technology cause a shift in S?if production technology change is rapid = ↑S = ↓P
- 11How does gov T, subsidies and regulations cause a shift in S?indirect T: ↑production costs = ↓S
subsidies: ↓costs of S = ↑S
regulations: ↑production costs = ↓S - 12How do changes in climate and agricultural conditions cause a shift in S?e.g. poor harvest = ↓S
- 13How does competition in a market cause a shift in S?when new firms enter a market = ↑S = downward pressure on P
- 14What are goods + services that are competitive in S?alternative products that a firm could make with it's factor reasources
- 15What does PES measure?the relationship between a change in Q and a change in market P
- 16What happens if S is elastic?producers can ↑output without a rise in costs or a time delay
- 17What happens if S is inelastic?firms find it hard to change production in a given time period
- 18What is the formula for calculating PES?%∆Q ÷ %∆P
- 19PES > 1supply is price elastic
- 201 < PES > 0S is inelastic
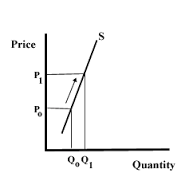
- 21PES = 0S is perfectly inelastic
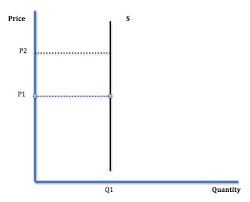
- 22PES = ∞S is perfectly elastic
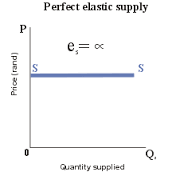
- 23What are factors affecting PES? (4)spare production capacity
stocks of unfinished products
ease + cost factor of mobility/substitution
time period + production speed - 24How does spare production capacity affect PES?if there is spare capacity then a business can ↑output without ↑P (so PES > 1)
- 25How do stocks of unfinished products and components affect PES?if stocks of raw materials and unfinished products are at a high level, then a firm is able to respond to a change in D (so PED > 1)
- 26How do east and cost factors of substitution and mobility affect PES?if both K and labour are occupationally mobile, then PES for a product is higher
- 27How do time period and production speed affect PES?S is more price elastic the longer time period a firm is allowed to adjust it's production levels
- 28What happens if ↑D and S = 0?↑P, Q stays the same
- 29What happens if ↑S and D = 0?↓P, Q stays the same
- 30What happens if ↑D and S = ∞?P stays the same, ↑Q
- 31What happens if ↑S and D = ∞?P stays the same, ↑Q
- 32What does production refer to?the output of goods and services produced by firms
- 33What is SR production?where there is at least 1 fixed factor input (usually K)
output expands in the SR when more variable factors are brought into use - 34What is LR production?all of the factors of production can change, allowing a firm to change the scale of it's operation
- 35What is productivity?a measure of the efficiency of a factor input
- 36What are costs of production?expenses faced by a business producing a good or service
- 37What are fixed costs?they do not vary directly with the level of output
- 38Give an example of fixed costsrent paid on buildings
- 39What are variable costs?costs that can vary directly with output
- 40Give an example of variable coststhe costs of raw materials and components
- 41When there are fixed costs, what happens if the total volume of goods produced increases?the lower the fixed costs per unit because costs are spread over a high number of units
Information
- Description
- AS - Level Economics (Microeconomics) Flashcards on 4 ~ Supply, created by Tara Pugal on 24/04/2016.
- Created by
- Tara Pugal
- Views
- 14
- Tags
- Rating