
Notes
Economics - Module 2 - Unit 1
Content of the notes (1)
Page 1
Unit 1 - The Economic Cycle
A key
objective of Government is to increase the total output of goods and services
produced and consumed within the economy because this leads to higher
employment and living standards.
This
output is called the Gross Domestic
Product and is calculated by adding up the total output of all producers
within the UK Economy.
The
economy is divided into three sectors:
1. The primary sector - this is the sector involved in the production of raw materials, e.g.:
Farming - food
Fishing - within the Eurozone
Mining - coil, oil, shale gas
Forestry - Northern Europe
This is all mostly imported
2. The secondary sector - includes suppliers who turn raw materials into finished goods. This sector includes:
1) Manufacturing
Cars - Toyota, Jaguar-Land Rover, Honda, VW, Ford, Nissan...
Defence
Aeroplanes - Rolls Royce, Airbus
High tech goods - Toshiba, Panasonic
2) Construction
3. The tertiary sector - includes suppliers who provide any type of service:
Education, Healthcare, Financial, Legal, Law enforcement, Armed forces, Retail & wholesale, Tourism, Media and Personal.
The Growth of the UK Economy:
Economic
growth is the increase in the productive capacity of the UK economy and this
is measured by the change in real GDP.
GDP is
the monetary value of the total output produced in each sector.
This
is measured both quarterly and annually.
The
measure is adjusted for inflation to calculate whether output has risen or
fallen.
The
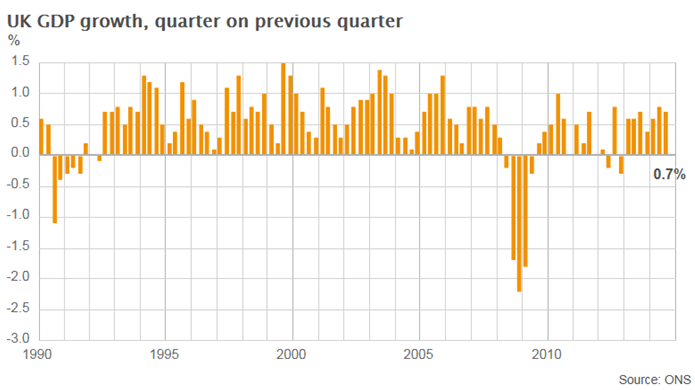
percentage changes in GDP between
one quarter and the next is the indicator used to measure economic growth.
Economic growth is positive when the
value of GDP growth is above 0 and this implies the output of the economy has
increased over the quarterly period.
Economic growth is negative when the
value of GDP growth is below 0 and this implies the output the economy has
decreased over the quarterly period.
An economic recession occurs when GDP
growth is negative for two consecutive quarters or a period of six months.
Key dates of the two recessions
1990 - Q3 - The economic recession of 1990/91 lasting 5 quarters, where the economy contracted by a total of -2.3%.
2008 - Q2 - The economic recession of 2008/09 lasting 5 quarters, where the economy contracted by a total of -6.2%.
The recession of 2008/09 lasted the same time, but the economy contracted deeper by -3.9%.
The
Economic Cycle:
The economy therefore does not grow at a
constant rate every quarter but fluctuates and is characterised by phases of
-Growth -Recession -Boom -Slump -Upturns -Downturns
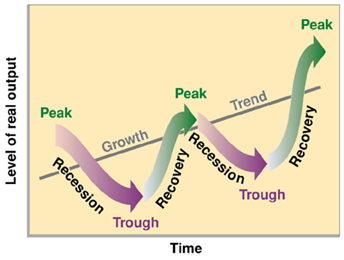
-Economic growth is a phase of the
economic cycle when the productive capacity is growing and GDP growth is
positive.
-An economic recession is phase of the economic
cycle when economic growth is negative
for two consecutive quarters and means the productive capacity of the economy
is shrinking.
-A boom
is a phase of the economic cycle when economic growth is growing above its
trend rate of growth which for the UK has been calculated at about 2.25%-2.5%. This means output is above a level that the
economy can be sustained over the long term.
-A slump
or depression is a prolonged recession where GDP
shrinks by more than 10%. The last slump
experienced by the UK was in the 1930’s which lasted from all of this decade
and only came to an end as a result of World War 2. The Wall Street Crash was a signal that the
global economy was entering a severe downturn.
Some are worried that the recent financial crash may signal a slump of
similar proportions.
-An upturn
means economic growth is accelerating and productive capacity (output) is
growing at an increasing rate. A rise
from 0.5% to 1.5% quarterly growth is an example.
-A downturn
means economic growth is slowing down and output is growing at a decreasing
rate. A fall in growth from 2.4% to
1.1% is an example. The economy is still
growing but at a slower rate.
-A double
dip recession means that two periods of negative growth have occurred one
after the other without the economy returning to its trend rate of growth for a
sustained period in between.
How Economic growth affects output
Output can be classified into:
a)
Consumer goods food, clothing and shelter that
satisfy human demand
b)
Capital goods such buildings and machines that
produce consumer goods.
Economic growth can be illustrated using
a production possibility frontier.
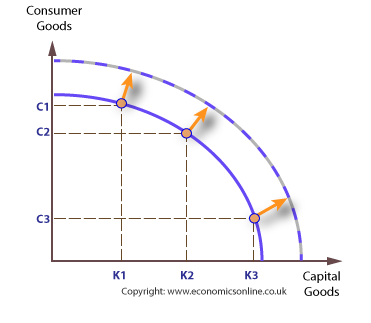
The production possibility frontier is
curved to illustrate how there is a limit to the productive capacity of the
economy.
Economic growth is illustrated by an
outward shift of the PPF
Economic recession is illustrated by an
inward shift of the PPF
Investment
in capital goods is the key to generating economic growth.
Consumer goods are favoured in production to capital goods (C1,K1).
Economic growth implies a rise in output, employment and living standards.
The benefits of economic growth
Economic growth is desirable because it generates
benefits for consumers, producers and society:
Economic growth means the productive
capacity of the economy has risen.
1.
This means a higher level of output of good and
services. This can be illustrated by an
increase in the production possibility frontier.
2.
This means that the supply of capital good has
risen and this will result in more consumer goods being available.
3.
This will create more jobs in the economy
leading to higher wages, salaries and consequently living standards.
4.
Technological improvement will result in better
quality goods at cheaper prices.
5.
Consumers will have more disposable income to
spend on consumer durables such as property and services.
6.
Higher tax revenues for the state will allow
higher spending on merit goods such as health and education.
7.
Growth encourages further increases in
enterprise and investment.
8.
Firms benefit from higher profits which can be
used to finance new investment.
Therefore economic growth leads to
higher levels of output, employment, wages, profits and living standards.
Government benefits from higher tax revenues leading
to better public services such as health and education.
GDP
per Capita
GDP per capita is
calculated by dividing GDP by population,
and is a more accurate measure of the increase in living standards because it
provides a crude monetary measure of how resources are divided amongst the
population of that country.
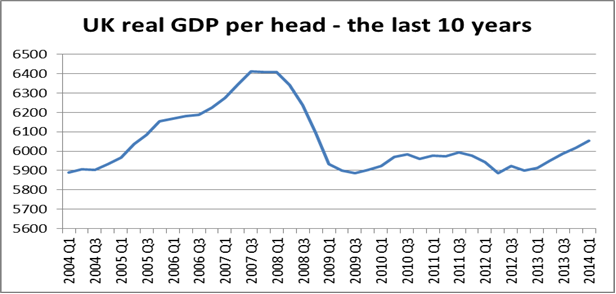
GDP per capita is calculated as: GDP / Population.
In theory, a rise in economic growth would mean a rise in GDP, and therefore a rise in GDP per capita.
However, since 2008 GDP per capita has not seen a significant increase despite a growth in the economy. This is due to the significant population growth was has grown quicker than Real GDP. Factors contributing to population are immigration, a rise in the birth rate and a fall in the death rate.
Economic Growth and the Price Level
Economic growth measures changes in real
GDP and therefore the effects of inflation have been removed.
This means economic growth measures the
change in actual output.
Inflation is a measure of the average
rise in prices. It is calculated by
comparing the price of a basket of goods and services over a period of time.
The
basket includes a selection of goods and services that the typical family buy
on a regular basis.
In
the UK,
an index called the consumer price index (CPI) is used to measure changes in
the average price level.
Value of total output - % Change in GDP - % Change in Inflation
E.g.
In 2010 GDP was £100bn, and in 2011 it was £110bn.
The rise in GDP in money terms = 10%
Inflation during this period was was 6%
Total economic growth = 10% - 6% = 4% GDP.
Therefore,
the value for real GDP or economic
growth will have been adjusted for the increase in prices that will have taken
place during this period.
The use of Index Numbers to express data:
Nominal - GDP NOT adjusted for inflation, and is valued using current prices for that period.
Constant - GDP adjusted for inflation, and so must be expressed according to a base year.
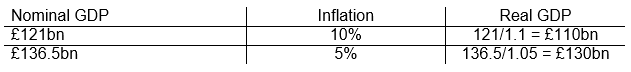
2004: Nominal GDP - £121bn ~ Inflation index - 10% ~ Real GDP - 121/1.1 = £110bn.
2005: Nominal GDP - £136.5bn ~ Inflation index - 5% ~ Real GDP - 136.5/1.05 = £130bn.
Hence, Real GDP = Nominal GDP / Infation Index (as a decimal.)
GDP Growth = Growth / Base Real GDP x 100%.
GDP Growth = £20bn / £110bn x 100% = 18%.
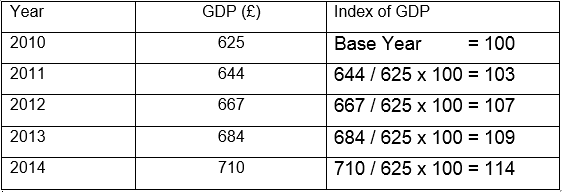
To calculate index:
1. Select a base year e.g. 2010 (£625bn).
2. Use the formula for each year: Current GDP / Base GDP x 100
E.g. 2012 - 667 / 625 x 100 = 107%.
3. Precentage of annual growth = % Change / Previous Index x 100
E.g. 2012 - 4 / 103 x 100 = 3.9%.
The Circular Flow of Income
Macroeconomics is concerned with the
economy as a whole and therefore focuses on output, employment, inflation and
trade.
National output is considered the key
indicator to the health of the economy.
A healthy economy is one when the
national output is growing while an unhealthy economy is one when national
output is contracting.
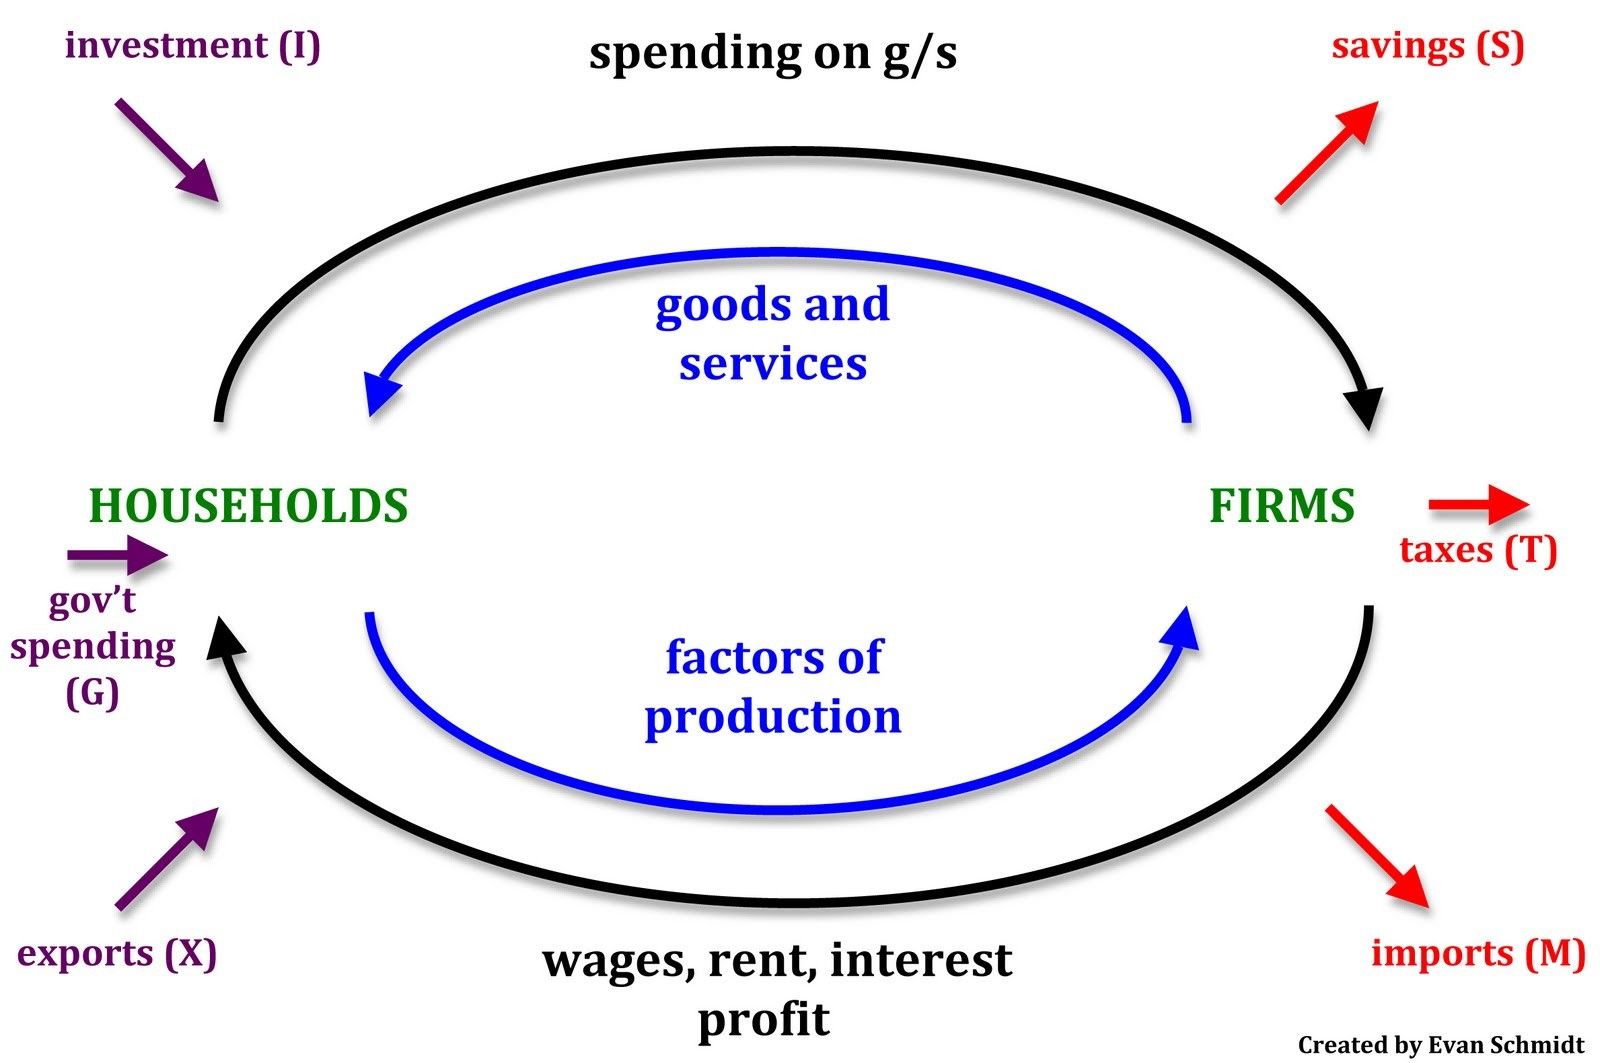
1.
Households own the factors of production such
as land, labour and capital which they supply to firms in return for an income
in the form of wages, rents and dividends.
2.
Firms produce all the goods and services by
hiring or renting factors of production from households.
3.
Households used their income to buy finished
goods and services from firms.
4. This produces three flows that can be
measured:
a)
The output
of goods and services from firms.
b)
The income
of household.
c)
The expenditure
by households on goods and services.
Income =
Expenditure = Output
It is assumed in this simple model that
all income is spent on buying goods and services.
Injections and Withdrawals
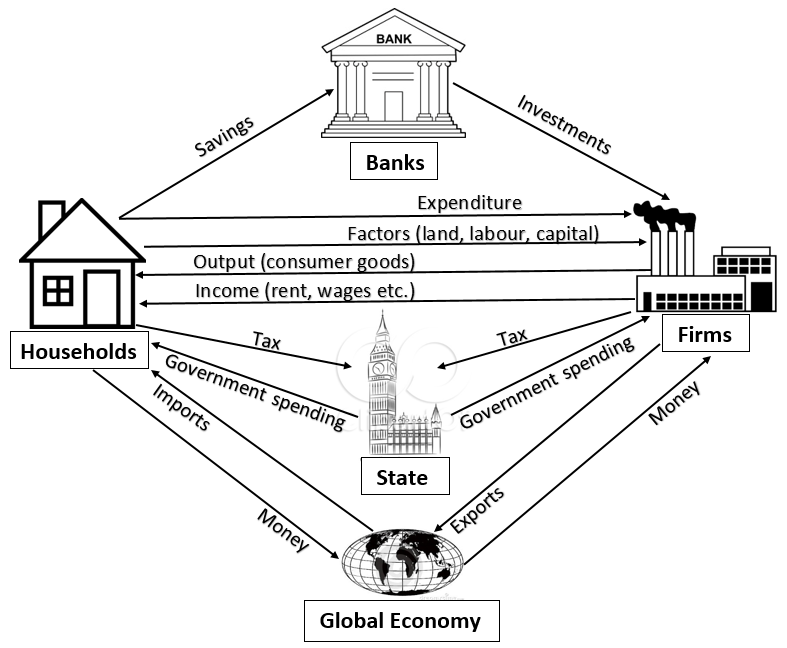
Injections are sources of income that cause the
economy to grow such a:
1.
Investment
spending by firms on
capital goods such as
Factories and warehouses
Equipment and machinery
Buildings and offices.
2.
Government spending on
Education, healthcare, defence, welfare, defence, public order, housing and infastructure.
3.
Exports which are goods produced in the UK but sold
abroad and therefore bring in income such as
Food and drinks
Alcohol and tobacco
Cars and aeroplanes
Drugs and medicine
Oil.
Withdrawals cause the economy to contract such as:
1. Savings
is the part of
disposable consumer income that households choose not to spend, but is invest in
Banks, shares, pensions and bonds.
2. Tax
is that part of gross household income that the
government takes and can be in the form of
Excise tax (alcohol and tobacco)
Value Added Tax (VAT)
National insurance
Council tax, road tax and income tax
Corporation tax.
3. Imports
are that part of
household income that is spent on goods produced outside the UK and therefore
is not received by UK firms. Almost every item The UK exports can also be imported.
Measuring
income, expenditure and output
The value of national income and output
is measured in three simple ways:
1.
The
Office of National Statistics
calculates the value of quarterly GDP
in the following way
Information on sales is collected from 6,000 companies in
manufacturing, 25,000 service
sector firms, 5,000 retailers and 10,000 companies in the construction sector.
Data is also collected from government departments covering
activities such as agriculture, energy,
health and education. This is augmented by a wide range of sources which ensure that activity in
the economy is well covered.
This
method is considered the most accurate in the short term.
2.
The department of Revenue
and Customs is able to provide a measure of national income from
information calculated on tax receipts such as income tax and VAT.
However,
this measure would not be able to provide a
quarterly calculation of GDP because the self employed and firms pay their tax annually.
Information
- Description
- A levels Economics (Module 2: The National and International Economy) Note on Economics - Module 2 - Unit 1, created by Amardeep Kumar on 26/03/2015.
- Created by
- Amardeep Kumar
- Views
- 67
- Tags
- Rating
More on GDP and national income