
Notes
IATA Report: The Impact of September 11 2001 on Aviation
Content of the notes (3)
Page 1
Foreward
On September 11, 2001 anyone associated with
aviation knew that the industry would never be the
same.
What we did not know was how resilient the
industry would be in the aftermath of the tragedy or
the direction in which it would change.
A decade after the event, there can be no doubt about
aviation’s resilience. By 2004 revenues and traffic
surpassed 2000 levels.
And by 2006 aviation had
returned to profitability—albeit with a weak 1.1% margin. In the interim airlines dealt with SARS, additional terrorist
attempts, wars, and rising oil prices.
It took three years to recover the $22 billion revenue drop
(6%) between 2000 and 2001. When the global financial
crisis struck in 2008, 2009 revenues fell by 14% ($82
billion) to $482 billion. This was largely recovered in
the following year when industry revenues rose to $554
billion and airlines posted an $18 billion profit. Clearly the
restructuring of the decade has left airlines leaner and more
resilient in the face of crisis.
Over the decade, the dimensions of global aviation have
also changed. IATA expects 2011 airline revenues of $598
billion—nearly twice the $307 billion of 2001. Airlines are
also expected to carry 2.8 billion passengers and 48 million
tonnes of cargo. That’s a billion more people flying and 16
million more tonnes of cargo than in 2001.
While it is difficult to isolate the impact of the events of
2001, we can say that they were a part of a chain of events
that cost the industry three years of growth. The 2008
global financial crisis cost another two years of growth.
The legacy of 9.11 is felt most in airport security. Aviation is
more secure today than in 2001. But this has come at a great
price in terms of passenger convenience and industry costs.
As we move forward, there are five major lessons in security
over the last decade:
Governments must coordinate the development and
deployment of security measures to ensure harmonized
global standards and eliminate overlapping and
redundant requirements among nations.
Governments are obliged to foot the bill for security
threats which are national challenges in the same
manner as they would do in any other sector. Airlines
and their passengers currently pay a security bill that
had ballooned to $7.4 billion by 2010.
Passengers should and do play an important role in
helping keep air travel safe. Vigilance and cooperation
with authorities are crucial.
Governments need to embrace a risk-based approach
to security screening.
We must accept that there is no such thing as 100%
risk-free security. Governments must focus on the
probable and not all that is possible and avoid policies
driven by knee-jerk reactions.
A good place to start is by removing the hassle that comes
between check-in and boarding at many airports. The
building blocks to do a better job exist. The vision for IATA’s
Checkpoint of the Future is for passengers to be able to get
from curb to gate in a seamless and convenient process. For
this, we need a risk-based approach to security powered by
the enormous amount of data that we can and do collect on
travelers. Combined with this will be technology that will allow
most passengers to simply stroll through a checkpoint that
can detect metal and harmful substances without stopping,
stripping or unpacking.
Parts of this vision could be realized with technology that
exists today. Others are in development with a three to
seven year horizon. The important thing is to keep focused
on evolving the 40-year-old concept of today’s airport
checkpoint into one that is more convenient, more effective
and that can handle the ever increasing volume of people
who want and need to fly.
Finally, as we commemorate the tragedy of 9.11, the
thoughts and prayers of the industry are with the families
of the victims—passengers, crew and bystanders. Our best
tribute to their memories is a resilient aviation industry.
Aviation is a force for good and an instrument of peace that
promotes trade, spreads wealth and facilitates understanding
among the peoples and cultures of our world.
Page 2
The Financial Impact of 9.11
9.11 was the beginning of the most challenging decade in
aviation history. But it is important to note that the industry
was already in a weak financial position. World trade had
slowed and the ‘dot.com bubble’ had burst the year earlier.
Global airline profits had fallen from $8.5 billion in 1999 to
$3.7 billion in 2000.
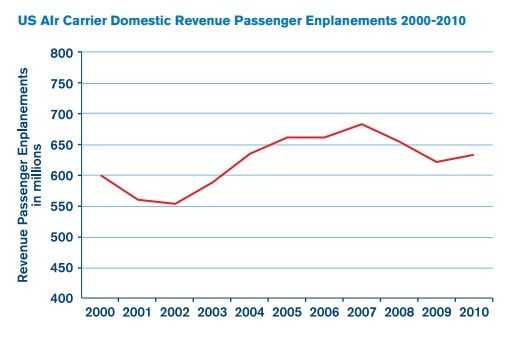
US Impact
• Air Space Closed: On September 10, 2001, US
airports handled 38,047 flights. On September 12,
they handled 252 commercial flights. One week later
(September 18) there were 34,743 flights.1
• Passenger Traffic: US passenger traffic, measured
by revenue passenger kilometers (number of travelers
multiplied by the distance traveled) declined 5.9%
in 20012 (compared to 2000) and a further 1.4%
in 2002. Airlines struggled to match this decline by
cutting capacity (available seat kilometers or number
of seats multiplied by distance traveled) by 2.8% in
2001 and a further 3.9% in 2002. This was the first
time since World War II that industry capacity declined
for two consecutive years. After stabilizing in 2003,
capacity growth resumed in 2004 and continued
until 2008, when it declined again owing to soaring
oil prices and the global financial crisis. Capacity
fell further in 2009, returning virtually to 2000 levels.
Between 2000 and 2009, the US commercial aircraft
fleet shrank by around 700 units.
• Domestic Market: “The events of 9.11…marked
a permanent decline in [US] domestic airline
demand”—Barclays Capital, February 2009. Total
domestic operating revenue per $100 of nominal US
GDP declined from around US$0.823 in 2000 to
US$0.687 in 2010, representing a shortfall of $18
billion for 2010 and $142 billion for the 2001-2010
period.3 Passengers found alternatives to short-haul
travel to avoid the security hassles at airports. Network
carriers shed their domestic operations to regional
Page 3
Global Impact
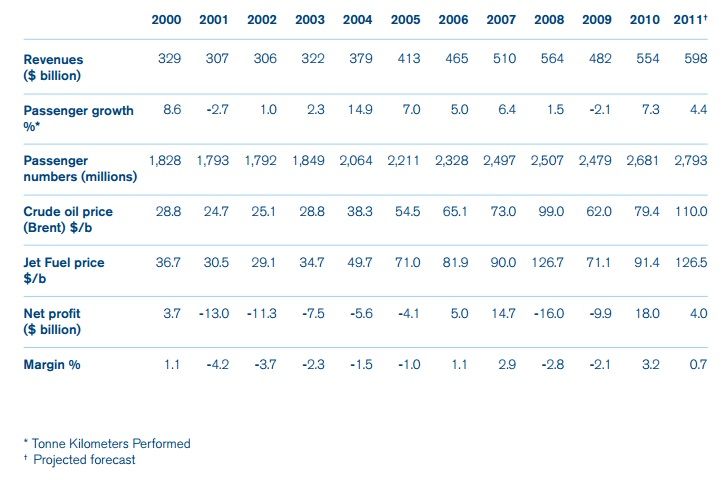
Traffic: Global passenger traffic (tonne kilometers
performed) declined by 2.7% in 2001 (see table
below). Traffic did not surpass the 2000 level until
2003. It continued to rise until 2009 when, owing to
the global financial crisis, it declined 2.1% year-onyear.
• Revenues: Global airline revenues declined from
$329 billion in 2000 to $307 billion in 2001 and
further to $306 billion in 2002. Revenues rebounded
to $322 billion in 2003 and then to $379 billion in
2004. The next revenue dip was in 2009 when they
fell $82 billion to $482 billion. In percentage terms
this 14% drop was more than twice the decline
experienced in 2001-2.
• Profitability: Airlines lost $13 billion in 2001 and a
further $11.3 billion in 2002.The industry recorded
its first post-September 11 annual profit in 2006
($5 billion), and earned $14.7 billion in 2007. The
following year rising oil prices and the global financial
crisis plunged airlines back into the red with 2008-9
total losses of $25.9 billion.
• Bankruptcies: Within months of the attacks, Swissair
and Sabena went bankrupt as the 9.11 shock pushed
these financially weak carriers into collapse.
• Oil price: In the decade since 9.11 the industry fuel
bill rose from 13% of costs (2001) to 30% (projected
for 2011).
Information
- Description
- Note on IATA Report: The Impact of September 11 2001 on Aviation, created by Sarah Egan on 13/04/2017.
- Created by
- Sarah Egan · Apr 2017
- Updated
- Aug 23, 2017
- Views
- 196
- Tags
- Rating